

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Soy Milk Market to Hit USD 17.63 Billion by 2032

Soy Milk Market 2026 Outlook: Strategic Imperatives for Growth, Resilience and Differentiation
PW Consulting today releases a forward-looking briefing that synthesizes our proprietary analysis of the global soy milk market through 2032. Drawing on an expanded historical base (2020–2025) and a detailed forecast period (2026–2032), the study frames the competitive, supply‑chain and consumer dynamics that will determine winners and laggards in 2026. Our core takeaway: the soy milk sector is maturing into a structurally larger, yet selectively consolidating, market where strategic choices on product formulation, channel playbooks and raw‑material management will have outsized P&L consequences.
Soy Milk Market
Market at a Glance (what the numbers mean for strategy)
By our base year (2025) the global soy milk market reached roughly USD 11.7 billion (revenue expressed in USD Million), and it is projected to expand at a steady compound annual growth rate (CAGR) of approximately 6.02% through our forecast window (2026–2032). By the terminal year of the forecast the market is expected to exceed an estimated USD 17.6 billion, reflecting both volume growth in mature markets and value uplift from premiumization, protein fortification and convenience formats in growth markets.
Soy Milk Market
Two structural signals emerge from the sizing and concentration metrics: first, growth is broad‑based and resilient—increasing consumer interest in plant-based proteins, coupled with product innovation, supports durable demand. Second, the market exhibits moderate concentration (our report quantifies leading-three and leading-five concentration ratios), indicating room for regional champions, private-label escalations and targeted M&A by global players seeking scale and capability gaps.
Soy Milk Market
What the PW Consulting report delivers (practical, transaction-ready intelligence)
- Robust market-sizing and scenario forecasts (bottom‑up and top‑down reconciliations) calibrated to raw‑material price scenarios and demand shocks.
- Segment playbooks for product types, packaging formats and distribution channels that translate consumer trends into SKU and pricing recommendations.
- Supply-chain and procurement modeling that maps soybean cost pass-through, inventory strategies and hedging levers under alternative USDA and FAO price paths.
- Competitor and capability heatmaps, including comparative analysis of scale, channel footprint, innovation cadence and private‑label exposure.
- M&A and partnership scouting: prioritized target archetypes, valuation multiples observed in recent deals and integration risk checklists.
- Regulatory, sustainability and labeling impact assessment—practical compliance steps for market entry and claims management.
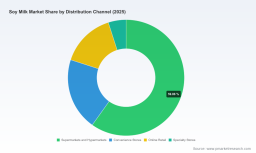
- Playbook for commercial execution: route‑to‑market playbooks for supermarkets, convenience, foodservice and e‑commerce, including SKU rationalization templates and margin waterfall tools.
Market dynamics shaping 2026 decisions
- Raw‑material volatility: Recent agricultural reports and commodity indices point to renewed price pressure and tightening crush demand dynamics. Procurement and sourcing strategies must be stress‑tested against price scenarios and supply‑disruption shocks.
- Premiumization and functionalization: Higher‑protein and clean‑label offers are capturing incremental shelf space and command higher price points. Firms that can credibly deliver complete‑protein messaging or clinically backed functional claims will unlock new margin tiers.
- Channel polarization: Brick‑and‑mortar remains the backbone for trial and repeat, but online and direct‑to‑consumer channels are accelerating conversion for premium and subscription models. Channel economics differ materially—assessments of CAC, return rates and logistics costs should inform product‑by‑channel allocations.
- Regional demand nuances: Growth is geographically heterogeneous—strategic market entry or expansion requires granular go‑to‑market playbooks built from local consumer occasion mapping rather than one‑size‑fits‑all rollouts.
- Regulatory and consumer scrutiny: Clean‑label and sustainability claims are increasingly audited by regulators and NGOs; traceability and certification (organic, non‑GMO, regenerative sourcing) are becoming tangible competitive differentiators.
Competitive landscape — who matters and why
The market is populated by global consumer goods giants, regional beverage specialists and agile natural‑foods challengers. Our report includes competitor dossiers and strategic positioning for the following industry participants (selected): Danone S.A. (Silk, Alpro), Vitasoy International, Kikkoman, Eden Foods, Pacific Foods (Campbell Soup Company), SunOpta, The Hain Celestial Group, Califia Farms, Organic Valley, WestSoy and several focused organic challengers. Each represents a different strategic posture:
- Global incumbents (e.g., Danone) leverage scale, R&D and multi‑channel reach to push premium protein blends and refrigerated high‑protein SKUs.
- Regional champions (e.g., Vitasoy) capitalize on entrenched distribution in Asia and local taste adaptation to defend share and expand adjacent categories.
- Natural/organic specialists (e.g., Eden Foods, Pacific Foods, WestSoy) exploit clean‑label authenticity and premium shelf tags to capture health‑oriented cohorts.
- Innovators and insurgents (e.g., Califia Farms) drive category renewal through minimalist formulations, branding and DTC engagement.
Recent industry moves signal where competition is converging and diverging. Notable product launches and developments in early 2026 include high‑protein refrigerated offerings from established brands, clean‑label soy variants from insurgent players, new soy‑based snacks and renewed promotional activity emphasizing health benefits. Our report provides a deal‑flow tracker and decision matrix to interpret whether new launches are scale plays, co‑opetition, or category expansion tactics.
Actionable strategic recommendations for 2026
- Hedge and diversify raw‑material exposure: Implement layered procurement combining forward contracts, index‑linked sourcing and strategic buffer inventories. Stress‑test commercial plans with +/‑ 20% soybean feedstock scenarios.
- Prioritize protein and simplicity: Rebalance R&D spend toward high‑protein, nutrient‑complete formulations and minimal‑ingredient variants. Use targeted consumer testing to validate premium price elasticity.
- Channel‑specific assortment and pricing: Rationalize SKUs by channel—allocate higher‑margin premium SKUs to e‑commerce and subscription while optimizing shelf SKUs for mass channels to reduce in‑store clutter and improve turns.
- Capitalize on adjacent formats: Evaluate high‑margin product adjacencies (creamers, ready‑to‑drink single‑serve, soy‑based snacks) as margin diversifiers and as on‑ramp products for new consumers.
- M&A and strategic partnerships: Seek bolt‑on acquisitions that deliver either procurement scale, cold‑chain capabilities or IP in plant‑protein formulations. Our report ranks target archetypes and highlights integration red flags.
- Sustainability as risk management: Convert sustainability claims into procurement advantage—traceability, regenerative premiums and supplier partnerships reduce long‑term cost exposure and enhance buyer loyalty.
Why this report is mission‑critical for 2026 planning
2026 will be a year where execution and choices determine relative market position. Volume alone will not secure leadership; it will be the combination of (a) disciplined supply‑chain risk management, (b) product differentiation tied to credible health and sustainability claims, and (c) channel economics optimization. PW Consulting’s soy milk study provides the integrated modeling, commercial playbooks and competitor intelligence that boards, commercial leads and M&A teams need to convert market growth into durable value.
How our analysis supports near‑term decisions
- Use our scenario outputs to set procurement trigger points and pricing corridors for 2026; incorporate the model into monthly trading and budgeting cycles.
- Adopt our SKU rationalization framework to free up promotional space and reduce inventory carrying costs while preserving consumer choice in key channels.
- Leverage the competitive dossiers to benchmark R&D spend, time‑to‑market and NPD success metrics versus peers.
Next steps and access to full intelligence
This briefing highlights the strategic contours of a detailed, actionable body of work. The full PW Consulting Soy Milk Market Report includes the proprietary regional and channel splits, unit economics, supplier scorecards and a downloadable scenario modeling tool that we intentionally withhold here to preserve the commercial value of the research. To obtain complete datasets, model files and our prioritized go‑to‑market checklist for 2026, please request the full report via PW Consulting’s research portal or contact your advisory lead.
PW Consulting’s team stands ready to support tailored strategy workshops, M&A diligence, or procurement optimization pilots derived from the report’s findings. 2026 will reward organizations that pair decisive capital allocation with operational rigor; this report is designed to make that pairing repeatable and measurable.
For detailed analysis of this topic, please visit the official page: Soy Milk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com