

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Orthodontic Aids Market Poised to Reach USD 13.85 Billion by 2032, Driven by an 8.45% CAGR

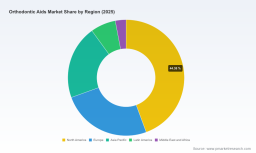
Orthodontic Aids Market — Strategic Preview for 2026 Decisions
PW Consulting’s new Orthodontic Aids Market study delivers a concise but strategically rich preview designed for executive teams, investors, product leaders and clinical operations to align 2026 priorities with the market’s accelerating trajectory. The global market has shown sustained expansion over the past half-decade, rising from USD 5,122.34 Million in 2020 to USD 7,850.50 Million in 2025, with our forecast placing the market above USD 8,900 Million in 2026 and climbing toward USD 13,851.73 Million by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of 8.45% across the 2026–2032 forecast window — a pace that demands proactive repositioning across product, regulatory and go‑to‑market strategies.
Orthodontic Aids Market
Why this report matters for 2026 planning
-
Market momentum: The size and growth rate indicate both rising clinical adoption of aesthetic and digital orthodontic solutions and continued investment by both incumbent medical device groups and specialist manufacturers.
Orthodontic Aids Market -
Consolidation and concentration: The market exhibits meaningful concentration at the top — the leading firms capture a majority share of industry revenue — creating both barriers and pathways for scale-seeking challengers.
Orthodontic Aids Market -
Regulatory and reimbursement inflection points: Device-class regulation, updated CDT codes effective January 1, 2026, and evolving EU conformity requirements are reshaping product lifecycles and commercial playbooks.
-
Technology disruption: Digital scanning, AI diagnostics and integrated digital workflows are no longer optional; they change clinical pathways, supplier economics and patient acquisition dynamics.
What the report contains — practical, actionable deliverables
-
Market sizing and trajectory models: A transparent methodology that reconciles historical sales (2020–2025) with near-term projections and scenario-based outcomes for 2026–2032.
-
Decision-grade financial templates: Unit economics, margin bridges and sensitivity analyses tailored for OEMs, distributors and DSOs to stress-test pricing, product mix and service bundling.
-
Regulatory and reimbursement playbooks: Step-by-step guidance for 510(k) strategies in the U.S., MDR/Class IIa compliance in Europe, and the operational impact of the 2026 CDT code changes.
-
Competitive intelligence dashboards: A structured view of capabilities, route-to-market models and innovation focus areas across the industry’s most active players.
-
Go-to-market and partnership blueprints: Channel optimisation, DSO engagement tactics, lab integration and partnerships with digital imaging/AI providers.
-
M&A screening and integration checklist: Valuation levers, cultural/operational fit criteria and a 100‑day integration playbook for bolt-on acquisitions or strategic alliances.
-
Priority investment roadmaps: Tactical recommendations for R&D, manufacturing scale-up, and pilot programs that can be executed within 6–18 months to capture share in 2026.
Competitive landscape — who matters and why
The competitive environment blends global medical device groups, specialist orthodontic manufacturers and distribution-led incumbents. Market concentration metrics show that the top three participants account for a little over half of the market, while the top five firms deepen that leadership position. This structure creates asymmetric advantages for firms that combine scale in manufacturing, broad clinical channels, and digital services.
-
Align Technology, Inc. — A clear-aligner pioneer whose ecosystem (aligners, intraoral scanners and retention solutions) demonstrates the commercial power of integrated hardware + consumables + software. Recent regulatory progress on targeted attachment and expansion systems underscores the company’s cadence of product approvals and market rollouts.
-
3M — A diversified technology company with deep reach into traditional brackets, wires and aesthetic solutions; its R&D and distribution scale make it a durable competitor across both fixed and aesthetic segments.
-
Envista (Ormco and related brands) — Strong in bracket/wire system innovation and laboratory workflow efficiency: an important competitor for clinical customers focused on speed and predictable biomechanics.
-
DENTSPLY SIRONA — Presents a mixed model: clinical consumables and a direct-to-consumer footprint in the past, alongside clinical devices and vibration adjuncts; recent recognition for partnership-based cleft care highlights a growing services and CSR dimension to commercial strategy.
-
Institut Straumann AG — Leveraging implant/restorative connections and digital treatment planning to deliver end-to-end clinical workflows that can lock in practice-level adoption.
-
Specialist manufacturers and distributors — Firms such as American Orthodontics, Rocky Mountain Orthodontics, G&H, Dentaurum, Henry Schein Orthodontics and DB Orthodontics continue to control important product niches (precision brackets, engineered archwires and consumables) and provide local distribution muscle.
Together, these profiles show two dominant commercial archetypes: (1) integrated digital platforms that capture value across the treatment pathway, and (2) component specialists that win on cost, reliability and clinician preference. Strategic positioning for 2026 requires addressing both models.
Regulatory and market dynamics shaping near-term strategy
-
Device regulation: Clear aligners and brackets are predominantly regulated as Class II devices in the U.S., requiring 510(k) clearance demonstrating substantial equivalence. The European transition continues to be defined by MDR/Class IIa requirements and material biocompatibility scrutiny.
-
Reimbursement: CDT code updates effective for claims in 2026 introduce nuances that will affect case mix economics, particularly for procedures tied to digital workflows and adjunctive devices.
-
Direct-to-consumer disruptions: The industry has seen how DTC aligner models create reputational, regulatory and legal risk; certain consumer-focused operations have already adjusted their market presence in response to compliance pressure.
-
Technology infusion: In 2026, we’re seeing regulatory clearance for AI-driven imaging tools and continued product approvals for innovative attachments and expansion systems — both of which will alter diagnostic and treatment-planning economics.
Recent developments that matter for 2026 tactics
-
A series of product and regulatory milestones (including approvals for new aligner attachment systems and palatal expanders, and AI-enabled imaging clearances) are accelerating the digitization of orthodontic care and expanding the set of permitted clinical tools.
-
New aesthetic bracket system launches and continued partnership activity around cleft care and global programs show manufacturers are combining product innovation with reputational and CSR strategies to broaden market access.
Practical recommendations for executives planning 2026 moves
-
Prioritise digital integration. Investing in intraoral scanning, AI diagnostics, and interoperable patient management systems is table stakes. Pursue partnerships or licensing where organic development is slower than market demand.
-
Build a regulatory roadmap. Treat 510(k) and MDR compliance as strategic milestones: allocate resources to clinical validation and post‑market surveillance to shorten time-to-market for adjacent products.
-
Reassess channel strategy. For manufacturers, a hybrid model that blends direct digital channels with strengthened DSO and clinic partnerships is the most resilient approach as reimbursement and procurement models evolve.
-
De-risk supply and manufacturing. The margin impact of component shortages can be material; diversify sources for specialty polymers, nickel-titanium alloys and outsourced fabrication early.
-
Use clinical and economic evidence to win placement. Outcome data, ROI models for clinics and case studies for DSOs shorten sales cycles and justify premium pricing for differentiated systems.
-
Targeted M&A and alliances. Consider bolt-ons that provide digital capabilities (AI, scanning, treatment planning) or lab capacity rather than purely geographic roll-ups. Integration playbooks are critical to capture value post-deal.
Why PW Consulting’s study is the strategic tool you need now
This report is purpose-built as a decision-support asset for 2026: it converts macro market performance (notably our observed expansion from 2020 through 2025 and the 8.45% forward CAGR) into executable options, prioritized actions and quantified scenarios. Our analysts combine vendor-level intelligence, regulatory mapping and commercial modelling to produce a compact set of levers CFOs and heads of strategy can implement in the next two quarters.
Note: following our “trailer” principle, this public preview intentionally omits the full set of granular regional splits, product-level revenue tables and application-specific unit economics. Those detailed segment tables, granular regional forecasts and downloadable financial models are available in the full PW Consulting Orthodontic Aids Market report and accompanying data workbook.
Next steps
-
For executive teams evaluating portfolio pivots: request the model workbook to run custom scenario analyses (pricing, reimbursement shifts, and channel changes).
-
For investors conducting diligence: obtain the competitive dashboards and M&A screening annex to assess target synergies and valuation levers.
-
For product and regulatory leads: access the compliance playbook and product approval timelines to prioritize 2026 submissions and clinical studies.
PW Consulting is ready to brief your leadership team on how these market dynamics translate into concrete profit-and-loss outcomes for 2026. Visit our report page to access the full dataset, proprietary segment breakdowns and scenario-enabled financial models.
For detailed analysis of this topic, please visit the official page: Orthodontic Aids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com