

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts DDR RAM Market to Surge from USD 118.4 Billion in 2025 to USD 264.72 Billion by 2032 at a 12.18% CAGR

PW Consulting Release: DDR RAM Market Research — Strategic Playbook for 2026 Decision-Makers
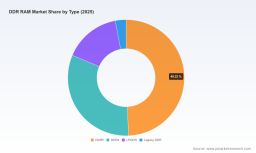
PW Consulting today publishes a strategic preview of its forthcoming DDR RAM Market Research report, designed to equip C-suite leaders, procurement heads, product architects, and investors with the high-conviction insights they need to navigate the memory market in 2026. Anchored on a robust base year (2025) and a 2026–2032 forecast horizon, the research maps an industry that is simultaneously expanding and rebalancing: the global DDR RAM market recovered from multi-year volatility to an estimated 118.4 USD Billion in 2025 and is projected to grow toward the mid-2020s trajectory, reaching roughly 264.7 USD Billion by 2032 at a compounded annual growth rate of 12.18%. This preview sets out the implications of that trajectory while deliberately preserving the proprietary segmentation matrices and granular tables that are available in the full report.
Ddr Ram Market Research
Executive summary — What this preview delivers
-
Actionable signal: synthesis of supply-side strategic shifts and demand pockets driven by AI, cloud, and mobile evolution.
Ddr Ram Market Research -
Risk framing: an independent assessment of supply constraints, pricing pressure, and policy risks that will matter to 2026 procurement cycles.
Ddr Ram Market Research -
Competitive positioning: concise profiles of incumbent and emerging suppliers and what their strategic choices mean for buyers and partners.
-
Practical next steps: concrete options for contracting, redesign, hedging, and partnership that enterprises can operationalize this year.
Macro dynamics shaping 2026 strategy
The memory market is no longer a simple demand-led commodity story. Over 2020–2025 the sector showed pronounced cyclicality; by 2025 it had consolidated into a more predictable growth path, yet one characterized by structural reallocation of wafer capacity. Leading manufacturers redirected significant capacity toward high-bandwidth memory (HBM) to serve AI accelerators and adjacent high-margin segments. The reallocation has tightened supply for mainstream DDR families and injected volatility into contract and spot pricing.
These supply-side choices coincided with standards and specification updates that change the adoption curve for next-generation module types. Recent JESD releases through 2025 updated DDR5 performance, reliability, and SPD frameworks and introduced new mobile memory standards — developments that accelerate technology transitions but also raise validation and BOM complexity for OEMs. Meanwhile, macro policy signals from early 2026 around processed critical minerals and continued export controls on advanced manufacturing equipment add a second-order layer of geopolitical supply risk to sourcing strategies.
Price and supply signals buyers must treat as strategic
Late-2025 and early-2026 market dynamics demonstrated how quickly procurement windows can close. Contract price inflation for advanced DDR variants surged substantially in late 2025, with further quarter-to-quarter uplifts expected into the first half of 2026 as AI-driven inventory demand outpaces available supply. At the same time, selective extensions of legacy production lines by major suppliers through 2026 have created short-term arbitrage opportunities in certain module classes. For enterprise buyers and system integrators, these conflicting signals make timing, supplier choice, and contract terms the primary levers for margin protection and product roadmap fidelity.
Competitive landscape — concentration and strategic implications
The DDR ecosystem remains highly concentrated: the top three and top five suppliers together account for an outsized share of market capacity, leading to elevated market influence on pricing, product roadmaps, and capacity allocation. This concentration manifests both as an opportunity (predictable technology roadmaps, consolidated testing baselines) and a systemic risk (supply bottlenecks, prioritized allocation to higher-margin product lines).
-
Samsung Electronics (Suwon, South Korea) — A dominant producer with extended DDR4 production commitments through 2026 while aggressively ramping advanced DDR5 and higher-density modules. Strategic emphasis: balancing legacy demand with next-gen capacity investment. ( https://www.samsung.com/semiconductor)
-
SK hynix (Icheon, South Korea) — Major supplier prioritizing high-performance DDR5 portfolios for servers and AI workloads, with selective legacy production extensions. Strategic emphasis: serving hyperscale and AI-centric customers through product velocity.
-
Micron Technology (Boise, USA) — U.S.-based leader focusing on higher-margin enterprise and data center DDR5 SKUs and higher-density components; maintains competitive DDR5 output while targeting premium segments. ( https://www.micron.com)
-
CXMT (ChangXin Memory Technologies) (Hefei, China) — Emerging supplier advancing DDR5 capability and providing alternative sourcing options as market share evolves. Strategic emphasis: cost-competitive ramps at mature nodes. ( https://www.cxmt.com)
-
Nanya Technology (New Taipei City, Taiwan) — Pure-play DRAM vendor adapting to reduced legacy output by larger players; benefits from specific niches where top-tier suppliers retract capacity. Strategic emphasis: focused node optimization. ( https://www.nanya.com)
-
Winbond Electronics (Taichung, Taiwan) — Specialty memory manufacturer serving embedded and niche DRAM needs; offers differentiated roadmap options for verticals with unique requirements. ( https://www.winbond.com)
Report highlights — the practical modules inside the full study
PW Consulting’s full DDR RAM Market Research report is structured to be operational from day one. Key deliverables include:
-
A transparent market sizing and forecasting model covering 2020–2032 with scenario analysis and sensitivity to capacity shifts.
-
Price-model simulations that translate wafer allocation scenarios into contract price projections across time horizons.
-
Supplier capability maps and capacity timelines, showing strategic moves and investment windows for the leading producers and credible challengers.
-
A technology and standards tracker that distills the business consequences of recent JEDEC updates and standards like DDR5 and LPDDR6 for design cycles and validation.
-
Actionable procurement playbooks and negotiation frameworks (including contract design, make/buy triggers, and inventory strategies) tailored for OEMs, cloud providers, and hyperscalers.
-
Regulatory and geopolitical risk matrices, with mitigations for critical minerals policy, export-control impacts, and supplier concentration.
NOTE: this preview deliberately omits the proprietary segmentation tables, region-by-region breakdowns, and application-level revenue splits that appear in the full report. Those core datasets and model files are a central deliverable for subscribers and are accessible on the report webpage.
Strategic implications and recommended moves for 2026
-
For buyers and OEMs: Treat memory procurement as a multi-year strategic function. Move beyond quarterly spot cycles: secure multi-year supply agreements with price- and allocation-linked mechanisms, accelerate design validation for emerging standards, and operationalize substitute-path testing to manage supply shocks.
-
For cloud and data center operators: Reassess memory mix on a workload basis. For latency- and bandwidth-sensitive AI workloads prioritize validated high-density DDR and HBM supplier commitments while staggering purchases to smooth capex and opex impacts.
-
For suppliers and foundries: Align capacity investments to differentiated product tiers where margin and long-term demand visibility are strongest. Consider selective partnerships and wafer-sourcing arrangements to de-risk sanction- or export-control-driven capital constraints.
-
For investors and M&A teams: Focus on bolt-on acquisitions that enable node migration, packaging capability, or alternate sourcing in under-served geographies. Evaluate counterparty exposure to policy risks and concentration effects in target valuations.
-
For policy-makers and procurement strategists: Account for processed minerals policy shifts and equipment export controls when modeling national supply resilience. Targeted incentives for downstream processing and secure materials sourcing will materially affect national-level memory resilience.
How to operationalize the research in your 2026 planning cycle
Practical steps to translate insight into action:
-
1) Prioritize SKU-level validation for next-gen modules tied to product roadmaps and cost-to-serve analysis.
-
2) Lock strategic allocations with tier-one suppliers where product differentiation matters and use indexed contracts elsewhere.
-
3) Build short-cycle hedging strategies that combine limited spot purchases, buffer inventory, and flexible component substitution playbooks.
-
4) Engage cross-functional war rooms (procurement, engineering, legal) to review export-control and mineral-policy scenarios that could affect manufacturing inputs.
-
5) Deploy supplier diversification plans that include credible regional alternatives and design-for-supply flexibility.
Next steps and access to the full intelligence
PW Consulting’s full DDR RAM Market Research report offers the complete dataset, forecast scenarios, supplier scorecards, and procurement templates referenced in this preview. The report is designed as a decision-ready tool for 2026 planning cycles; it combines empirical market modeling (2020–2025 base, 2026–2032 forecast) with playbooks you can operationalize within procurement, product, and corporate strategy functions.
To preserve the strategic value of the proprietary segmentation and pricing matrices, we have intentionally withheld the full tables and certain granular splits from this public preview. Organizations seeking the underlying models, executable templates, and bespoke advisory support can access the full report and contact PW Consulting’s advisory teams via the report web page.
PW Consulting remains committed to delivering market intelligence that translates into concrete actions. In a market defined by rapid technology evolution, concentrated supply, and renewed geopolitical complexity, this research is a strategic asset for any organization that depends on predictable, cost-effective access to DDR memory through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ddr Ram Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com