

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Uterotonic Agent Market at USD 1,138.3 Million in 2025, Poised to Reach USD 1,733.17 Million by 2032 at a 6.19% CAGR — Asia Pacific and Oxytocin Lead the Surge

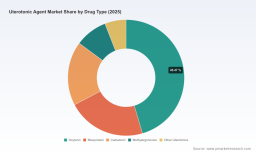
Uterotonic Agent Market — 2026 Strategic Outlook: Essential Intelligence for Decision-Makers
PW Consulting today releases a strategic briefing drawn from our full Uterotonic Agent Market report (base year 2025). As health systems, donors, manufacturers and investors prepare capital allocation and procurement strategies for 2026, this briefing synthesizes the structural trends and competitive dynamics that will determine who wins in the next phase of growth — and why. The global market for uterotonic agents expanded from a modest base in 2020 to approximately USD 1,138.3 Million in 2025, and we model continued expansion at a compound annual growth rate of 6.19% through the 2026–2032 forecast window, with the market reaching roughly USD 1.73 billion by 2032. This trajectory creates both near-term operational imperatives and multi-year strategic opportunities.
Uterotonic Agent Market
Why this market matters in 2026
-
Maternal health remains a global policy priority. International guidance and funding commitments are reorienting demand toward quality-assured uterotonics as countries seek measurable reductions in postpartum hemorrhage (PPH) mortality.
Uterotonic Agent Market -
Technological and formulation innovations — most notably heat-stable alternatives to cold-chain-dependent products — are redrawing procurement calculus in low-resource settings. These innovations are creating differentiated value propositions that go beyond unit price.
Uterotonic Agent Market -
Supply-side consolidation and the presence of both multinational innovators and a diverse base of generic and regional producers mean that procurement strategies must balance cost, quality assurance, supply resilience and local manufacturing objectives.
Market trajectory: what the numbers imply for strategy
The historical trend (2020–2025) demonstrates resilient growth driven by policy uptake, programmatic campaigns, and gradual expansion of access in lower‑resource geographies. Our forecast to 2032 assumes continued policy alignment with WHO guidance, incremental replacement of substandard products, and wider adoption of heat-stable formulations where cold‑chain reliability is limited. For corporate and procurement leaders, the key takeaway is that demand growth is steady and predictable at a mid-single-digit CAGR — sufficient to support targeted capacity investments and differentiated product launches, but not so rapid as to obscure the importance of cost discipline and differentiated service models.
Demand drivers and structural dynamics
-
Policy and clinical guidance: WHO guidance continues to designate injectable oxytocin as the primary uterotonic for PPH prevention where quality can be ensured, while heat‑stable carbetocin and misoprostol remain critical alternatives in contexts with compromised cold chains or limited clinical capacity. These clinical recommendations are shaping national essential medicines lists and procurement preferences.
-
Cold‑chain realities: Standard oxytocin formulations typically require 2–8°C storage, creating quality degradation risks in tropical climates. In settings where refrigeration is unreliable, procurement agencies increasingly weigh the total cost of ownership and clinical reliability when selecting products.
-
Quality and procurement behavior: Procurement decisions in many markets have emphasized upfront price, which has in some cases led to circulation of substandard products. Recent initiatives to strengthen quality assurance and supplier qualification are altering tenders and creating a pricing premium for WHO‑prequalified and otherwise quality‑assured suppliers.
Supply-side considerations and recent developments
-
Prequalification and supplier lists: Recent regulatory and procurement milestones — including WHO prequalification decisions and public-quality supplier lists published by independent organizations — are increasing transparency and altering buyer-supplier interactions. These shifts matter for manufacturers seeking access to public tenders and for financiers evaluating investment risk.
-
Formulation-led differentiation: Heat‑stable carbetocin, and other formulations that reduce dependence on cold chains, are reshaping tender specifications and procurement strategies in target countries. Licensing agreements and technology transfers are enabling broader production and distribution footprints for these differentiated products.
-
Local manufacturing and regional players: An emerging cohort of local and regional manufacturers — some WHO‑prequalified — is improving supply security in several markets. Decision-makers should assess the trade-offs between local sourcing objectives and supplier capability/quality.
Competitive landscape: strategic implications for incumbents and challengers
The competitive field spans multinational originators with proprietary or heat‑stable formulations, large generic pharmaceutical players with global reach, and focused regional manufacturers supplying public health programs. Market concentration is moderate: the top three players account for approximately 41.8% of total market revenue, while the top five control around 57.45%. These metrics indicate room for both scale-driven incumbents and well-positioned smaller players to capture value through specialization, cost leadership or quality differentiation.
-
Innovator strategy (e.g., developers of heat‑stable formulations): Innovators have leverage where product characteristics (stability, dosing convenience) materially reduce logistical costs and clinical risk. Strategic priorities include managing IP and licensing arrangements to expand public-sector access while protecting commercial returns in higher-margin markets.
-
Large generics and contract manufacturers: These players compete on scale, existing supply relationships with procurement agencies, and price. Their opportunity lies in investing selectively in quality upgrades, WHO prequalification, and supply‑chain transparency to move beyond lowest‑price bids.
-
Regional manufacturers and NGOs: Local producers can offer advantages in lead times, localization and policy alignment. Partnerships with donors or technical agencies to secure demand and co-invest in quality improvements can be decisive.
Recent industry actions underscore these dynamics: high‑visibility licensing initiatives to expand access to heat‑stable products, public lists of quality‑assured suppliers that reshape tender eligibility, and continued WHO prequalification activity that changes the supplier landscape. These events accelerate a shift from price-first procurement toward multi-criteria sourcing where quality, stability and supply resilience are explicit decision levers.
What the PW Consulting report delivers (practical, actionable content)
-
Forward-looking demand model (2026–2032) with scenario variations aligned to policy adoption rates, formulation uptake, and funding trajectories — designed for integration into procurement and investment decision tools.
-
Supplier scorecards and risk heatmaps incorporating quality assurance status, prequalification indicators, manufacturing footprint, cold‑chain requirements and commercial positioning (note: detailed supplier-level scores and regional splits are available in the full report).
-
Commercial playbooks for innovators, generics and contract manufacturers covering pricing strategy, licensing options, tender design, and partnership models to accelerate access in public markets while preserving commercial viability.
-
Operational checklists for procurement agencies and donors: sample RFP clauses, quality assurance KPIs, cold‑chain cost modeling templates and a supplier on‑boarding roadmap to mitigate the risk of substandard products.
-
M&A and investment screening framework that highlights capacity gaps, regulatory hurdles and value-creation levers for investors considering consolidation or vertical integration in the uterotonic supply chain.
Strategic recommendations for 2026 decision-makers
-
For manufacturers (innovators and generics): Prioritize WHO prequalification or equivalent quality credentials early in market-entry plans. Where feasible, pursue licensing or partnerships to expand access to heat‑stable formulations — this is both a public‑health imperative and a route to differentiated tender success.
-
For procurement agencies and donors: Move procurement evaluation beyond unit price to include total cost of ownership, potency risk, and cold‑chain limitations. Implement pre-tender supplier qualification checks and incorporate conditional procurement volumes to incentivize quality upgrades.
-
For local/regional producers: Leverage proximity advantages by aggregating demand with regional buyers or through pooled procurement mechanisms, while investing in quality management systems to meet international buyers’ expectations.
-
For investors and private equity: Focus on assets that can scale WHO‑prequalified production or that enable conversion of heat‑sensitive manufacturing lines. Consider bolt-on acquisitions that add prequalified SKUs or extend regional regulatory reach.
Why PW Consulting’s intelligence matters now
Decisions made in 2026 will shape national procurement pipelines, capital allocation and supplier ecosystems for years. The mid-single-digit CAGR and predictable growth path provide a planning window for capital investments, regulatory filings and partnership negotiations — but only if those actions are guided by nuanced understanding of quality risk, cold‑chain constraints and evolving procurement standards. Our full report provides the granular, actionable analytics required to operationalize these strategies, including detailed regional demand breakdowns, supplier scorecards, and an executable procurement playbook.
To access the full dataset, segment-level modeling, supplier assessments and the commercial playbooks referenced here, please visit the PW Consulting report page for the Uterotonic Agent Market. The full report is designed to equip executives and procurement leaders to act decisively in 2026: optimizing portfolios, securing quality supply, and aligning commercial models with global health priorities.
For detailed analysis of this topic, please visit the official page: Uterotonic Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com