

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: SMD Common Mode Chokes Market to Expand at 6.5% CAGR, Reaching USD 1,320.89 Million by 2032

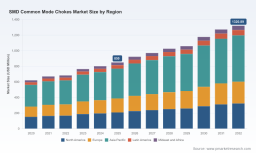
Smd Common Mode Chokes Market — Strategic Outlook for 2026: Actionable Insights from PW Consulting
As enterprises prepare procurement, product development, and go-to-market plans for 2026, PW Consulting’s latest Smd Common Mode Chokes Market report (base year 2025; forecast 2026–2032) delivers the sector-level context and decision-grade intelligence leaders need. The global market, which expanded from roughly USD 620 million in 2020 to USD 850 million in 2025, is projected to continue growing at a compound annual growth rate of 6.5% through 2032, reaching an estimated USD 1.32 billion by the end of the forecast window. These headline dynamics mask a rich set of trade-offs and operational risks—our research unpacks what they mean for procurement, design, and M&A strategies in 2026 without exposing the granular subsegment tables reserved for report subscribers.
Smd Common Mode Chokes Market
What the report delivers — practical, transaction-ready analysis
- Market sizing and scenario forecasts (2020–2032) with upside/downside sensitivity cases anchored to demand shocks in EVs, renewables, and telecom infrastructure.
- Segment playbooks for product teams: how to prioritize choke topologies, current ratings, and footprint trade-offs for power-line vs. signal-line use cases.
- Supplier scorecards and buyer’s guide: procurement KPIs, quality benchmarks (including AEC-Q200 and IEC/EN compliance expectations), and qualification checklists for Tier-1 and regional sources.
- Supply chain stress-testing: lead-time models for cores and copper, inventory optimization templates, and contracting strategies to mitigate raw-material volatility.
- Competitive dynamics and M&A heatmaps: concentrated areas of scale, niche innovation pockets, and consolidation scenarios for 2026–2028.
- Commercial negotiation levers: pricing index drivers, cost-to-serve breakdowns, and escalation clauses tailored to ferrite and copper input cycles.
Why 2026 is a pivotal planning year
Several structural forces converge in 2026 to change how companies must approach SMD common mode choke supply and design. Demand from power-dense applications—automotive electronics, high-efficiency power conversion in telecoms and data centers, and next-generation consumer products—continues to push requirements toward higher current ratings, tighter thermal envelopes, and stricter EMC performance. At the same time, material and logistics realities are evolving: ferrite and specialized nanocrystalline cores remain fundamental inputs, and their production and lead times have become a critical planning variable.
Smd Common Mode Chokes Market
Our analysis shows suppliers and buyers operating in a market that is neither fully fragmented nor highly concentrated: a mid-level concentration presents both opportunities to partner with scale players and openings to gain leverage via specialized suppliers. This structure amplifies the value of precise supplier selection and design convergence in 2026.
Smd Common Mode Chokes Market
Supply chain dynamics that should drive your 2026 playbook
- Core materials and pricing volatility — Ferrite cores and copper wire continue to be the dominant cost drivers. Price moves tied to broader base-metal cycles and demand from electrification projects materially affect BOM costs within weeks or months, not years.
- Lead-time risk for advanced cores — Nanocrystalline core lead times are typically 8–12 weeks under normal conditions and can extend to 16–22 weeks during constrained periods. This reality requires procurement plans that incorporate buffer inventory, long-lead purchase orders, or dual-sourcing strategies.
- Standards and compliance — Common mode components are being designed to meet rigorous EMC and power-application standards (e.g., IEC/EN common-mode requirements). Early engagement between systems engineers and suppliers reduces late-stage redesigns and compliance-cost overruns.
- Geographic manufacturing concentration — Major manufacturing capability remains rooted in Asia-Pacific hubs, with implications for lead-time, freight, and geopolitical risk. Nearshoring or local stocking strategies are becoming more common among OEMs targeting automotive and industrial markets.
Competitive landscape — what the major players mean for buyers
Across the market, incumbents differentiate on current capability (high-current surface-mount solutions), automotive qualification, proprietary core geometries, and integrated protection features. Several strategic observations for 2026:
- Leaders with high-current portfolios are shaping design-in cycles for power electronics: suppliers that can certify reflow-capable, high-current SMD chokes for industrial and telecom power lines hold strong negotiating positions for design wins.
- Automotive-focused suppliers that maintain AEC-Q200 qualifications and dedicated traceability processes tend to command longer, stickier relationships with vehicle OEMs and tier-one system integrators.
- Emerging launches from leading vendors demonstrate product push toward higher current ratings and specialized core shapes optimized for DC/DC and power-line applications. Recent product introductions by major manufacturers confirm this directional shift and put pressure on competitors to match thermal and current density performance.
- Mid-sized and niche suppliers remain important for custom form factors, specialized frequency responses, and rapid prototyping services—vital for firms seeking differentiation without committing to large supplier change costs.
PW Consulting’s competitive profiles include deep technical and commercial dossiers on the sector’s prominent suppliers, assessing technology roadmaps, capacity, quality systems, and customer concentration. We also quantify market concentration: the top three suppliers account for a meaningful share of the market, while top five control just over half—this split creates both bargaining room for buyers and strategic opportunities for suppliers looking to scale through partnerships or bolt-on acquisitions.
Recent product moves and their implications
- New high-current SMD chokes introduced by multiple vendors in 2025 signal escalating competition around current density and thermal performance. These launches accelerate the need for OEMs to reassess legacy component choices and re-evaluate qualification roadmaps.
- Product introductions aimed at telecom and industrial applications indicate that suppliers are targeting segments with longer product lifecycles and higher qualification barriers—a structural hedge against short-cycle consumer demand volatility.
Actionable strategies for 2026
Based on our scenario modeling and supplier intelligence, PW Consulting recommends a five-point strategic playbook for companies making decisions in 2026:
- Design-for-supply resilience: prioritize topologies and form factors with multiple qualified sources. Where a unique core or winding approach is required, secure design partnerships or multiple second-source agreements early in the calendar year.
- Lock-in long-lead components: for programs with multi-year production plans, negotiate staged capacity reservations or take-or-pay arrangements for cores during Q2–Q3 2026 to avoid extended lead-time windows.
- Embed EMC earlier in the product lifecycle: integrate choke selection into system-level EMI/EMC validation rather than treating it as an end-of-line fix—this reduces costly late-stage rework and accelerates time-to-market.
- Supplier segmentation and cost-to-serve optimization: classify suppliers by technology risk, capacity flexibility, and geographic exposure. Apply differentiated procurement approaches—spot auctions for commoditized SKUs, strategic alliances for long-tail, high-complexity parts.
- M&A and partnership scouting: for component manufacturers and PE investors, target specialized choke makers with differentiated core tech or automotive-grade processes to capture consolidation-driven margin expansion.
Recommended timing and tactical calendar for 2026
- Q1: Finalize design-in specifications and initiate multi-source qualification for any high-current or automotive-grade chokes.
- Q2: Secure long-lead contracts for cores and schedule capacity reservations aligned with BOM ramp timelines.
- Q3: Complete EMC validation cycles and lock manufacturing SOPs; begin transition to mass production for priority programs.
- Q4: Reassess inventory levels, update hedging strategies against raw-material price moves, and plan supplier audits for the following year.
How PW Consulting’s report advances 2026 decision-making
Our market study translates market-level growth (6.5% CAGR through 2032) into concrete operational actions—prioritizing supplier qualification, procurement structuring, and product design choices that reduce time-to-market and cost volatility. The report’s proprietary supplier scorecards, risk matrices, and cost-model templates are built for rapid integration into procurement and engineering workflows.
In keeping with the “teaser” approach, this release intentionally highlights the strategic takeaways most relevant to 2026 planning while withholding granular subsegment tables and supplier-specific financial models. These detailed exhibits—regional and application splits, SKU-level pricing, and full vendor scorecards—are available in the full PW Consulting report and on our report landing page.
For leadership teams preparing budgets and supply commitments for 2026, the right combination of supplier diversification, contract design, and early EMC integration will materially reduce program risk and protect margins as the market grows. PW Consulting’s Smd Common Mode Chokes Market report is designed to be the operational roadmap behind those decisions.
To access the full report, including the detailed segment analyses, supplier scorecards, and downloadable models, please visit the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Smd Common Mode Chokes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com