

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Multi-Use Cleaner Market to Grow at a 4.61% CAGR in 2026–2032, 2025 Report Finds

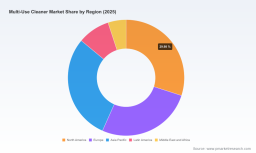
Multi Use Cleaner Market — Strategic Outlook 2026: Navigating Stability, Cost Volatility, and Consolidation
Executive summary
PW Consulting’s Multi Use Cleaner Market report (base year 2025) synthesizes five years of historical performance and a seven-year forecast horizon (2026–2032) to equip executives with decision-ready insights for 2026. The market reached approximately USD 8,800 Million in 2025 after a period of measured expansion and near-term volatility. Our forecast projects a compound annual growth rate (CAGR) of 4.61% across 2026–2032, taking the market toward a projected valuation in excess of USD 12 billion by 2032.
Multi Use Cleaner Market
This briefing highlights why these macro trajectories matter for product strategy, sourcing, channel investment and M&A planning in 2026 — while intentionally omitting the granular, proprietary segment tables contained in the full report to prompt direct engagement with our source material for deal-level decisions.
Multi Use Cleaner Market
Market trajectory and what it means for 2026 planning
-
Stability with pockets of cyclical pressure: Overall market growth over 2020–2025 shows resilient end-user demand despite episodic dips tied to macro shocks. For 2026, management teams should plan under a steady-growth base case while stress-testing for raw-material-driven margin compression and accelerated channel shift scenarios.
Multi Use Cleaner Market -
Mid-single-digit secular growth: A 4.61% CAGR across 2026–2032 implies predictable revenue expansion but heightened competition for margin. This environment favors companies that can extract operational efficiencies, innovate product and pack economics, and selectively pursue premiumization strategies in higher-margin niches.
-
Concentration and competitive dynamics: Market concentration metrics indicate the sector is moderately consolidated: top-three players account for a meaningful share while the top-five increase that concentration further. This structure enables leading incumbents to set innovation and distribution norms, but also leaves multiple mid-market opportunities for specialists and private-label players.
Strategic implications for 2026 decision-making
-
Portfolio prioritization: With steady overall growth, the near-term value driver will be margin expansion rather than raw topline capture. Companies should prioritize SKU rationalization, concentrate R&D on low-cost formulation upgrades and water-efficient concentrates, and accelerate roll-outs of differentiated claims (e.g., reduced VOCs, Safer Choice certification) where price elasticity supports premiumization.
-
Sourcing and procurement resilience: Raw material cost swings will be a decisive factor in 2026 budgeting. Linear Alkyl Benzene (LAB), an important surfactant feedstock, has shown meaningful price dispersion across regions in recent quarters — for example, benchmark observations ranged across key markets in 2025–2026 — underscoring the need for multi-sourced contracts, regional hedging strategies and co-located manufacturing where logistics economics justify investment.
-
Channel and go-to-market rebalancing: E-commerce continues to change purchase frequency and pack-size economics for residential buyers, while professional and institutional channels demand performance guarantees and bulk handling efficiencies. In 2026, companies should deploy differentiated channel playbooks, including digital-first promotions for household formats and performance-based contracts for commercial accounts.
-
M&A and partnership criteria: Given moderate market concentration, acquisitive moves should emphasize capability gaps — such as green formulations, concentrated dosing technology, or regional distribution — rather than chasing scale alone. Our report provides a prioritized acquisition filter tailored to margin accretion timelines and integration risk tolerances.
Operational playbook — what the report delivers
The full PW Consulting report translates market-level forecasts into actionable workstreams for 2026. Key deliverables include:
-
Revenue scenario models (base, upside, downside) calibrated to raw-material price paths and channel-shift assumptions.
-
SKU and pack optimization matrices that link cost-to-serve to pricing bands and recommended rationalizations.
-
Procurement playbooks: supplier segmentation, hedging approaches, and a factory siting decision tool informed by freight and input-cost sensitivities.
-
Commercial frameworks: margin-first assortment, promotional ROI ladders for digital vs brick-and-mortar, and institutional contracting templates.
-
M&A targeting engine and integration checklist focused on capability capture (formulations, dosing, green credentials) rather than pure volumetrics.
These modules are built for immediate operationalization: dashboards, templates and scenario models are included in the licensed deliverable so leaders can run “what-if” analyses tailored to their P&L cadence.
Competitive landscape — players to watch in 2026
The sector remains anchored by established multinational incumbents and specialist professional suppliers. Our competitive review synthesizes strategy, portfolio positioning and go-to-market capability for key firms, including:
-
The Procter & Gamble Company (Cincinnati, Ohio, USA) — strong consumer brands with scale R&D and retail channel leverage ( https://us.pg.com/).
-
The Clorox Company (Oakland, California, USA) — portfolio depth in disinfectants and institutional channels ( https://www.clorox.com/).
-
Reckitt Benckiser Group plc (Slough, United Kingdom) — multi-surface disinfectant leadership and strong institutional penetration ( https://www.reckitt.com/).
-
Henkel AG & Co. KGaA (Düsseldorf, Germany) and Unilever PLC (London, United Kingdom) — diversified household-care portfolios with distribution breadth ( https://www.henkel.com/, https://www.unilever.com/).
-
S.C. Johnson & Son, Inc., Ecolab Inc., Diversey, LLC, 3M Company — a mix of consumer and professional capabilities with distinct routes-to-market ( https://www.scjohnson.com/, https://www.ecolab.com/, https://diversey.com/, https://www.3m.com/).
-
Regional and industrial specialists such as Zep Inc., Spartan Chemical, Betco Corporation and Church & Dwight — targeted portfolios and distribution relationships that make them attractive acquisition or partnership candidates ( https://www.zep.com/, https://www.spartanchemical.com/, https://www.betco.com/, https://churchdwight.com/).
Our competitive maps provide relative positioning on capabilities such as formulation innovation, private-label servicing, dosing systems and sustainability credentials — information critical for negotiating partnerships and benchmarking product roadmaps. Detailed market shares and segment-level competitive tables are reserved for the report’s subscriber pages.
Cost, regulation and sustainability dynamics
-
Input-cost vigilance: LAB price observations across major sourcing geographies in 2025–2026 highlight non-uniform cost pressure that affects global sourcing choices. Procurement strategies should therefore incorporate regional price differentials, long-term supplier agreements and formulation flexibility to substitute or reduce surfactant intensity where performance permits.
-
Regulatory and eco-innovation imperatives: Programs such as the U.S. EPA’s Safer Choice certification are shaping buyer preferences and procurement requirements, particularly among institutional customers. In 2026, certification status will increasingly be a gate in RFPs for public and private sector contracts; product development plans must anticipate documentation and testing timelines.
-
Net-zero and circularity pressures: Packaging recyclability, concentrate formats and refill systems are high-leverage areas for differentiation. The report quantifies likely ROI horizons for switching to concentrated refills and polymer-reduced packs under different consumer adoption curves.
How senior leaders should use this report in 2026
-
CEOs and corporate strategists: use the macro scenarios and concentration analysis to set portfolio and M&A targets for the year, and to stress-test the company’s exposure to raw-material inflation.
-
CFOs and procurement heads: deploy procurement playbooks and the cost-sensitivity dashboards to reprice contracts, renegotiate supplier terms and evaluate capex for regional manufacturing adjustments.
-
CMOs and category heads: operationalize the SKU/pack optimization matrices and channel-specific growth levers to improve margin per distribution point.
-
Business development and corporate development teams: use the M&A filter and competitive scorecards to prioritize targets and accelerate due diligence.
Methodology note and next steps
Our analysis integrates five-year historical sales trajectories, bottom-up channel models and supplier-cost monitoring to produce a probabilistic forecast for 2026–2032. The public briefing intentionally highlights high-level numbers (market size, CAGR and concentration metrics) while withholding the proprietary segment valuation tables, regional and application splits and pricing matrices. These granular outputs — including interactive models and buyer-switching elasticity assumptions — are available through the full PW Consulting report subscription.
To convert insight into action in 2026, PW Consulting recommends a two-week rapid diagnostic (sourcing stress test + SKU profitability sweep) followed by a 90-day implementation roadmap addressing procurement, pack economics and targeted channel pilots. Contact PW Consulting for access to the full report package, models, and tailored workshops designed to accelerate decision-making and capture the margin opportunities the market presents in 2026.
For detailed analysis of this topic, please visit the official page: Multi Use Cleaner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com