

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wafer Purge Systems Market Poised to Grow at a 9.5% CAGR Over 2026–2032

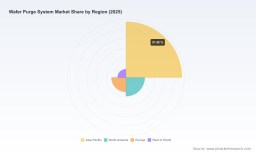
Wafer Purge Systems 2026: Strategic Intelligence for High-Stakes Decisions
As semiconductor manufacturers navigate an era defined by extreme miniaturization, supply-chain scrutiny, and sustainability mandates, wafer purge systems have shifted from a niche operational expense to a strategic enabler of yield, uptime, and cost predictability. PW Consulting’s latest Wafer Purge System Market Research (base year 2025) synthesizes historical performance (2020–2025) with forward-looking scenario analysis for 2026–2032 to equip executives with the evidence and playbooks needed for decisive action in 2026.
Wafer Purge System Market Research
Market pulse: macro trajectory you can count on
The wafer purge systems market has shown resilient expansion across the past half decade and is set to accelerate through the next planning cycle. Our topline modeling pegs the market at roughly USD 845.5 Million in 2025, rising to an expected USD 924.7 Million in 2026. Over the 2026–2032 forecast window, the sector is projected to grow at a compound annual growth rate (CAGR) of approximately 9.5%—a pace driven by capacity additions at advanced nodes, broader adoption of inert environment strategies across 200–300mm toolsets, and retrofitting programs in existing fabs.
Wafer Purge System Market Research
Two structural facts make this growth commercially meaningful for 2026 budget cycles: first, the technology’s direct impact on yield and process stability; second, accelerating investments in retrofits as integrators and fabs seek lower-capex paths to contamination control. These forces combine to make wafer purge systems an actionable lever for both OPEX and CAPEX optimization.
Wafer Purge System Market Research
Why the 2026 decision window matters
- Yield preservation at scale: Nitrogen-purged storage and handling demonstrably reduce oxide formation and particle-related defects, an outcome that scales geometrically with wafer throughput and the criticality of advanced process nodes.
- Retrofit as a high-return pathway: Many fabs can unlock near-term margin improvements via targeted retrofits of FOUPs, stockers, and load ports—options that postpone expensive tool replacements and shorten ROI timelines.
- Operational efficiency through smarter gas control: New flow-control innovations materially reduce purge gas consumption, lowering both utility and logistics costs while improving environmental footprint metrics that matter to stakeholders and regulators.
Key dynamics shaping supplier and buyer strategies
- Technology-in-fabric innovations: Low-energy, piezo-based flow-control valves and precision nozzle mechanisms are reshaping the cost equation. Field data and vendor disclosures indicate that well-designed flow control can cut nitrogen consumption substantially—transforming an ongoing operating cost into a controllable variable with measurable payback.
- Raw material and component pressure: Stainless steel and electronic sensor components constitute a substantial portion of manufacturing costs for purge equipment. Rising metal and sensor prices have increased OEM input costs, compressing margins for suppliers that cannot rapidly pass through inflation or achieve volumetric scale efficiencies.
- Regulatory complexity and certification risk: Compliance with industry standards such as SEMI S2, alongside export-control regimes that affect front-end equipment, means procurement and compliance teams must bake certification risk into sourcing and deployment timelines—especially for cross-border supply to geographies under tightened export restrictions.
- Concentration and competitive dynamics: The market demonstrates material concentration among a handful of specialist suppliers. This creates both leverage for leading OEMs to set technical direction and an opportunity for nimble challengers to win retrofit business through aggressive product differentiation and service models.
Competitive landscape: what the leading suppliers are doing
Our qualitative benchmarking surfaces three strategic supplier archetypes: platform integrators who embed purge capabilities into automated material-handling systems; niche specialists focused on FOUP/SMIF pod purging and desiccation cabinets; and component innovators that supply high-efficiency valves, nozzles, and sensors. Prominent players exemplify these archetypes:
- Fabmatics (Germany) — A retrofit-first specialist with a strong global installed base, Fabmatics emphasizes continuous inert gas purging across storage and overhead buffers. Its field-proven deployments and modular retrofit approach make it a default partner for fabs targeting rapid contamination-control upgrades without disruptive capital projects.
- Murata Machinery (Muratec) (Japan) — A systems integrator that combines thin purge units, mass flow control, and proprietary nozzle efficiency claims. Muratec’s approach is attractive to fabs seeking tight integration between stockers and existing AMHS frameworks.
- Rorze Corporation (Japan) — Known for N2 purge stockers and low-flow nozzle mechanisms, Rorze focuses on minimizing gas consumption while maintaining low oxygen and humidity for FOUP handling—relevant for customers prioritizing OPEX containment.
- Palbam Class (Israel) and Santa Phoenix Technology (Taiwan) — These vendors specialize in cabinet-style N2 solutions and smart charging for FOUPs, addressing storage-centric contamination control in both greenfield and brownfield contexts.
- Daifuku, Sinfonia Technology, Kostek, and others — Large AMHS suppliers and module vendors are increasingly bundling purge options into stockers and load ports, expanding the incumbents’ ability to capture systems-level value.
Recent product and trade-show activity underscores the pace of commercial evolution: smart purge systems and low-energy flow-control modules were showcased at major industry events in 2025, while leading suppliers continue to document multi-thousand-unit field installations—evidence that adoption is moving from pilot to scale in several leading fabs.
Operational and commercial implications for 2026 planning
- For fabs (IDM and foundry): Prioritize an audit of wafer handling and interim storage processes to quantify contamination risk and potential yield uplift from purge upgrades. Include retrofit scenarios in 2026 CAPEX plans and quantify OPEX savings from reduced cleaning cycles and nitrogen usage under both current and improved flow-control technologies.
- For OEMs and integrators: Accelerate product roadmaps that integrate smart flow control, modular retrofits, and telemetry for O2/H2O monitoring. Build certified, SEMI-compliant product stacks and plan for export-control compliance workflows to reduce friction in cross-border deployments.
- For investors and supply-chain managers: Target suppliers that demonstrate: (a) clear installed-base traction, (b) roadmaps for gas-efficiency gains, and (c) resilience to raw-material inflation (through design choices, sourcing diversity, or pricing power). The market’s concentration indicates that successful consolidation or strategic partnerships can rapidly change competitive dynamics.
What our report delivers (practical, executable intelligence)
PW Consulting’s full report goes beyond market sizing. It provides:
- Scenario-driven financial models for retrofit vs. greenfield deployment across multiple node and throughput assumptions;
- Vendor-level technology scorecards covering nozzle architecture, flow-control strategy, monitoring and communications, retrofit complexity, and compliance posture;
- Procurement playbooks that align spec’ing, certification checkpoints (including SEMI S2 requirements), and export-control screening to accelerate procurement cycles while mitigating regulatory risk;
- Supplier negotiation levers and TCO calculators that convert technical improvements—such as reduced nitrogen consumption from next-generation valves—into cash-flow impacts and payback windows;
- Operational case studies showing how N2-purged stockers deliver quantifiable reductions in cleaning frequency and yield-enhancing outcomes, enabling prioritized investment decisions.
In this announcement we intentionally withhold granular regional and application split figures and certain proprietary vendor-level supply metrics: the full dataset, models, and vendor scorecards are available exclusively in the report and via our interactive web portal for subscribers.
Action agenda for senior leaders—next 90 days
- Conduct an internal contamination-risk and yield-sensitivity workshop involving fab process engineers, AMHS owners, and procurement to identify “low-hanging fruit” for purge retrofits.
- Engage two suppliers—one retrofit specialist and one AMHS integrator—for proof-of-concept validations that emphasize gas-efficiency and certification readiness.
- Update CAPEX/OPEX models to reflect potential gas savings from advanced flow-control and the current raw-material inflation environment; stress-test procurement scenarios against export-control constraints.
- Commission a supplier audit focused on manufacturing cost structure, especially material and sensor exposure, to inform contract and price-risk mitigation strategies.
Final perspective
As semiconductor roadmaps push for ever-tighter control of contamination and process environments, wafer purge systems will play an increasingly strategic role. The market’s robust CAGR and the maturity of retrofit options create a rare convergence: near-term operational upside paired with long-term strategic leverage. For executives preparing 2026 budgets, the question is not whether to invest in purge capability, but how to prioritize among retrofit, retrofit-plus, and systems-integrated pathways to maximize yield, control OPEX, and manage regulatory complexity.
PW Consulting’s full Wafer Purge System Market Research report supplies the quantitative models, vendor scorecards, and executable procurement playbooks that operationalize these choices. To access the complete analysis, scenarios, and interactive tools that underpin the conclusions summarized here, please visit our report page or contact your PW Consulting account lead for an executive briefing.
For detailed analysis of this topic, please visit the official page: Wafer Purge System Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com