

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fumed & Precipitated Silica Market Reaches USD 7.61 Billion in 2025, Poised for Continued Growth

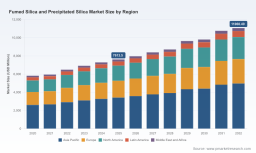
Fumed Silica and Precipitated Silica: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive Preview
PW Consulting’s new Fumed Silica and Precipitated Silica Market study (base year 2025, forecast 2026–2032) equips executives, investors and supply‑chain leaders with the quantitative and decision‑grade intelligence needed to make high‑stakes choices in 2026. The report maps an industry that has grown steadily through 2020–2025 and that we now model to continue expanding at a mid‑single‑digit compound annual growth rate (CAGR) of 5.48% through 2032. From an estimated global market size in 2025 to our 2032 outlook, the analysis quantifies demand trajectories, stress‑tests supply scenarios, and isolates the commercial levers that will determine winners and laggards in the decade to come.
Fumed Silica And Precipitated Silica Market
Why this market matters in 2026
-
Cross‑industry criticality: Both fumed and precipitated silica remain foundational additives across tires, elastomers, paints & coatings, adhesives, personal care and selected food applications. Decisions made in 2026 on capacity, feedsourcing and product differentiation will set cost and margin curves for the remainder of the forecast window.
Fumed Silica And Precipitated Silica Market -
Structural change in demand drivers: Electrification, sustainability mandates for “green tires,” and higher‑value electronics and specialty applications are shifting demand composition toward specific silica grades and performance attributes. These shifts amplify the value of targeted R&D and premiumization strategies more than volume plays alone.
Fumed Silica And Precipitated Silica Market -
Supply‑chain vulnerability and policy: Recent tariff interventions and regional policy moves have made security of supply and near‑term capacity a boardroom topic. Firms that move to secure feedstocks, localize production or lock strategic off‑take arrangements in 2026 will gain decisive negotiation leverage.
What PW Consulting’s analysis delivers
Our report is purpose‑built for strategy teams. It balances granularity and confidentiality: illustrative models and scenario outputs show how unit economics change under alternative feedstock, energy and tariff assumptions, while proprietary regional and application splits are reserved for the full report. Key deliverables include:
-
Demand forecasting to 2032 with scenario modelling (base, downside, upside) that links macro adoption trends (e.g., tire electrification, specialty silicones) to silica grade demand.
-
Supply and capacity mapping that identifies short‑to‑medium term bottlenecks, greenfield opportunities and strategic brownfield expansions needed to close forecast gaps.
-
Raw material sensitivity analysis that quantifies EBITDA exposure to movements in sodium silicate and silicon‑tetrachloride feedstocks, energy costs and freight dynamics.
-
Regulatory and product stewardship risk matrix focusing on CLP/STOT considerations and operational controls that reduce liability and ensure market access.
-
Commercial playbook for producers and downstream users outlining pricing, contracting and product innovation tactics to capture margin in a tightening market.
Market dynamics shaping strategic choices
The market’s headline growth masks nuanced forces that will determine strategic outcomes in 2026 and beyond:
-
Feedstock volatility and substitutability: Precipitated silica production is closely tied to sodium silicate supply economics and energy for furnace processes, while fumed silica depends on silicon‑based precursors and flame hydrolysis routes. Our sensitivity models show that feedstock inflation and supply disruption profiles differ across routes — making a firm’s technology choice a material financial decision.
-
Regulatory and labeling pressures: Synthetic amorphous silicas maintain distinct regulatory treatment relative to crystalline forms, but increased attention to chronic inhalation and supply chain labeling (e.g., STOT RE 1 considerations) requires enhanced product stewardship programs and can alter usage patterns for certain grades.
-
Trade policy shocks: Tariff and trade policy shifts in 2025 altered arbitrage flows and elevated the strategic premium on domestic or regionally proximate capacity. Firms with flexible logistics and diversified manufacturing footprints are better positioned to capture spot opportunities and defend margins.
-
Sustainability and circular feedstocks: Market demand for lower carbon intensity and circular raw materials is already influencing capital allocation. Investments that deliver demonstrable lifecycle improvements are commanding commercial premiums in tire and specialty segments.
Competitive landscape — who to watch
The industry exhibits a concentrated core with numerous regional specialists. PW Consulting’s competitor matrix in the full report maps capabilities, channel strengths and recent strategic moves; below are concise strategic profiles and implications for 2026 competition.
-
Evonik Industries AG (Essen, Germany) — Industry leader with integrated production and vertically aligned inputs. Evonik’s strategic focus on both flame hydrolysis and precipitation technologies and its investment program to expand precipitated silica capacity underscores a dual track: defend high‑value specialty applications while capturing sustainability‑focused tire demand.
-
Cabot Corporation (Boston, MA, USA) — A major fumed silica producer with global footprints and targeted joint ventures. Cabot’s push to expand brownfield capacity in India signals an emphasis on serving high‑growth domestic end markets and on securing cost‑competitive supply for specialty applications.
-
Wacker Chemie AG (Munich, Germany) — Known for high‑purity fumed grades used in electronics and silicones. Wacker’s technology orientation and site diversification provide a defensive moat in performance segments where quality commands premium pricing.
-
Tokuyama Corporation (Tokyo, Japan) and OCI Company Ltd. (Seoul, South Korea) — Both are important for high‑purity and hydrophobic fumed grades, respectively, supplying semiconductor, silicone and high‑value industrial applications where consistency and specialty support matter.
-
QEMETICA (Warsaw, Poland) — After acquiring PPG’s precipitated silica business, QEMETICA’s enlarged footprint positions it as a consolidator in European and North American precipitated markets, with particular focus on tires, batteries and specialty fillers.
-
Solvay, W.R. Grace, Tata Chemicals and a set of regional producers in India and China — These players collectively shape price dynamics in industrial and rubber segments and are increasingly active on sustainability, specialty HDS grades and low‑carbon initiatives.
Recent market events that matter for 2026 decisions
-
Evonik’s capacity expansion (announced October 2024) to raise precipitated silica output underlines OEMs’ and tire makers’ demand for sustainable inputs — a lead indicator for procurement teams that future RFPs will demand circularity credentials.
-
QEMETICA’s acquisition of PPG’s precipitated silica business (completed November 2024) reconfigured the competitive map in Europe and North America, compressing supplier choices for certain specialized grades and creating new scale economies.
-
Capacity additions in Asia announced by major fumed silica players in 2026 signal both response to domestic industrial growth and strategic hedging against trade policy volatility.
Implications by strategic role
-
Producers: Prioritize portfolio differentiation toward high‑value grades, accelerate pilot projects for circular feedstocks, and secure flexible logistics to mitigate policy risk. Use scenario planning to justify brownfield versus greenfield capital allocation in 2026.
-
Downstream manufacturers (tires, coatings, adhesives): Embed multi‑sourcing and long‑term offtake clauses into procurement strategies; quantify performance trade‑offs for lower‑carbon silica substitutions; and co‑invest in joint R&D to accelerate qualification timelines.
-
Investors and M&A teams: Look for targets that offer technology lock‑in, access to circular feedstocks, or regional scale advantages created by recent consolidation. Valuation multiples will increasingly reflect sustainability credentials and secure supply access.
-
Policy and risk teams: Update compliance playbooks for class‑specific labeling and supply chain disclosure. Advance worker safety and upstream supplier auditing to protect market access and reduce STOT‑related risk exposure.
What the full PW Consulting report contains (practical tools)
The published study provides an executive toolkit for action in 2026, including:
-
Interactive supply‑demand dashboards and downloadable datasets (CSV) for custom scenario runs.
-
Contractual playbooks and sample clause language to manage price pass‑through, force majeure and sustainability covenants.
-
Detailed capex and timeline modelling for brownfield and greenfield projects across major producing technologies.
-
Competitor scorecards with capability matrices, recent deal activity and M&A readiness indicators.
-
Regulatory checklists and product stewardship templates mapped to likely CLP/STOT outcomes.
How to use these insights in 2026
Leaders should treat 2026 as a year to translate strategic intent into binding actions: secure tiered supply agreements that hedge tariff and feedstock risk, prioritize qualification pipelines for higher‑value silica grades, and align capex with scenarios where sustainability requisites become de‑facto market entry criteria. Tactical moves—such as selective brownfield expansions, JV formations, or acquisition of specialty portfolios—will compound advantage across the forecast horizon.
Closing invitation
This preview outlines the strategic thesis and decision levers. For boards and commercial teams preparing 2026 budgets and three‑to‑five‑year roadmaps, the full PW Consulting report contains the granular regional and application‑level intelligence, proprietary unit‑cost models and scorecards required to execute with confidence. Access to the full dataset and consulting‑grade scenario workbooks is available through the PW Consulting report page — contact our market team to arrange a briefing and download the executive tools that translate insight into immediate action.
— PW Consulting, Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: Fumed Silica And Precipitated Silica Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com