

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High-Speed Optical Transceiver Market to Expand at 15.48% CAGR, Reaching USD 55,030 Million by 2032

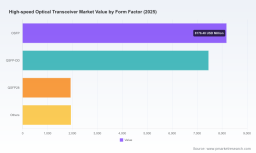
High Speed Optical Transceiver Market — Strategic Intelligence for 2026 Decision-Making
Executive summary
As hyperscale, cloud and telecom architectures accelerate adoption of 400G and above optics, the high speed optical transceiver market is entering a phase of rapid expansion and structural shift. Our latest PW Consulting market study shows the market scaled from roughly USD 7.2 billion in 2020 to USD 19.5 billion in 2025 and is projected to continue expanding to an estimated USD 55.0 billion by 2032 — representing a compound annual growth rate of 15.48% across the 2026–2032 forecast window. This trajectory is driven by the confluence of silicon photonics maturation, new pluggable module MSAs, and surging bandwidth demand from AI/ML workloads and 5G transport.
High Speed Optical Transceiver Market
For executives planning capex, product roadmaps, supply chain commitments and M&A activity in 2026, the practical insights contained in this report translate directly into executable choices: where to invest in internal R&D, which supplier relationships to prioritize, how to structure procurement to mitigate supply and regulatory risk, and how to position product portfolios for interoperability and cost leadership.
High Speed Optical Transceiver Market
Why this study matters for 2026
-
Market momentum is no longer incremental — it is multi-year and multi-architecture. The size and growth dynamics demand strategic reorientation of sourcing, product development and channel strategy.
High Speed Optical Transceiver Market -
Standards and form-factor progress (OSFP-XD, CEI-112G class specifications, IEEE 802.3df) create windows of opportunity but also first-mover traps; timing product launches to standards adoption will materially affect adoption curves and margins.
-
Regulatory and raw material shocks are endogenous risks: export controls and wafer supply constraints alter supplier viability and pricing power. Companies that embed these macro risks into their 2026 planning will preserve margin and delivery commitments.
Report scope — what you will find inside
This report is built as an operational toolkit for 2026 decision cycles. It combines quantitative market modeling with actionable market-entry and defense playbooks. Key deliverables include:
-
Top-down market sizing and a seven-year forecast with scenario analysis (base, upside, downside) that maps demand to capacity and technology adoption timelines.
-
Supplier and ecosystem mapping: capability heatmaps for silicon photonics, EML/VCSEL lasers, DSPs, and module integrators; vendor profiles with go-to-market evidence and interoperability certifications.
-
Competitive positioning matrices and valuation proxies to guide M&A and investment prioritization.
-
Procurement playbooks: multi-source contracting templates, hedging strategies for key components, and recommended inventory buffers under different lead-time scenarios.
-
Product roadmaps aligned to standards adoption and hyperscaler validation cycles, including performance, power, and thermal trade-off frameworks for pluggable optics.
-
Risk registers for export control, raw material price volatility, certification lag and concentration risk, with mitigation options ranked by cost and implementation time.
Competitive landscape — who’s setting the pace
The current landscape is a mix of legacy component specialists, vertically integrated network OEMs, and aggressive Chinese and Japanese module houses. Market concentration is meaningful: the top three vendors account for nearly half of market supply, and the top five capture well over sixty percent — a dynamic that favors scale and integration while leaving room for focused challengers.
-
Coherent Corp (USA) — A leader in high-speed transceivers across 400G, 800G and beyond, Coherent’s investments in silicon photonics and integrated DSPs position it strongly for short-reach DCI and data center interconnects. Recent product introductions underscore their push into silicon-photonics-enabled 800G modules.
-
Innolight Technology (China) — Innolight has moved rapidly to support hyperscalers with QSFP-DD and OSFP offerings, and in late 2025 launched a 1.6T OSFP-XD transceiver targeting AI data centers. Their momentum illustrates how focused engineering and supply relationships can accelerate form-factor transitions.
-
Cisco Systems (USA) — As a buyer and integrator, Cisco’s optics roadmap is closely tied to switch ASIC development. Certification achievements with next-generation switch families reduce adoption friction for partners and customers and help set de facto interoperability baselines.
-
II‑VI / Coherent (USA) — With a strong foothold in silicon photonics and laser integration, the combined II‑VI/Coherent capability establishes a strategic axis for modules up to 1.6T targeted at AI/ML workloads.
-
Lumentum Holdings (USA) — Focused on coherent and PAM4 optics, Lumentum’s ramping of pluggable ZR/ZR+ shipments to hyperscalers signals the emergence of pluggable coherent optics in DCI and metro use cases.
-
Asia and Japan-based module houses (Accelink, Hisense Broadband, Fujitsu Optical Components, Sumitomo Electric, Eoptolink) — These players combine manufacturing cost advantages, regional customer relationships and MSA-compliant product strategies to serve telecom and cloud customers in their home markets and beyond.
-
Source Photonics; Maxlinear — Cost- and DSP-focused vendors that compete on price-to-performance and integration depth; attractive targets for hyperscalers seeking a wider vendor base.
Recent developments that matter
-
OSFP-XD MSA publication and a wave of 1.6T product announcements indicate a practical roadmap to 200G‑per‑lane architectures; early entrants will shape form‑factor economics.
-
Standards work such as completed CEI-112G specifications and IEEE 802.3df for 800G/1.6T Ethernet reduce interoperability risk but raise the technical bar for component suppliers.
-
Hyperscaler certification milestones (e.g., Tomahawk interoperability) and volume shipments of pluggable coherent optics are shortening time-to-adoption for new module types.
Market dynamics and structural risks
Decision-makers in 2026 must reconcile rapid demand growth with several non-linear risks:
-
Component supply and cost pressure: Laser and VCSEL supply constraints have already translated into price increases; firms need active supplier development and multi-sourcing to avoid margin erosion.
-
Regulatory fragmentation: Export controls on high-bandwidth optical components shift where manufacturing and R&D investments can be safely located without losing market access.
-
Standards timing: Early compliance brings interoperability advantages but also requires significant engineering investment; late entry risks being locked out of reference architectures.
-
Consolidation pressure: High fixed costs for photonics integration and DSP development favor consolidation; strategic alliances or targeted M&A can accelerate capability assembly.
Practical 2026 playbook — actions by stakeholder
-
Cloud & Hyperscalers: Adopt a phased mix of proprietary and open-standard optics to retain tight TCO control; fund silicon-photonics co-development where volume justifies. Negotiate long-term supply agreements with price-escrow provisions for key laser supplies.
-
Network OEMs & Vendors: Prioritize modular architectures enabling rapid swaps across 400G–1.6T line cards. Invest selectively in silicon photonics and DSP IP; pursue strategic contracts with MSA groups to influence form‑factor directions.
-
Component suppliers: Focus on yield acceleration and vertically integrated assembly to protect margins. Certify early with leading switch ASIC vendors to shorten design cycles for customers.
-
Private equity & strategic investors: Target players with differentiated IP in photonics packaging, DSP algorithms or cost-efficient manufacturing; plan for consolidation plays as market concentration remains elevated.
Why PW Consulting’s report is different
This study balances rigorous, audit‑grade market modeling with hands-on execution tools. The quantitative forecast is complemented by supplier heatmaps, interoperability timelines, procurement templates and scenario‑tested strategic options — all designed to be directly usable in board-level capital allocation and procurement approvals in 2026.
Next steps — how to use this intelligence
-
Download the executive dataset to overlay our demand curves on your demand planning and inventory models.
-
Use the supplier heatmap to short-list 3–5 partners for qualification and create a parallel sourcing track for critical laser and DSP sub-systems.
-
Engage with our advisory team for a tailored three‑month go-to-market sprint: vendor selection, contract negotiation templates and a certification roadmap aligned to your product launches.
Access full findings
This release is a strategic preview designed to highlight the report’s decision-grade insights while preserving the detailed subsegment analytics that inform procurement, pricing and M&A decisions. The full report contains the granular regional, data-rate and form-factor breakouts, vendor-level revenue benchmarking, and downloadable models that underpin the scenarios summarized here.
For procurement managers, product leads and investors who must make binding choices in 2026, our analysis converts market movement into a prioritized set of actions — reducing execution risk while exposing high-conviction opportunities. Contact PW Consulting to obtain the full report, the Excel forecast model, and bespoke advisory support to operationalize these findings.
For detailed analysis of this topic, please visit the official page: High Speed Optical Transceiver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com