

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting forecasts Breast Cancer Biomarkers Market to reach USD 8,332.42 Million by 2032

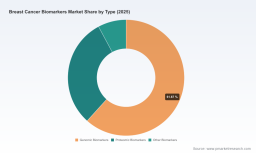
Breast Cancer Biomarkers Market Outlook 2026: Strategic Imperatives for Life Sciences Leaders
As therapeutic innovation, precision diagnostics and regulatory evolution converge, breast cancer biomarkers are rapidly reshaping clinical pathways and commercial opportunity maps. PW Consulting's latest market study—anchored on a 2025 base year with a historical view from 2020–2025 and a forward-looking forecast to 2032—translates that convergence into a practical playbook for executives making high‑stakes decisions in 2026. The global market has expanded meaningfully over the past half‑decade and, under base-case assumptions, continues to grow at a robust compound annual growth rate (CAGR) of 9.2% through our forecast horizon. These are macro dynamics you need to calibrate against product roadmaps, partnership negotiations and reimbursement strategies this year.
Breast Cancer Biomarkers Market
Why this report matters now
-
Timing: 2026 is a pivotal inflection point for biomarker-driven breast cancer care. Recent regulatory clearances and trial readouts have accelerated clinical adoption of companion diagnostics, while payer policies are tightening evidentiary requirements for routine reimbursement. Our study maps those shifts into actionable scenarios for vendors, payers and hospital systems.
Breast Cancer Biomarkers Market -
Decision focus: Boardrooms and business development teams must now choose among four interdependent paths—organic product development, focused M&A, strategic partnerships (co‑development/companion diagnostics), and rapid deployment of decentralized testing capabilities. The report quantifies the strategic tradeoffs and time-to-value for each path.
Breast Cancer Biomarkers Market -
Risk management: Supply chain disruptions, patent expiries and regulatory labeling complexity are no longer theoretical. The report supplies contingency frameworks and supplier diversification checklists to protect testing volumes and service continuity.
Market trajectory at a glance
Between 2020 and 2025 the market has moved from early‑stage expansion to mainstream clinical adoption. Our modeled market size shows a clear inflection, with accelerating revenues underpinned by genomic profiling, proteomic methods, and liquid biopsy adoption. By 2025 the sector has entered the multi‑billion dollar range and, with a mid‑single to high‑single digit CAGR, is projected to more than double for many portfolios by the end of the forecast period. For commercial leaders this means that near‑term investments in clinical evidence and payer engagement are likely to deliver compounded returns across multiple product categories.
What’s in the full report (practical, executable content)
-
Market architecture and scenarios: Three demand scenarios (conservative, base and aggressive) tied to regulatory outcomes, reimbursement roll‑outs and clinical guideline updates—each with revenue and volume implications by assay type and testing channel.
-
Go‑to‑market blueprints: Rollout playbooks for companion diagnostics, lab-developed tests (LDTs) and decentralized point‑of‑care platforms, including launch sequencing, pricing corridors and channel economics.
-
Regulatory and reimbursement playbooks: Step‑by‑step checklists for FDA co‑development pathways, PMA/510(k) strategies where applicable, and payer engagement templates calibrated to MolDX and other regionally specific coverage policies.
-
Clinical adoption heatmaps: Adoption levers and friction points across oncology care settings, with prioritized evidence generation plans to accelerate guideline inclusion.
-
Supply chain resiliency plans: Tactical advice on sourcing critical antibodies, FISH probes and assay reagents—plus alternative sourcing strategies and inventory hedging models.
-
Competitive benchmarking: Detailed technology profiles, commercial footprint maps and a battle‑card suite for the leading diagnostics and genomics players that are shaping the market today.
-
Portfolio optimization and M&A targets: Screening criteria and valuation drivers for tuck‑ins and platform deals, along with a shortlist of capability adjacencies likely to yield rapid synergies.
Clinical and regulatory dynamics shaping 2026 decisions
Several structural forces are re‑calibrating the value equation for breast cancer biomarkers. The FDA’s co‑development model continues to be the de facto pathway for companion diagnostics, raising the bar for analytical and clinical validation but providing clearer commercialization routes for companies that invest early in co‑development with therapeutics teams. At the same time, payers in key markets have begun to codify coverage for select genomic assays under defined clinical scenarios—an important demand signal that changes how health economic dossiers should be built.
Operationally, supply chain constraints—particularly shortages of critical antibodies and FISH probes—have compressed testing capacity in several regions. This is a strategic lever: manufacturers that secure diversified reagent supply or develop alternative assay chemistries can protect throughput and capture incremental market share without price competition. Meanwhile, the expiration of legacy genetic patents has broadened the testing base for hereditary risk assessment, intensifying competition but also expanding the addressable market for risk stratification services.
Competitive landscape: who matters and why
The market is competitive but not monopolized—top players maintain strong clinical and channel advantages, while a tier of agile innovators is leveraging speed, automation and new sample modalities to penetrate labs and clinics.
-
Roche Diagnostics: A dominant clinical diagnostics franchise with deep IHC/FISH expertise and an expanding RxDx portfolio. Their continued investment in assay standardization and automation keeps them central in hospital and reference lab protocols.
-
Agendia: A specialist genomic profiling company focused on risk stratification and molecular subtyping. Strategic partnerships that integrate genomic outputs into AI‑driven clinical platforms are extending their clinical utility beyond baseline prognostication.
-
Exact Sciences: Known for established recurrence‑score testing, Exact has broadened indications through recent regulatory milestones, strengthening its position in early‑stage treatment decision tools.
-
Hologic & Danaher (Leica Biosystems): These platform players supply high‑throughput automation and companion diagnostic assays, enabling scale in centralized labs and influencing procurement decisions across health systems.
-
Abbott & Qiagen: Providers of targeted assays and companion kits that link molecular findings to targeted therapies. Qiagen’s recent companion diagnostic clearances underscore the commercial importance of co‑development with pharmaceutical partners.
-
Myriad Genetics: A household name in hereditary risk testing; their broad portfolio continues to anchor genetic counseling pathways and population screening discussions.
-
BioCartis & Guardant Health: Representing the faster diagnostics and liquid biopsy segments, respectively, these companies are pushing the boundaries of turnaround time, sample accessibility and ctDNA‑guided therapy selection—areas that are attracting significant clinical interest.
Our concentration analysis indicates that a modest number of firms hold a meaningful share of clinical testing volumes and platform placements. That market concentration creates both barriers and opportunities: incumbents control access to many clinical touchpoints, but innovators can outmaneuver them through differentiated evidence, lower cost‑of‑testing or superior integration into treatment decision workflows.
Recent developments you cannot ignore
-
Expanded regulatory approvals and trial readouts have materially altered the commercial calculus for companion diagnostics and genomic assays—shifts that our forecast and scenario modules explicitly incorporate.
-
Clinical trial innovations using ctDNA to guide therapy selection have produced promising progression‑free survival signals, strengthening the case for liquid biopsy deployment in metastatic settings.
-
Partnerships that pair genomic assays with AI and clinical decision support platforms are changing how results are interpreted and actioned at the point of care.
How to use the report in 2026: five executive actions
-
Prioritize co‑development deals for companion diagnostics tied to late‑stage therapeutic programs. Our ROI sensitivity models show co‑development can compress time‑to‑reimbursement and improve market access odds.
-
Build a reimbursement evidence accelerator: target prospective studies and payer‑focused health economic analyses in the first 12–18 months post‑launch to shorten time to favorable coverage.
-
Hedge supply risk by securing multi‑sourced reagent contracts and qualifying alternative chemistries; factor continuity clauses into supplier agreements.
-
Assess decentralization: for organizations with strong logistics and digital support, deploying rapid on‑platform testing in community settings can capture underserved volumes and command premium pricing.
-
Use our M&A screening matrix to identify tuck‑ins that supply complementary clinical evidence, automation capability or market access expertise—targets that typically unlock the fastest synergies.
Access to the data and the next step
This article intentionally highlights the analytical depth and strategic orientation of PW Consulting’s Breast Cancer Biomarkers Market report while withholding the granular regional and application‑level tables that underpin our forecasting engine. The full report includes proprietary segmentation matrices, downloadable financial models, and a competitor battle‑card set with actionable intelligence. For companies allocating 2026 budgets to diagnostics development, payer engagement, or inorganic growth, the dataset and scenario tools in the full report are designed to support board‑level decisions and internal investment committees.
To request the complete executive suite—market model, supplier risk tool, reimbursement playbook and M&A shortlist—visit PW Consulting’s report page or contact our strategic advisory team. Our analysts are available to run custom scenario variants and to brief leadership teams on how the findings map to your specific portfolio priorities in 2026.
For detailed analysis of this topic, please visit the official page: Breast Cancer Biomarkers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com