

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Semi Direct Drive Wind Turbine Generator System Market Set for 12.02% CAGR — Valued at USD 18,562.15 Million in 2025, Forecast to Reach USD 41,034.98 Million by 2032

Semi Direct Drive Wind Turbine Generator System Market — Strategic Preview for 2026 Decisions
PW Consulting today publishes a strategic preview of our forthcoming market report on the Semi Direct Drive Wind Turbine Generator System (WTGS) market. This briefing distills the report’s core implications for executive decision-making in 2026 — highlighting the commercial runway, competitive inflection points, supply-chain sensitivities, and the practical intelligence executives will need to convert opportunity into market share. The full report (base year 2025; historical window 2020–2025; forecast 2026–2032) contains the granular segment and scenario analysis that underpins the recommendations summarized here.
Semi Direct Drive Wind Turbine Generator System Market
Executive summary: why semi direct drive matters to 2026 strategy
Semi direct drive drivetrains are emerging as the pragmatic middle path for large-megawatt offshore projects: they balance reliability, efficiency, and cost in ways that are reshaping procurement choices for developers and OEMs. Our market sizing shows a sustained, above-market CAGR across the forecast window — driven by accelerating offshore deployment, OEM product maturation, and a concerted materials and integration push across the value chain. Specifically, the market expanded materially through 2020–2025 and is projected to continue robust growth through 2032 at an annualized rate of approximately 12.02%.
Semi Direct Drive Wind Turbine Generator System Market
For 2026 planners, that trajectory implies two immediate realities: (1) demand growth will continue to create supplier leverage and multi-year contract opportunities; (2) competitive differentiation will increasingly rest on platform-level integration, rare-earth sourcing strategies, and demonstrable reliability at scale. Our report converts these macro signals into actionable options for developers, OEMs, component suppliers, and investors.
Semi Direct Drive Wind Turbine Generator System Market
Market trajectory and implications
-
Observed market expansion (2020–2025): The semi direct drive market recorded significant expansion during the historical window as several OEMs moved from prototyping to serialization of medium-speed platforms. This phase established techno-commercial proof points that reduce perceived technology risk for contractors and financiers.
-
Forecast momentum (2026–2032): Under our base-case modeling, total market value grows strongly through 2032 — roughly doubling from the mid‑2020s level by the end of the forecast horizon. That pace reflects continued offshore project awards, rising turbine ratings, and broader adoption of medium-speed architectures for large-capacity units.
-
Concentration and partnership dynamics: The market exhibits a relatively high level of supplier concentration among leading OEMs and integrators. The top three suppliers account for a majority share of installed semi direct drive capacity, while the top five extend a commanding position. For buyers this concentration means fewer, deeper sourcing relationships; for challengers it sets a high bar for scale, certification, and service capability.
Strategic levers for 2026 — where to act now
-
Secure mid-term supply of key magnetic materials: Permanent magnet machines remain central to semi direct drive designs. Our material-cost sensitivity analysis shows that marginal changes in NdFeB pricing and alloy composition can meaningfully affect LCOE and capex phasing for large projects. Firms should move from spot purchasing to offtake-linked hedges or long-term supplier partnerships to stabilize economics for 2026–2028 projects.
-
Prioritize integrated drivetrain validation: Buyers and OEMs should require supplier roadmaps and validation plans that demonstrate integrated shaft‑gear‑generator reliability at scale. Pilot performance data and accelerated-life testing will be decision gates for contracting and warranty structuring in 2026.
-
Design modular service strategies: Semi direct drive platforms deliver efficiency gains when paired with targeted maintenance regimes and digital condition monitoring. Service-capability investment — especially for sea‑fast access, modular component swaps, and remote diagnostics — will become a differentiator in client tender evaluations.
-
Evaluate strategic M&A and JV routes to capture scale: Given the market’s concentration, alliances and targeted acquisitions of gearbox, magnet, or integration specialists can accelerate market entry and reduce time-to-first-contract. 2026 is likely to see elevated deal activity around technology bolt-ons and regional assembly capacity.
What the PW Consulting report provides (practical contents)
Our full report is built for practitioners who must make near-term capital and sourcing decisions. It contains:
-
Detailed market sizing and three-tier scenario forecasts (base, upside, downside) for 2026–2032 with sensitivity analysis tied to commodity pricing, policy timelines, and project pipeline realization rates.
-
End-to-end commercial due diligence templates for developers and investors, including procurement scorecards, warranty negotiation playbooks, and CAPEX/OPEX modeling slabs tailored to semi direct drive platforms.
-
Supply‑chain heat maps identifying capacity bottlenecks, lead‑time drivers, and qualifying criteria for critical sub‑suppliers (magnets, medium‑speed gearboxes, integrated shaft assemblies).
-
Operational readiness checklists for serial production and offshore commissioning, and an OEM comparison framework that scores candidates on technical maturity, integration depth, and service footprint.
-
Commercial scenarios and procurement strategies that map to different developer profiles (merchant vs contracted), financing structures, and regional permitting timelines.
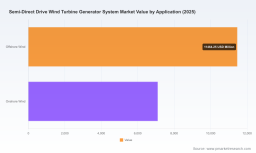
Note: this preview intentionally omits granular segment-by-region and by-application split values. The full dataset and interactive dashboards are available through the report portal for verified subscribers.
Competitive landscape: core players and recent moves
The competitive field is anchored by a handful of vertically integrated OEMs that have moved semi direct drive from concept to commercial scale. Key actors featured in our competitive dossiers include:
-
Ming Yang Smart Energy Group — A global frontrunner in semi direct drive offshore platforms, with a product family centered on medium‑speed compact drive (MCD) architectures and typhoon‑rated designs. Recent product introductions and floating‑platform concepts indicate a push to secure both fixed‑foundation and floating project pipelines.
-
Dongfang Electric Corporation (DEC) — Advancing large-capacity semi direct drive units with high integration across shaft, gearbox, and generator systems. DEC’s prototype installations of very-large machines signal an aggressive entry into the upper-megawatt offshore segment.
-
Goldwind Science & Technology — While historically focused on PMDD and other drivetrains, Goldwind’s incremental inclusion of medium‑speed platforms highlights a strategic diversification to meet different project and grid-adaptation requirements.
-
Yinchuan Weili Transmission Technology — A specialist supplier of integrated medium‑speed speed‑increaser components that bridge impellers and permanent magnet generators. Component-level innovation like Weili’s reduces platform mass and simplifies logistics for serial production.
Recent industry developments reinforce the competitive dynamics summarized above. In 2025 and into early 2026, OEMs unveiled next‑generation medium‑speed MCD portfolios, and several manufacturers commissioned prototype installations of very-large-rated offshore turbines using fully integrated semi direct drive drivetrains. These events accelerate buyer scrutiny on demonstrable serial performance and service readiness.
Supply chain, materials, and risk factors
-
Material intensity and rare‑earth exposure: Semi direct drive permanent magnet designs typically require less rare‑earth magnet material than full direct‑drive equivalents — a structural advantage that reduces material cost sensitivity and logistics friction. However, mid‑grade NdFeB magnets remain a material input to monitor: in 2025 market indications placed mid‑grade sintered magnet pricing in the low triple‑digit USD per kilogram range, and price volatility can materially alter near‑term project economics.
-
Manufacturing and integration risk: Tight tolerances in medium‑speed gearboxes and the need for integrated shaft‑gear‑generator assemblies mean manufacturing scale and quality control are differentiators. Expect OEMs with vertically integrated supply chains or validated tier‑1 partners to command preferable procurement terms in 2026 tenders.
-
Regulatory and permitting tailwinds: Policy support for offshore deployment and national content rules in key markets will shape where projects are developed and which OEMs can compete effectively. Our scenario work models these regulatory levers to quantify pipeline realization risk by commissioning window.
How executives should use this intelligence in 2026
-
Developers: Use the report’s procurement scorecards to structure multi‑stage contracts that de‑risk first-of-kind units while preserving upside on serial procurement discounts.
-
OEMs: Prioritize investments in integration testing and service networks. The market rewards demonstrable uptime performance and lifecycle cost transparency.
-
Component suppliers and investors: Target partnerships that close capability gaps for scale production — magnets, medium‑speed gearboxes, and modular assembly capacity are immediate focus areas.
Next steps and obtaining the full report
This preview captures the strategic contours that matter for 2026 decisions: strong market growth, supplier concentration, material and integration sensitivities, and a narrow set of competitive frontrunners. The full PW Consulting report provides the underlying quantitative models, the proprietary supplier benchmarking, and downloadable commercial templates you will need to operationalize these insights. For access to the complete dataset, interactive dashboards, and tailored briefings for your executive team, please visit our report page.
PW Consulting’s Semi Direct Drive WTGS Market report is designed to be both diagnostic and prescriptive. If your 2026 plans hinge on drivetrain technology selection, supply agreements, or scale-up strategies, this is the intelligence set that converts hypothesis into executable strategy.
For detailed analysis of this topic, please visit the official page: Semi Direct Drive Wind Turbine Generator System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com