

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
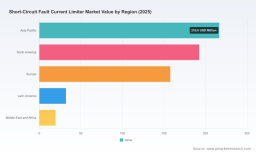
PW Consulting Forecast: Short Circuit Fault Current Limiter Market to Rise from USD 618.5 Million in 2025 to USD 1,073.8 Million by 2032 at an 8.21% CAGR — Asia Pacific Leads with USD 216.6 Million

Short Circuit Fault Current Limiter Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As utilities, independent power producers, industrial energy managers and system integrators position for an accelerating energy transition, short circuit fault current limiters (FCLs) have moved from niche protection hardware to a strategic grid-stability lever. PW Consulting’s new Short Circuit Fault Current Limiter Market report — built on a 2020–2025 historical base and a 2026–2032 forecast — quantifies that shift and translates it into decision-ready guidance for corporate leaders in 2026.
Short Circuit Fault Current Limiter Market
Headline numbers that matter
Our base-year analysis shows the global FCL market reached approximately USD 618.5 Million in 2025. Under the market dynamics modeled in this study, the sector is expected to expand at a compound annual growth rate (CAGR) of 8.21% through 2032, reaching roughly USD 1.07 Billion by the end of the forecast horizon. These macro figures underpin the report’s core argument: FCLs are becoming an essential asset class for preserving legacy switchgear value and enabling higher penetrations of inverter-based resources.
Short Circuit Fault Current Limiter Market
Why this matters for 2026 decisions
-
Operational continuity and compliance: As grid codes evolve to demand tighter fault-ride-through performance and grid-forming behaviour from distributed resources, FCLs offer a practical pathway to both meeting compliance and avoiding costly switchgear upgrades.
Short Circuit Fault Current Limiter Market -
Capital efficiency: For asset owners evaluating network reinforcement versus selective protection upgrades, the economics of FCL deployment transform when modeled across expected inverter penetration scenarios and equipment replacement cycles — a central modeling capability of our report.
-
Technology selection and timing: The market is technologically heterogeneous — from superconducting designs through solid-state and pyrotechnic/IS-limiter options — and timing a technology bet matters. Our analysis maps technology readiness to maturity risk, procurement lead-times, and total cost of ownership under multiple grid futures.
What’s inside the report — practical outputs for executives
PW Consulting’s report is designed as an operational playbook for 2026 decision cycles. It does not simply describe the market; it equips procurement, engineering, and strategy teams with actionable deliverables:
- Proprietary market-sizing model (2020–2032) with sensitivity levers for renewable penetration, UHV/HV investments and HTS supply-cost paths.
- Investment-grade vendor scorecards covering reliability, service footprint, product variants, and lifecycle economics.
- Technology comparator and use-case matrix that aligns FCL architectures (superconducting, solid-state, inductive/magnetic, IS/pyrotechnic) to customer risk profiles and commissioning timelines.
- Procurement playbooks and tender templates tuned to 2026 contracting environments, including SLAs, acceptance tests, and spares strategies.
- Scenarios and decision gates for R&D and partnership strategies — from pilot funding thresholds to M&A screening criteria.
- Supply-chain risk register with mitigation options for critical inputs (notably HTS tape and power-electronics semiconductors) and recommended inventory policies for brownfield/greenfield projects.
Competitive landscape — who to watch
The FCL market is characterized by a mix of large power-systems incumbents, specialized superconducting developers, and nimble, cost-focused challengers. Our concentration analysis indicates a moderately concentrated supplier base: the top three vendors account for over 40% of market presence, and the top five approach 60% — a structure that influences pricing dynamics, bid competition, and partnership opportunities.
-
ABB Ltd. (Switzerland) — A global systems integrator offering medium-voltage FCLs and portfolio solutions for compact indoor/outdoor integration. ABB’s strength lies in end-to-end delivery capabilities and established utility relationships, making it a frequent partner on large-scale distribution and industrial projects.
-
Siemens AG / Siemens Energy (Germany) — Offers network-grade FCL solutions and places emphasis on grid stability for high-voltage applications. Expect Siemens to pursue integrated grid-stability packages that bundle protection, controls and services.
-
Schneider Electric (France) — Focused on medium and low-voltage protection ecosystems, Schneider tends to compete on system compatibility, lifecycle services and industrial deployments where coordination with existing protection systems is imperative.
-
Eaton Corporation (Ireland) — Positions current-limiting devices as part of broader machine-building and electrical infrastructure protection strategies; attractive to OEMs seeking SCCR compliance and integrated solutions.
-
Nexans (France) — A notable industrial player in superconducting fault current limiter development, recently advancing rail-sector applications through strategic alliances; a technology leader to watch for specialist SFCL deployments.
-
LS Electric Co., Ltd. (South Korea) — Offers rapid-response FCL products tailored to networks where circuit breakers alone are insufficient; strong regional execution capabilities in Asia-Pacific markets.
-
G&W Electric (United States) — Focused on current-limiting protection for systems up to medium voltage class, G&W competes on durable field-proven hardware for distribution utilities.
-
GridON Ltd. (Israel) — A cost-competitive supplier with offerings optimized for grid operators, IPPs and industrial customers that require pragmatic, quick-to-deploy solutions.
-
American Superconductor Corporation (AMSC) (United States) — An HTS-wire developer advancing superconducting FCLs; its technology roadmap and supply capabilities are a key variable for SFCL adoption curves.
-
Rongxin Power Electronic Co., Ltd. (China) — Focused on power-electronic FCLs that address power quality and short-circuit management; its products align with market segments prioritizing rapid fault handling and compact footprints.
Recent industry developments shaping 2026 strategy
-
Technology validation accelerates adoption: High-voltage demonstrations that successfully couple superconducting FCLs with DC circuit-breaker systems have shown substantial limitation performance in HVDC test contexts. These validations materially reduce technical risk for offshore renewables and HVDC link applications.
-
Targeted sector pilots: Strategic alliances targeting rail and transport sectors underline a move towards sector-specific FCL implementations, with the potential to create replicable templates for other critical infrastructure customers.
-
Regulatory momentum: Evolving grid codes — emphasizing grid-forming behavior, fast fault injection control and harmonic management — are raising the baseline requirement for passive and active fault management devices. This regulatory tailwind accelerates procurement cycles among regulated utilities.
-
Supply-side sensitivities: HTS conductor costs and availability remain a central determinant for SFCL cost trajectories. Designs that optimize conductor usage at LN2 operating temperatures and alternative cooling approaches are particularly consequential for unit economics.
Strategic recommendations for 2026
-
Start with targeted pilots, not broad rollouts: Prioritize pilot deployments in constrained circuits where FCLs can demonstrably defer asset replacement or enable new interconnects. Use pilots to validate integration with existing protection schemes and to collect real-world performance data for contracting negotiations.
-
Hedge critical input risk: For firms considering superconducting options, secure upstream positions or multi-supplier agreements for HTS tape and cryogenic services. For power-electronics-heavy options, qualify dual-sourcing for critical semiconductor modules.
-
Engage in standards and grid-code consultations: Influence technical requirements and interoperability expectations early. Vendors and buyers who participate in standards work can reduce non-recurring engineering costs and accelerate procurement acceptance criteria.
-
Design procurement for lifecycle economics: Tender evaluation should include failure-mode analysis, maintenance windows and end-of-life recycling — not just CAPEX. Our procurement playbook includes template performance clauses and service-benchmark KPIs tailored for 2026 market conditions.
-
Consider strategic partnerships over bolt-on M&A: Given the market’s moderate concentration and the deep engineering specialization required, joint development or JV structures with superconducting or power-electronics specialists often outperform full acquisition in near-term value creation.
Where PW Consulting adds unique value
PW Consulting’s report combines a detailed, audited market model with supplier intelligence and executable templates for procurement and project delivery. Critically, the work is structured to support 2026 board-level decisions: it converts technical performance parameters into balance-sheet impacts and provides clear decision gates for pilots, scale-up and investment. To preserve competitive advantage for subscribers, detailed segment-level breakouts and vendor-specific price decks are only available within the full report package.
Next steps for executives
For energy leaders planning capital programs in 2026, the decision levers are clear: accelerate targeted validation projects, secure critical supply positions, and structure procurements around lifecycle performance. PW Consulting’s Short Circuit Fault Current Limiter Market report equips teams to make those choices with quantified scenarios and industry-proven contracting frameworks. To assess how these insights apply to your specific operating and regulatory footprint, contact PW Consulting for an executive briefing and tailored workshop.
For detailed analysis of this topic, please visit the official page: Short Circuit Fault Current Limiter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com