

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gamma Knife Radiosurgery Market Poised for Steady Expansion at a 5.76% CAGR Through 2032

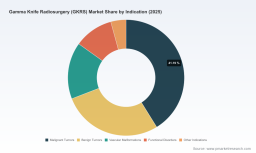
Gamma Knife Radiosurgery (GKRS) Market — Strategic Outlook for 2026
PW Consulting’s latest market research brief on Gamma Knife Radiosurgery (GKRS) presents a focused, decision-oriented assessment designed to inform executive strategy in 2026. Drawing on a six‑year historical series and a seven‑year forecast, the report synthesizes clinical, commercial, regulatory and capital‑investment dynamics that will shape vendor positioning, hospital purchasing, and investor returns in the coming cycle.
Gamma Knife Radiosurgery Gkrs Market Research
Executive snapshot
- The GKRS market is at a measured growth inflection: after recovering from near‑term variability, our modelling places the market at approximately USD 482.5 Million in the report base year (2025) and projects a steady expansion through the forecast window (2026–2032) at a compound annual growth rate of 5.76%.
- We observe a market structure dominated by a handful of specialized vendors and marked by high entry barriers — technical, regulatory and capital — that concentrate value in system sales, long‑term service contracts and consumables.
- Recent regulatory and clinical developments are re‑shaping the addressable use cases for GKRS, creating near‑term opportunity for product positioning and medium‑term implications for capital planning and reimbursement strategies.
Why this matters for 2026 decision‑makers
Hospital systems, equipment manufacturers, private equity investors and strategic buyers face a set of binary choices in 2026: accelerate adoption and expand program capacity, or prioritize multi‑purpose platforms that maximize utilization. GKRS is not just another capital purchase — it is a long‑horizon clinical program investment that touches clinical pathways, radiology and neurosurgery service lines, reimbursement negotiation and radioactive source lifecycle management. PW Consulting’s analysis translates these technical realities into actionable scenarios that CEOs, CFOs and strategy chiefs can use to size risk, model returns and prioritise capital allocation.
Gamma Knife Radiosurgery Gkrs Market Research
Market trajectory and growth drivers
- Macro growth is underpinned by three converging forces: expanding clinical indications (including functional applications), increasing case complexity that favors highly conformal intracranial platforms, and willingness among some hospital systems to pay higher technical charges for single‑fraction stereotactic radiosurgery.
- Our scenario modelling accounts for reimbursement variability, capital planning cycles, and regulatory headwinds related to radioactive source management. The resulting baseline forecast projects continued, moderate expansion to a materially larger market by the end of the forecast horizon — an outcome that supports new investment but requires disciplined execution on service and clinical adoption.
- Cost and revenue dynamics are asymmetric: procedure-level reimbursement can be significantly higher for GKRS relative to some linac‑based alternatives in select markets, which changes the economics of program build‑out even when system acquisition is capital‑intensive.
What’s in the PW Consulting GKRS report (practical, executable content)
The report is structured to be immediately useful for strategic planning and transaction diligence. Key deliverables include:
Gamma Knife Radiosurgery Gkrs Market Research
- Proprietary market model (2020–2032) in downloadable format: top‑line forecasts, scenario toggles for reimbursement and adoption, and sensitivity analysis for capex amortization and case mix. Note: this press release intentionally omits granular regional and indication splits; full models are available with the report.
- Buyer’s playbook for hospital systems: capital decision trees, recommended staffing and training roadmaps, and a reimbursement negotiation toolkit that maps clinical codes to realistic net revenue assumptions (including illustrative chargemaster data points drawn from U.S. hospital surveys).
- Vendor scorecards and procurement checklist: comparative evaluation criteria for system acquisition, service SLAs, consumables pricing, and radioactive source lifecycle obligations (installation, management, and decommissioning pathways).
- M&A and corporate strategy module: valuation frameworks for platform vendors and aftermarket specialists, integration risk matrices, and prioritized acquisition themes such as consumables, maintenance networks, and distributed treatment centers.
- Regulatory and safety compliance dossier: practical steps to prepare for cobalt‑60 source management, facility licensing implications, and scenario playbooks for decommissioning costs and timelines.
- Clinical adoption index and evidence roadmap: recommendations to accelerate case volumes through evidence generation, referral pathway alignment, and payer engagement strategies for broader indication coverage.
Competitive landscape — who matters and why
The GKRS supplier ecosystem is characterized by specialized device engineering, deep installed bases, and aftermarket revenue capture. PW Consulting highlights three vendor types that matter to supply dynamics in 2026:
- Elekta AB (Stockholm, Sweden): the primary commercial anchor in the space, provider of the Leksell Gamma Knife family across multiple hardware generations. Elekta’s breadth of clinical data, established service networks, and recent regulatory momentum — notably U.S. 510(k) clearance expanding indications to include drug‑resistant mesial temporal lobe epilepsy (MTLE) in adults (July 2025) — are strategically significant. That clearance exemplifies how regulatory expansion into functional indications can expand program utility and hospital willingness to invest, while also creating evidence and reimbursement pathways that other vendors will attempt to follow.
- Regional and alternative technology vendors (e.g., MASEP Medical Science & Technology Development Co. Ltd., China): developing rotary and alternative gamma solutions that compete on capital intensity and local service models. These suppliers matter most in markets where price, local support, and procurement incentives outweigh single‑vendor clinical legacy.
- Specialist challenger platforms (e.g., American Radiosurgery Inc., U.S.): producers of rotating gamma systems such as RGS Vertex360 that seek to differentiate on throughput, lifecycle economics, or unique clinical claims. Their strategic pressure is greatest where customers value flexibility, lower per‑case cost or an alternate risk profile around radioactive source management.
Dynamics and risk factors
- Reimbursement pressure vs. opportunity: procedure‑level technical charges for single‑fraction GKRS in some U.S. hospitals have been documented at levels materially higher than linac‑based SRS. That differential creates commercial opportunity but also invites payor scrutiny and contract renegotiation; hospitals must be ready with case‑level cost accounting and outcomes evidence when presenting claims to payors.
- Regulatory and operational complexity: GKRS systems that rely on cobalt‑60 require rigorous radiation safety protocols, licensing and long‑term source management plans — including planned decommissioning. These obligations represent both risk and a recurring revenue opportunity for vendors that can package turn‑key management and predictable total cost of ownership.
- Capital intensity and utilization risk: unlike multipurpose linac platforms, GKRS systems are dedicated intracranial tools. The decision to buy should be driven by programed volumes and referral capture strategies; otherwise utilization shortfalls materially degrade financial returns.
- Market concentration and competitive moats: value accrues not only in initial system sales but in consumables, head‑frame and mask accessories, long‑term maintenance, and training. Small vendor ecosystems amplify aftersales opportunity for market leaders but also create acquisition targets for private capital aiming to consolidate service networks and consumables supply chains.
Where the pockets of opportunity will be in 2026
- Functional indications and expanded clinical use: regulatory clearances and robust evidence will drive adoption beyond classical tumor indications; vendors and hospital programs that can demonstrate cost‑effective outcomes for functional disorders will unlock new case volumes.
- Aftermarket and service economics: predictable, recurring revenue from maintenance and consumables continues to represent a disproportionate share of lifetime value. For investors, platforms that control field service and supply logistics offer defensible margins.
- Adjacency M&A: targets that strengthen a vendor’s ability to offer bundled service (installation, source management, decommissioning) or expand consumables penetration are attractive in a concentrated market where install base expansion is incremental.
What PW Consulting recommends for 2026 planning
- For hospital systems: develop a 5‑year utilization plan before committing to acquisition; model alternative leasing and refurbishment scenarios and build a payer engagement dossier that aligns clinical protocol to reimbursement codes.
- For vendors: prioritize hybrid commercial models that combine system sales with compelling service agreements and consumables bundles; invest in clinical evidence programs for functional indications to capture emerging demand pockets.
- For investors and corporate development teams: focus due diligence on installed base visibility, field service KPIs, consumables gross margins, and regulatory exposure related to source lifecycle liabilities.
How to use the full PW Consulting report
This press release is a strategic preview. The full report contains the downloadable market model, granular segmentation, vendor scorecards, and executable playbooks that will enable teams to build capex requests, model M&A returns, and prioritize product development investments. To preserve the strategic value of the intelligence and to protect commercial sensitivity, we have deliberately withheld the granular regional and indication‑level breakdowns in this release. The full dataset, including scenario inputs and supplier benchmarking, is available to subscribers and purchasers via our market research portal.
Concluding perspective
The Gamma Knife radiosurgery market in 2026 sits at the intersection of clinical innovation and capital discipline. Measured growth (5.76% CAGR in our central scenario) justifies new investments — provided those investments are guided by realistic utilization plans, strong payer strategies, and careful management of regulatory obligations. PW Consulting’s GKRS research translates technical complexity into boardroom decisions: whether you are sizing a program, evaluating a vendor, or underwriting an acquisition, the difference between success and disappointment will be in the details — the operational levers, the reimbursement playbook, and the aftermarket economics that we quantify in the full report.
For access to the full dataset, models and actionable appendices, visit PW Consulting’s Gamma Knife Radiosurgery market report page or contact our research team to arrange briefing and data licensing.
For detailed analysis of this topic, please visit the official page: Gamma Knife Radiosurgery Gkrs Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com