

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Cross‑Domain E/E Architecture Market Poised to Grow at 16.55% CAGR Through 2032

Automotive Cross-Domain E/E Architecture Market — Strategic Imperatives for 2026 Decision‑Making
Executive summary
PW Consulting’s latest Automotive Cross Domain E/E Architecture Market report (base year 2025; forecast 2026–2032) synthesizes commercial, technical, regulatory and competitive intelligence into an operational playbook for senior executives. The market is on a sustained expansion path — growing from a sizeable mid‑single‑digit billion USD base in 2025 to a multi‑billion market by 2032 under a robust compound annual growth rate of approximately 16.55%. This trajectory creates both urgent risks and unique windows of opportunity for OEMs, Tier‑1 suppliers, and semiconductor and software providers as they plan 2026 investments and product roadmaps.
Automotive Cross Domain E E Architecture Market
Why 2026 matters: a strategic inflection for E/E architectures
Several converging forces make 2026 a pivotal year for cross‑domain E/E architecture decisions:
Automotive Cross Domain E E Architecture Market
- Regulatory acceleration: Global vehicle type approval regimes now require certified cybersecurity management (UNECE WP.29 R155) and mechanisms to manage secure in‑service software updates (R156). Engineering standards such as ISO/SAE 21434 have been widely adopted as the baseline for lifecycle cybersecurity engineering. Compliance is no longer a checklist item; it is a precondition for market access and a determinant of supplier selection.
- Architectural shift: The industry is migrating from federated ECUs toward zonal and centralized (server‑based) E/E topologies to reduce wiring complexity, improve weight and cost efficiency, and enable over‑the‑air (OTA) service models. This shift rebalances the value chain between hardware vendors and software/middleware providers.
- Software‑defined vehicle economics: High‑performance compute (HPC), zonal controllers, and integrated middleware stacks are key enablers of cross‑domain functionality (powertrain, chassis, ADAS, infotainment). The winners will be those who can architect predictable software lifecycles, partitioned safety domains, and secure update channels.
Market trajectory and enterprise implications
At the aggregate level, the market’s forecasted growth at a ~16.55% CAGR signals a sustained investment cycle across the automotive value chain. For corporate strategists, three immediate implications stand out:
Automotive Cross Domain E E Architecture Market
- Prioritise modular, software‑centric roadmaps: The rate of value migration toward software and services requires rethinking product P&L, licensing models, and aftermarket revenue streams. Capital allocation decisions in 2026 should favour platforms that enable continuous feature delivery and monetization.
- Recalibrate supplier ecosystems: As compute and zonal architectures become mainstream, OEMs must rebalance sourcing away from discrete ECU suppliers toward providers that can deliver validated cross‑domain stacks or turn‑key HPC/ZCU solutions. For incumbent Tier‑1s, the imperative is to move up the stack into software and systems integration.
- Embed cybersecurity and functional safety into procurement: Given regulatory and certification imperatives, cybersecurity and safety engineering capability must be scored as first‑order procurement criteria rather than add‑ons. Vendors without demonstrable ISO/SAE 21434 and R155–R156 pathways will face escalating costs to qualify.
Technology inflection points to watch in 2026
The report highlights a small number of technology vectors that will determine winners and losers over the next three years:
- High‑performance vehicle computers (HPCs) and zonal controllers — enabling consolidation of cross‑domain functions while supporting mixed‑criticality workloads.
- SoCs, microcontrollers and power semiconductors tuned for zonal topologies — offering deterministic real‑time compute alongside efficient power delivery.
- Cloud‑native software platforms and middleware that support partitioning, virtualization, vehicle‑to‑cloud orchestration and OTA pipelines.
- Validated cybersecurity frameworks and toolchains that enable certification and evidence generation for type approval processes.
Competitive landscape — strategic positioning of core players
The market is led by a mix of traditional automotive systems suppliers, tier‑one integrators, and semiconductor specialists. Our qualitative assessment of core players exposes where competitive advantage is concentrated and where gaps remain:
- Robert Bosch GmbH (Germany): Strong in cross‑domain vehicle computers and zone‑oriented architectures; technical depth in systems integration and broad OEM relationships. Bosch’s portfolio positions it well to supply validated HPC platforms and integration services.
- Continental AG (Germany): Actively demonstrating cross‑domain HPCs and rolling series introductions of zone control units. Continental’s recent implementations in technology vehicles underline its capability to accelerate OEM pilot programs into production programs.
- Aptiv PLC (Ireland): Focused on Smart Vehicle Architecture with a clear separation of I/O and compute; investing in software platforms that orient toward cloud‑native principles. Aptiv’s modular approach reduces integration friction for OEMs shifting to zonal topologies.
- ZF Friedrichshafen AG (Germany) and DENSO Corporation (Japan): Both supply domain controllers and zonal solutions, with a strong foothold in motion, chassis and safety domains — critical where functional safety and performance are non‑negotiable.
- Valeo SE (France) and Magna International Inc. (Canada): Offering electrification and systems components that bridge hardware and systems integration needs, particularly in ADAS and EV powertrain domains.
- NXP Semiconductors (Netherlands) and Infineon Technologies AG (Germany): Semiconductor vendors that underpin zonal architectures through SoCs, microcontrollers and power electronics. Their roadmap alignment with automotive standards and toolchains is a gating factor for platform suppliers.
Collectively, these firms form a market with meaningful concentration among the front‑runners; however, there remains room for specialised entrants, software pure‑plays and alliances that can solve integration and certification bottlenecks.
Practical content you can act on
PW Consulting’s report is designed as an operational instrument for 2026 planning cycles. It goes beyond high‑level forecasting to provide executable assets, including:
- Decision frameworks and scenario models for centralised versus zonal migration — inclusive of sensitivity tests for semiconductor supply, software development cadence and OTA readiness.
- Supplier and technology scorecards — evaluating technical fit, certification readiness, delivery risk and commercial terms across cross‑domain HPC, ZCU, middleware and SoC suppliers.
- Reference architecture blueprints and integration checklists — showing partitioning strategies for mixed‑criticality workloads, secure boot/chain of trust patterns, and recommended interfaces for I/O separation.
- Regulatory compliance playbooks — practical steps to meet UNECE WP.29 R155/R156 and ISO/SAE 21434, including evidence packages, test plans and audit readiness milestones.
- TCO and ROI models — enabling procurement and finance teams to compare lifecycle costs (hardware, software, OTA operations, security maintenance) and quantify service revenues unlocked by software‑defined features.
- Migration roadmaps and program templates — staged integration plans that align feature delivery, certification gates and supplier onboarding across multi‑year vehicle programs.
Recommendations for 2026 executive action
Based on the modelled growth path and industry dynamics, we advise executives to take the following prioritized actions in 2026:
- Finalise platform choices early: Lock in a primary compute and middleware architecture for your 2028 model cycle now to avoid costly mid‑program rework.
- Invest in software ops and OTA capability: Build or partner for a secure, resilient OTA pipeline with clear metrics for patch delivery, rollback and remote diagnostics.
- Make cybersecurity a product differentiator: Integrate CSMS practices into product marketing and OEM contracting; certification should be framed as value rather than cost.
- Pursue focused M&A and strategic alliances: Target companies that complement missing capabilities (e.g., middleware, security toolchains, functional safety service providers) rather than broad horizontal plays.
- Engage standards and regulatory bodies: Allocate resources to shape and anticipate compliance interpretation, reducing certification uncertainty for upcoming programs.
How this report supports board‑level and program‑level decisions
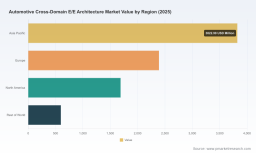
PW Consulting’s analysis bridges board‑level strategy and program‑level execution. Board members receive scenario outputs that quantify strategic trade‑offs (e.g., capture of software monetization vs. capital intensity of central compute), while program leads receive integration checklists, supplier scorecards and RFP templates to accelerate vendor selection and reduce qualification time. Importantly, our approach protects commercial sensitivity: the report’s executive sections summarise directional market sizing and growth dynamics, while our client portal contains the detailed regional, component and vehicle‑type splits behind validated assumptions and stress‑tested forecasts.
Next steps and access
For executives preparing 2026 budgets, the report provides a pragmatic combination of market projection, supplier analysis and implementation playbooks to reduce execution risk and accelerate time‑to‑value. To obtain the full dataset (including regional and component breakdowns, supplier heatmaps, and the detailed quantitative models referenced in this briefing), please visit the PW Consulting report page or contact our Automotive Practice. The public briefing above is intentionally selective — it aims to convey the strategic contours without disclosing the granular intelligence reserved for the full report and client engagements.
PW Consulting remains available to run tailored strategy workshops, construct bespoke migration roadmaps, and support vendor selection and negotiation for organisations committing resources in 2026. In a market growing at double‑digit rates with regulatory and architectural inflections accelerating, early, well‑informed moves will compound advantage.
For detailed analysis of this topic, please visit the official page: Automotive Cross Domain E E Architecture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com