

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Robot Joint Actuator Market to Surge from USD 20,185.55 Million in 2025 to USD 66,310.66 Million by 2032 at an 18.52% CAGR

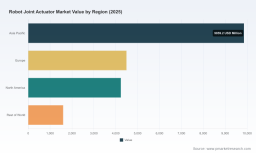
Robot Joint Actuator Market: Strategic Imperatives for 2026 — PW Consulting Analysis
Executive trailer
As robotics moves from bespoke prototypes to mass-deployed systems, joint actuators have transitioned from commoditized motion components to strategic system enablers. PW Consulting’s new Robot Joint Actuator Market report — anchored on a 2025 base year with a forecast through 2032 — quantifies a sustained, high-growth runway (CAGR: 18.52%) and translates that growth into actionable choices for executives planning 2026 investments. This release outlines the report’s practical value, highlights competitive dynamics reshaping supplier selection, and frames the regulatory and materials headwinds that should inform near-term strategy. For full tables, segmentation, and proprietary models, please visit our report page.
Robot Joint Actuator Market
Market trajectory and macro context
Between the historical period and 2025, the global robot joint actuator market has accelerated materially. PW Consulting’s top-line sizing shows a clear inflection: a market that has more than doubled in size over the last five years is projected to continue expanding robustly through 2032. The forecast period (2026–2032) is characterized by compound annual growth of 18.52%, driven by rapid uptake of integrated actuator modules in humanoid, collaborative, and advanced industrial robots, plus new demand from service and medical applications.
Robot Joint Actuator Market
Two macro forces underpin this expansion. First, systems-level requirements — higher torque density, lower backlash, and embedded control — are shifting purchasing decisions from discrete motors and gearboxes to integrated joint modules. Second, regulatory and safety updates introduced in 2025 have raised compliance thresholds for collaborative and industrial deployments, increasing the value of certified, fully integrated actuator solutions.
Robot Joint Actuator Market
Why 2026 is a strategic inflection point
- Standards and compliance: The major ISO revisions published in 2025 (and their adoption in ANSI/A3 guidance) expand requirements for collaborative use cases and introduce explicit cybersecurity and classification guidance relevant to joint actuators. Companies planning 2026 procurement or product launches must bake in compliance testing and security-by-design to avoid rework.
- Productization of integration: Recent product introductions and trade show demonstrations in early 2026 signal a new phase of maturation where suppliers offer sealed, thermally managed, encoder-redundant actuator packages rather than component stacks. This reduces system integration risk for OEMs but alters supplier bargaining power.
- Strategic supplier relationships: High-profile supply agreements and alliances announced in 2026 illustrate the industry pivot to long-term actuator sourcing partnerships for major robot platforms. Buyers should anticipate multi-year supply commitments as the default for flagship programs.
What the PW Consulting report delivers (practical content for decision-makers)
- Actionable market sizing & scenario forecasts: Top-down and bottom-up models with three scenario paths tied to adoption of integrated actuators, humanoid rollouts, and industrial automation cycles for 2026–2032.
- Supplier evaluation framework: A reproducible scorecard covering torque density, thermal management, functional safety, cybersecurity readiness, mean time between failures (MTBF), and total cost of ownership — designed for procurement teams to run quick comparisons.
- Technology maturity and roadmaps: Comparative analysis of harmonic drives, RV reducers, frameless motors, and embedded control electronics, with guidance on which architectures optimize for weight, precision, or cost for specific robot classes.
- Practical procurement toolkit: Sample RFP language, SLA templates for actuator life and performance, a TCO calculator calibrated to 2026 supply conditions, and vendor negotiation playbooks.
- Supply chain risk heat map: Identification of material dependencies (e.g., high-carbon steel alloys used in flexsplines), single-source bottlenecks, and mitigation levers including nearshoring, dual sourcing, and strategic inventory policies.
- Regulatory compliance playbook: Stepwise plan to align design and manufacturing to ISO 10218-2025 and ANSI/A3 R15.06-2025 revisions, including recommended external test labs and certification timelines.
- M&A and partnership screening: A shortlist of capability gaps, target profiles, and valuation considerations for buyers seeking inorganic routes to add torque density, integration capabilities, or regional production capacity.
Competitive landscape: dynamics and strategic implications
The market shows moderate concentration at the top, implying a mix of incumbent strength and meaningful space for well-positioned challengers. Several archetypes are now visible across suppliers:
- Specialist precision houses: Firms with deep IP in strain-wave gearing and zero-backlash reducers continue to command premium positions by protecting high-precision niches and providing mission-critical components for collaborative and industrial use cases.
- Integrated actuator pioneers: A new wave of vendors are offering full joint modules (motor, gearbox, encoder, driver, brake, thermal management) aimed at humanoid and service robot OEMs — these suppliers reduce integration costs and accelerate time-to-market for robot builders.
- System incumbents with vertical reach: Large automation OEMs and motion-control groups leverage scale to bundle actuators into broader automation solutions, affecting channel dynamics and after-sales support expectations.
Key competitive signals for procurement and product strategy in 2026:
- Suppliers showcasing integrated modules at industry shows indicate a shift from component procurement to systems sourcing. Buyers should reassess supplier evaluation criteria to include embedded electronics, thermal sealing, and IP lifecycle management.
- Partnership announcements linking actuator suppliers to flagship robot programs demonstrate a preference for co-engineered solutions. Securing early-stage design partnerships can be a differentiator for OEMs targeting rapid deployments.
- Geographic and operational footprints matter: while leading precision gear manufacturers retain engineering leadership, several fast-growing players from Asia are closing the gap on torque density and control integration — creating choices between premium incumbents and cost/feature-competitive challengers.
Operational risks and material/regulatory headwinds
Several non-market factors are set to materially affect 2026 decisions:
- Material fatigue and sourcing: Critical flexspline components typically use high-carbon steel alloys engineered for extended fatigue life; sourcing quality-controlled alloys and maintaining fatigue testing capacity are non-trivial constraints for volume programs.
- Compliance and cybersecurity: The 2025 ISO and ANSI updates expand expectations for collaborative operation and cybersecurity. Compliance timelines and third-party certification capacity should be factored into product launch schedules and supplier selection.
- Cost structure exposure: For advanced humanoid platforms, actuators can represent the dominant portion of unit production cost. Design choices that improve torque-to-weight ratio and reduce part count will materially improve manufacturing economics.
- After-sales and service requirements: As actuators become more integrated, after-sales capabilities (predictive maintenance, embedded diagnostics, firmware update pathways) will be decisive differentiators in long-term TCO conversations.
Strategic recommendations for 2026 decisions
For executive teams planning capital allocation, procurement, or R&D in 2026, PW Consulting recommends the following prioritized actions:
- Rebase supplier scorecards: Update procurement evaluation matrices to prioritize integrated actuator capabilities, embedded safety/cyber features, and field service pathways rather than individual component price.
- Pursue selective partnerships: Establish co-development agreements with one integrated-actuator supplier and one precision-reducer specialist to mitigate technology and supply risk while preserving negotiation leverage.
- Invest in design-for-manufacture for torque density: Allocate R&D budget to actuator architecture choices that reduce assembly complexity and thermal risk — improvements here compound across product lifecycles.
- Anticipate compliance resource needs: Budget for external certification and cybersecurity assessments early in the product development cycle; rework driven by late-stage compliance failures is costly and time-consuming.
- Lock in strategic inventory and dual sourcing: For programs where actuator unit cost dominates, secure multi-year supply agreements and consider strategic inventory buffers for critical materials to protect schedules during ramp phases.
- Evaluate M&A selectively: Target acquisitions that add unique torque-density IP or integrated actuator manufacturing capability, enabling faster time-to-market for advanced robot platforms.
How PW Consulting’s analysis helps you act in 2026
Our report is designed as an operational playbook as much as a market study. We translate growth forecasts and scenario models into checklists, procurement templates, and supplier scorecards that procurement, product, and corporate development teams can use immediately. Whether you are finalizing a sourcing decision, sizing an R&D program, or planning an acquisition, the report provides the calibrated inputs and practical templates to reduce execution risk and compress decision timelines.
Next steps
This briefing intentionally surfaces strategic insights while reserving the proprietary segment-level matrices, vendor benchmarking data, and downloadable procurement toolkits for the full report. To access the detailed segmentations, supplier scorecards, scenario models, and the downloadable procurement toolkit referenced above, please visit our report page. PW Consulting stands ready to run custom workshops to apply these findings to your product roadmaps, sourcing strategies, and M&A evaluation processes for 2026.
For detailed analysis of this topic, please visit the official page: Robot Joint Actuator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com