

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Stadium Access Control Systems Market to Reach USD 1,778.7 Million by 2032, Growing at 8.2% CAGR (2026–2032)

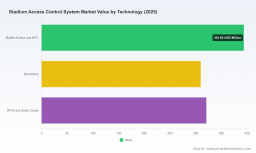
Stadium Access Control System Market — Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest industry brief on the Stadium Access Control System market is released at a critical juncture. As stadium operators, integrators, and technology investors finalize capital and operational plans for 2026, our research synthesizes macro growth trajectories, regulatory drivers, and competitive moves into an actionable playbook for strategic decisions. The study uses 2025 as its base year and projects the market through 2032, offering a forward-looking perspective designed to inform procurement, platform selection, and risk mitigation for high-density public venues.
Stadium Access Control System Market
Executive snapshot: growth, timing, and why it matters
Between 2020 and 2025 the stadium access control market experienced steady expansion driven by large-scale event preparations, renewed investment in venue modernization, and accelerated adoption of frictionless access technologies. Our analysis places 2025 as the base year and projects continued growth into the forecast window 2026–2032 at a compound annual growth rate (CAGR) of 8.2%. By 2026 the market is forecast to register a meaningful uplift versus 2025, with the longer-term trajectory culminating in materially larger market size by 2032. For executives planning multi-year procurement cycles, these dynamics translate directly into capital allocation choices, timing of refresh cycles, and vendor negotiation leverage.
Stadium Access Control System Market
Why 2026 is an inflection year
- Major events and regulatory convergence: Preparations for global sporting events and heightened national security expectations have already pushed stadiums toward integrated credentialing, stricter access controls, and counterterrorism posture alignment. These regulatory impulses are not temporary — they reshape minimum viable requirements for new systems and upgrades.
- Technology supply-side maturation: Cloud-native access control platforms, AI-based screening, and high-throughput gate hardware have moved past proof-of-concept into commercial deployments. This evolution reduces technology risk while raising expectations for interoperability with surveillance, ticketing, and venue-management systems.
- Connectivity as an enabler: The adoption of small-cell and neutral-host deployment models in arenas is enabling access control systems to operate in higher-fidelity, low-latency environments — a prerequisite for frictionless mobile ticketing, biometric validation, and real-time threat intelligence integrations.
Market dynamics and technological inflection points
- Frictionless entry becomes table stakes. Mobile access, NFC, and credential portability are moving from premium differentiators to baseline requirements for many new installations, especially in venues prioritizing guest experience and throughput.
- Biometrics and AI for risk-based screening. Facial authentication and behavioral analytics are increasingly paired with physical barriers and video analytics to enable differentiated access levels (players, staff, VIPs) and to support pre-emptive threat detection.
- Platform convergence. Cloud-managed access control is converging with video surveillance, alarms, and guest management systems to form unified security platforms — a pattern visible in recent stadium modernizations where operators prioritize a single pane of glass for incident response and post-event forensics.
- Hardware modernization and lifecycle economics. Turnstiles, full-height gates, and sensor-embedded ingress points are being re-specified for durability and throughput, with procurement decisions driven by lifecycle cost models and expected integration points rather than hardware price alone.
- Services growth. Managed services, integration projects, and ongoing security operations center (SOC) tie-ins are increasingly part of the value proposition, shifting procurement from one-off CapEx purchases to hybrid CapEx/Opex models.
Competitive landscape: who matters and why
The market remains moderately concentrated: the top three suppliers do not dominate the majority of the market, and the top five account for less than half — a structure that favors both established integrators and nimble specialist vendors. This competitive geometry creates opportunities for strategic partnerships, white-label deployments, and regional champions to secure meaningful share.
Stadium Access Control System Market
- Axess AG (Anif near Salzburg, Austria) — Specializes in turnstiles and ticket-reading systems purpose-built for stadia. Their installed base across major events underlines deep domain expertise in high-throughput applications and long-cycle vendor relationships with venue owners.
- SKIDATA GmbH (Austria) — Focuses on integrating NFC, biometrics, and multimedia ticketing for frictionless entry. Their strength lies in high-performance throughput solutions and a product architecture optimized for peak-event loads.
- Honeywell International Inc. (United States) — Leverages broad building-management and security experience to deliver integrated, cloud-enabled access control platforms used across high-profile venues. Their scale favors global deployments and multi-stadium rollouts.
- Avigilon (Motorola Solutions) — Distinguished by deep video-surveillance integration and analytics, making them a preferred partner where access control must be tightly coupled to real-time video and AI-driven detection.
- Dormakaba and Bosch Security Systems — Both bring extensive portfolios of access hardware and systems integration expertise, focusing on reliability and standards-compliance for high-traffic environments.
- HID Global (ASSA ABLOY) — A leader in RFID and digital key platforms; recent product deployments emphasize scalability and durability for stadium applications.
- Turnstile specialists (e.g., Hayward Turnstiles, CAME) — Continue to compete on mechanical reliability, customization for crowd management, and installation footprint considerations.
- AI and screening specialists (e.g., Evolv Technologies, Alcatraz AI) — Represent the fastest-growing niche, offering AI-based weapons detection and facial-authentication solutions increasingly deployed at player, staff, and fan ingress points.
Recent vendor activity underscores the market’s active modernization cycle: deployments of digital access platforms for stadium security upgrades, venue-wide installations of AI screening systems ahead of competitive seasons, and targeted video and access system upgrades to meet international venue standards. These illustrate how technology choice is being driven by event-ready compliance, throughput needs, and integration agility.
What the PW Consulting report delivers (practical, non-trivial content)
Beyond headline forecasts, the full PW Consulting report is purpose-built as a decision-support tool for 2026 planning cycles. It includes:
- Actionable procurement frameworks — RFP templates, evaluation scorecards, and pilot acceptance criteria tailored to stadium environments.
- Technology roadmaps — recommended adoption timelines for mobile access, biometrics, AI screening, and cloud migration, sequenced to minimize operational disruption.
- Integration playbooks — patterns for unifying access control with video, ticketing, and guest management systems, including recommended APIs and data flows for high-availability deployments.
- Lifecycle and TCO models — scenario-based financials to weigh CapEx vs Opex and to model phased modernization strategies across multiple seasons.
- Regulatory and security checklists — compliance guidance for event-driven credentialing, counterterrorism coordination, and privacy-preserving biometric deployments.
- Vendor benchmarking — qualitative strengths/weaknesses, go-to-market models, and recommended use-cases for tier-one integrators, turnstile manufacturers, and AI specialists (note: core segmentation tables and granular vendor scores are reserved for the full report).
Strategic recommendations for 2026 procurement and operations
- Prioritize open, cloud-friendly architectures that enable phased rollouts. Immediate vendor selection should favor platforms with proven APIs and a roadmap for unified security operations.
- Design for throughput first. Benchmark vendor hardware and software against peak-event ingress/egress scenarios and require live stress-testing as part of procurement acceptance.
- Adopt a hybrid approach to biometrics and mobile credentials. Use biometrics where identity assurance is mission-critical (back-of-house, VIP), and mobile/NFC for fan ingress to balance UX, privacy, and cost.
- Incorporate AI screening selectively. Deploy AI-based weapons and anomaly detection at selected high-risk points with human-in-the-loop validation to reduce false positives and operational friction.
- Ensure connectivity readiness. Require neutral-host and small-cell compatibility in technical requirements to support future enhancements in low-latency control and telemetry.
- Negotiate services and SLAs. Given the increasing role of managed services, make SLAs for uptime, incident response, and breach notification clear, and price them against integration complexity.
- Plan for interoperability testing ahead of major events. Mandate pre-event simulations and failover rehearsals as contractual conditions for final acceptance.
- Balance consolidation with best-of-breed. Where unified platforms reduce operational overhead, consolidation makes sense; where performance or function is mission-critical, retain specialist partners with clear integration obligations.
Conclusion — the strategic value of this report to 2026 decision-makers
For stadium owners, systems integrators, and technology investors, 2026 represents a window to convert recent regulatory pressure and technology maturation into durable operational value. The market’s growth trajectory and ongoing vendor activity create both opportunity and complexity. PW Consulting’s Stadium Access Control System market report translates macro growth projections, regulatory realities, and vendor dynamics into hands-on guidance: procurement artifacts, risk frameworks, technical integration playbooks, and go-to-market scenarios that align capital expenditure with operational readiness.
To maintain competitive crowd-experience and safety standards while optimizing total cost of ownership, decision-makers must combine strategic timing, judicious vendor choice, and rigorous acceptance testing. PW Consulting’s full report provides the granular tools and vendor-level insight required to do exactly that — including the detailed segmentation tables, vendor scorecards, and modelled scenarios that underpin our recommendations. For access to the complete intelligence suite and tailored advisory engagements, please consult PW Consulting’s market portal and advisory services.
For detailed analysis of this topic, please visit the official page: Stadium Access Control System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com