

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Disposable Hemoperfusion Cartridge Market Poised to Hit USD 1,547.58 Million by 2032

Disposable Hemoperfusion Cartridge Market — Strategic Outlook for 2026 Decision‑Makers
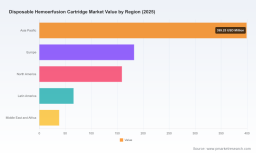
PW Consulting’s new market intelligence brief on the Disposable Hemoperfusion Cartridge Market is designed as a decision‑grade resource for executives who must set course in 2026. Built from a structured review of historical performance (2020–2025), primary interviews, device registries and regulatory filings, the report synthesizes a top‑down market model, competitive benchmarking, and scenario planning across a 2026–2032 forecast horizon. At the macro level the market demonstrates robust expansion — having grown from USD 555.2 million in 2020 to USD 845.5 million in 2025 — and is projected to continue expanding to an estimated USD 927.8 million in 2026 and roughly USD 1.55 billion by 2032 at a compound annual growth rate of 9.02%. This trajectory creates a timely window for strategic moves but also demands careful prioritization given regulatory and clinical complexity.
Disposable Hemoerfusion Cartridge Market
What the report delivers — practical, actionable intelligence
-
Proprietary market model and demand scenarios: A transparent forecast engine driven by clinical adoption levers (ICU penetration, renal replacement therapy bundling, surgical usage), supplier capacity constraints, and reimbursement sensitivity. The model is delivered in an interactive workbook so teams can test “what‑if” levers for 2026 budgeting and three‑year roadmaps.
Disposable Hemoerfusion Cartridge Market -
Commercial playbooks: Go‑to‑market options for device manufacturers, distributors and hospital system buyers including channel design, tendering strategies, and clinical evidence sequencing that accelerate hospital formulary adoption without overinvesting in low‑probability pathways.
Disposable Hemoerfusion Cartridge Market -
Regulatory and clinical tracker: Rolling summary of global regulatory positions, recent pre‑submission engagements, and key clinical evidence gaps by indication — enabling regulatory teams to prioritize De Novo/PMA pathways and plan pivotal studies in line with payer expectations.
-
Manufacturing and supply chain assessment: Clean‑room capacity mapping, critical raw material dependencies (resins, activated carbons, immobilized antibiotic fibers), and a supplier risk heat map to inform near‑term contract manufacturing or vertical integration decisions.
-
Competitor intelligence and M&A screening: Vendor scorecards that combine clinical footprint, manufacturing scale, go‑to‑market reach and strategic fit, together with an M&A suitability matrix designed for acquirers and PE sponsors evaluating roll‑up or bolt‑on plays.
Why 2026 is a strategic inflection point
-
Market momentum and capital allocation: With the market expanding at a double‑digit near‑mid single‑digit CAGR over the forecast period, capital allocated in 2026 will disproportionately influence share positions across the 2026–2029 window. Firms that pre‑commit to scalable production or high‑value clinical programs can capture early adopter premium while late movers risk commoditization.
-
Regulatory sequencing matters: Recent regulatory motions and high‑profile pre‑submissions indicate shifting clearance pathways for hemoperfusion devices in several indications. Manufacturers should align regulatory strategy with clinical program design to avoid costly pivots — for example, distinguishing pathways for endotoxin‑targeted polymyxin solutions versus broad cytokine adsorbers.
-
Clinical evidence is the gating factor for hospital uptake: Adoption in critical care and cardiac surgery is increasingly evidence‑driven. Payers and large health systems are now requesting outcomes data beyond physiological endpoints. 2026 investments in pragmatic randomized or registry‑linked evidence will materially improve negotiating leverage.
-
Supply resilience will determine commercial reach: Sterile single‑use consumables require both clean‑room capacity and validated supply chains for medical‑grade sorbents. Firms with flexible capacity options — in‑house or contracted — will win larger tenders and rapid geographic rollouts.
Competitive landscape — who matters and why (high‑level)
The market is populated by a mix of specialized hemoperfusion specialists, diversified blood‑purification incumbents, and regional OEMs. Our analysis identifies a concentrated top tier alongside numerous regional players competing on cost or niche clinical claims. Market concentration analysis in the report highlights why scale and channel depth are strategic advantages: three leading firms capture a majority share of revenues, and the top five firms capture a material portion of the market, creating both entry barriers and partnership opportunities depending on strategic intent.
-
Jafron Biomedical Co., Ltd. (Zhuhai, China) — prominent volume player with a broad HA portfolio that targets protein‑bound toxins, middle molecules and cytokines. Jafron’s automated production footprint and reported annual manufacturing capacity in the multi‑million unit range are central to its ability to serve high‑volume markets and win price‑sensitive tenders.
-
CytoSorbents Corporation (Monmouth Junction, NJ, USA) — technology leader in polystyrene‑divinylbenzene copolymer cartridges with notable adoption in critical care domains. CytoSorbents’ cumulative device use and recent moves — including a commercial launch for multi‑cartridge workflows and regulatory trajectory toward De Novo submissions for new cardiac surgery applications — make it a bellwether for clinical acceptance of cytokine adsorption strategies.
-
Regional and specialty players — including established Japanese firms (polymyxin B fiber cartridges), legacy acute‑care consumables suppliers, and rapidly scaling Chinese and Indian manufacturers — remain relevant for specific hospital pathways and price‑competitive segments. Several firms are focusing on integrated solutions (e.g., HD+HP combinations) and bundled service approaches.
Recent industry signals you cannot ignore
-
Commercial / regulatory momentum: A major supplier announced a multi‑cartridge “HotSwap” commercial offering and has advanced regulatory discussions with the U.S. authority for cardiac surgery indications. Concurrent regulatory rulings and historical reclassification proposals demonstrate that global regulatory posture can shift quickly and change product marketability across jurisdictions.
-
Market access and evidence convergence: The balance between emergency‑use pathways and full regulatory clearances in various markets underlines the need for tailored evidence generation plans. Hospitals increasingly require local registry data and cost‑effectiveness narratives to adopt new consumables at scale.
-
Manufacturing scale wins tenders: Automated production lines and ISO‑class clean workshops provide a decisive commercial advantage for high‑volume purchasing organizations. Buyers prize supply visibility as much as unit economics.
Risks and mitigations for 2026 planning
-
Regulatory reversal or divergent regional requirements — mitigation: maintain parallel regulatory tracks, prioritize pivotal endpoints that satisfy both clinical and regulatory stakeholders, and engage early with conjugate regulatory bodies.
-
Clinical evidence gaps — mitigation: deploy hybrid trial designs and real‑world evidence capture tied to hospital EMR to accelerate payer conversations and build case studies for key opinion leaders.
-
Supply chain shocks and capacity constraints — mitigation: diversify resin and sorbent suppliers, secure forward contracts for critical polymers and sterilization capacity, and explore geographic manufacturing redundancy.
-
Price compression — mitigation: shift value conversations from unit price to total cost of care, offering bundled outcomes‑based contracts and service agreements that share clinical risk with providers.
How to use this intelligence in your 2026 playbook
-
For CEOs and corporate strategy teams: Use the interactive model to stress‑test acquisition targets and organic expansion plans. Focus on nodes where a modest CAPEX commitment yields outsized capacity or regulatory advantage.
-
For R&D and clinical leaders: Prioritize indication selection where regulatory routes and evidence requirements align with your current device profile; concentrate on pragmatic endpoints that purchasers value most.
-
For commercial teams: Build channel strategies that combine direct hospital relationships with specialty distribution partners; design value propositions that reduce operational friction (e.g., simplified inventory, training bundles, and rapid exchange services).
-
For investors and corporate development: Target assets that either fill capability gaps (manufacturing or regulatory footprint) or provide steep learning curves for clinical adoption; avoid substitutable early‑stage technologies without clear regulatory paths.
About PW Consulting’s methodology and next steps
Our assessment combines top‑down market sizing, bottom‑up supplier capacity checks, clinical literature synthesis and a proprietary vendor scoring algorithm that weights clinical footprint, manufacturing scale, regulatory posture and commercial reach. The published brief is intentionally a strategic “trailer”: it demonstrates the rigor and implications of our analysis while reserving detailed sub‑segment revenue splits, regional allocations and company‑level financials for the full report and interactive model available on our portal.
If your 2026 decisions hinge on capacity commitments, regulatory investments or targeted M&A, PW Consulting can provide: a confidential workshop to run customized scenarios, a bespoke supplier diligence packet, or a regulator‑specific evidence roadmap tailored to your product portfolio. Access to the full dataset and model is deliverable under subscription or project engagement.
Call to action
PW Consulting’s Disposable Hemoperfusion Cartridge Market Report is the operational intelligence playbook many teams lacked in prior funding cycles. For the full forecast, detailed segment analytics, vendor scorecards and the interactive model that supports actionable 2026 decisions, please visit our report page or contact our strategy desk to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Disposable Hemoerfusion Cartridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com