

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Security MCU Market to Grow at 8.2% CAGR from USD 5,124.5 Million in 2025 to USD 8,896.97 Million by 2032 — Asia Pacific Leads with USD 2,158.1M; Hardware-based Secure Elements Dominate; CR3 at 48.55%

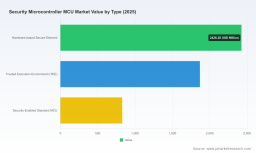
Security Microcontroller (MCU) Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
PW Consulting’s forthcoming Security Microcontroller MCU Market report (base year 2025; historical coverage 2020–2025; forecast horizon 2026–2032) synthesizes the commercial, technical, and geopolitical forces that will determine winners and losers in the security MCU ecosystem over the next seven years. The total market has expanded materially over the past half‑decade, exceeding USD 5.1 billion (USD Million basis) in 2025, and our model projects sustained growth at a compound annual growth rate (CAGR) of 8.2% through 2032. By 2032 the global market is forecast to approach the low‑single‑digit billions more than today, driven by escalating device-level security requirements across automotive, IoT, payments, and industrial domains.
Security Microcontroller Mcu Market
Why this matters for 2026 decision‑makers
For executives making procurement, product, or M&A decisions in 2026, the security MCU market is no longer an incremental engineering consideration — it is a strategic battleground. Security MCUs now embed regulatory compliance, brand trust, and service continuity into product roadmaps. The growth trajectory and underlying dynamics captured in our report create a narrow window for decisive moves: whether to vertically integrate hardware security, accelerate certification timelines, diversify supplier footprints, or pursue M&A to secure IP and scale.
Security Microcontroller Mcu Market
Market dynamics shaping 2026 strategy
-
Regulatory pressure and compliance complexity: Ongoing export controls and evolving certification standards have made compliant sourcing and design mandatory rather than optional. Our analysis shows these regulatory dynamics are already altering supplier selection matrices and increasing the value of security‑centric roadmaps.
Security Microcontroller Mcu Market -
Supply chain capacity constraints: Semiconductor capacity tightness—exacerbated by surging demand for AI‑related chips—has extended lead times for MCUs and memory components. Procurement teams must now plan against multi‑quarter windows and build component‑level redundancies.
-
Price volatility and cost pass‑through: Multiple leading suppliers announced significant price increases in early 2026. These shifts are reshaping total cost of ownership assessments and are increasing incentives for long‑term purchase commitments or alternative sourcing strategies.
-
Geopolitical fragmentation: Trade tensions and export restrictions continue to fragment the global supply base, creating differentiated regional risk profiles that materially affect manufacturing and certification timelines.
-
Technology inflection — post‑quantum and integrated trust: Select vendors and startups are accelerating adoption of quantum‑resistant primitives and integrated root‑of‑trust platforms. Early deployments and vendor partnerships in 2026 signal a multi‑year transition that will affect upgrade cadence and hardware design choices.
Competitive landscape — high‑level takeaways
The security MCU market exhibits a moderate level of concentration: the top three vendors account for a substantive portion of market revenues, and the top five broaden that leadership position further. This structure creates both opportunities and risks for buyers and challengers. Consolidation among established semiconductor incumbents remains the dominant near‑term scenario, but the window for focused entrants to capture niche security workloads—particularly those centered on post‑quantum capabilities or specialized certification stacks—remains open.
-
NXP Semiconductors (Eindhoven, Netherlands) — Offers a mature portfolio of smartcard‑grade security microcontrollers and secure element families. NXP’s emphasis on cryptographic acceleration and comprehensive security ecosystems (including EdgeLock) makes it a de‑risked partner for payment and eID programs. Strategic consideration: prioritize long‑lead contracts for mission‑critical programs where certification timelines are binding.
-
Infineon Technologies AG (Neubiberg, Germany) — Blends automotive and industrial security capabilities with roots in hardware root‑of‑trust and hardware crypto. Infineon’s product set targets rigorous functional safety and cybersecurity requirements, making it a natural fit for automotive Tier‑1s and industrial OEMs seeking integrated safety‑security stacks.
-
STMicroelectronics (Geneva, Switzerland) — Maintains a broad lineup spanning smartcard‑grade secure MCUs and general‑purpose MCUs with certified security profiles. ST’s 2026 product introductions underscore a strategy of moving advanced security features down the stack to address high‑volume IoT and industrial segments.
-
Microchip Technology Inc. (Chandler, Arizona, USA) — Positions secure microcontrollers in traditional embedded pockets (industrial, consumer, IoT) and emphasizes strong toolchains and engineering support for rapid integration.
-
Renesas Electronics (Tokyo, Japan) — Combines embedded compute with security features geared to automotive and connected‑device applications, appealing to customers prioritizing end‑to‑end platform integration.
-
Texas Instruments (Dallas, Texas, USA) — Continues to serve industrial and edge markets with a pragmatic approach to hardware security primitives and ecosystem support.
Recent vendor activity in early 2026 highlights two themes: (1) incumbents are pushing certified, entry‑level secure MCUs to accelerate market adoption, and (2) specialist platforms are moving post‑quantum primitives into production trials. For example, STMicroelectronics launched and showcased new Cortex‑M33 based MCUs with elevated security certifications at industry events in March 2026, while deployments of post‑quantum capable secure microcontroller platforms were confirmed in early 2026 by specialist providers. These moves foreshadow a two‑tier market: broadly adopted certified MCUs for mass IoT/automotive use and carve‑out niches for advanced cryptographic capability.
What PW Consulting’s report delivers — practical outputs for immediate action
-
Robust market sizing and scenario forecasts (base year 2025; forecast 2026–2032) with transparent assumptions and sensitivity analyses to stress‑test decisions under different macroeconomic and supply scenarios.
-
Vendor scorecards and decision matrices that translate technical attributes (e.g., root‑of‑trust, crypto acceleration, tamper resistance, certification readiness) into commercial recommendations for procurement, product, and security teams.
-
Security certification playbook mapping PSA/SESIP/CC/ISO pathways by product archetype, with timelines and cost buckets to accelerate product‑level compliance planning.
-
Supply chain risk heatmaps and pragmatic sourcing strategies (dual‑sourcing templates, long‑lead procurement calendars, and contract structures) tailored to security MCU use cases.
-
Technology roadmaps and migration paths for integrating post‑quantum readiness, firmware over‑the‑air (FOTA) secure update strategies, and lifecycle management for device fleets.
-
M&A and partnership playbooks identifying capability gaps, valuation multipliers, and integration risks for firms seeking to acquire or partner with security‑specialist vendors.
-
Executive one‑pagers and board‑ready briefing packs that frame investment options against market growth, concentration dynamics, and regulatory risk.
Note: this preview intentionally omits the detailed segment tables and region/application revenue breakdowns that underpin our recommendations — those granular datasets and company‑level financial mappings are included in the full report and supporting Excel deliverables.
Actionable recommendations for 2026
-
Prioritize supplier certification over lowest cost for new security‑critical product lines. The short‑term premium is outweighed by lower field risk and faster regulatory approval.
-
Lock in multi‑quarter procurement windows for components with long lead times; use staged purchase agreements tied to price‑adjustment clauses to manage volatility.
-
Fast‑track design work to accommodate quantum‑resistant primitives in products with >7‑year service lives; assess migration paths for existing deployed fleets.
-
Implement a tiered supplier strategy: retain incumbents for scale and certification maturity, while qualifying niche vendors for advanced cryptographic features and rapid innovation.
-
Build cross‑functional certification and security roadmaps that align product development, procurement, and regulatory affairs — our templates provide decision gates and cost estimates to operationalize this alignment.
-
Monitor consolidation and prepare agile M&A options; given current concentration metrics, selective acquisitions can accelerate capability acquisition and market access.
Methodology and credibility
Our analysis integrates primary interviews with OEMs, Tier‑1 buyers, and semiconductor suppliers, complemented by supplier financials, regulatory filings, and detailed supply chain modeling. The report uses a bottom‑up forecasting approach aligned with macro demand drivers and validated through multiple scenario stress tests. Base year metrics, historical trends, and forecast assumptions are fully documented in the report to support board‑level scrutiny and internal audit requirements.
Next steps — where to get the full intelligence
This preview is designed to surface the strategic levers and near‑term risks that will shape 2026 decisions. For the granular segment tables, vendor scorecards, certification timelines, and downloadable procurement templates that inform executable plans, please visit PW Consulting’s Security Microcontroller MCU Market report page and download the full report package. The full study contains the operative data, Excel models, and supplier matrices required to quantify and operationalize the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Security Microcontroller Mcu Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com