

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Portable X‑Ray Equipment Market to Reach USD 344.8 Million by 2032, Growing at a 5.2% CAGR

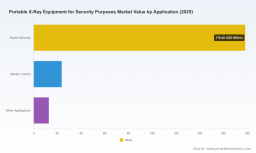
PW Consulting: Strategic Brief — Portable X‑Ray Equipment for Security Purposes Market (Base Year 2025) — A 2026 Decision Playbook
PW Consulting today publishes a strategic executive brief accompanying our full market research report on Portable X‑Ray Equipment for Security Purposes. Built for leaders in procurement, product strategy, corporate development, and national security programs, this brief synthesizes the macro trends and executive implications you need to make confident decisions in 2026 — while preserving the granular segment data and vendor scorecards for subscribers to the full report.
Portable X-Ray Equipment for Security Purposes Market
High‑level market context
The portable security X‑ray market has shown steady expansion through the first half of the decade and is positioned for continued, compounding growth through the next business cycle. Using 2025 as the base year, PW Consulting estimates the market size at USD 215.0 Million (revenue in USD Million). Our forecast model — anchored in historical performance from 2020–2025 and a scenario framework spanning 2026–2032 — projects growth to USD 344.8 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.2% over the forecast period.
Portable X-Ray Equipment for Security Purposes Market
These headline numbers reflect a market that is expanding moderately but steadily, underpinned by durable demand from aviation and border security, increasing adoption in law‑enforcement EOD and tactical teams, and a rising interest in mobile deployment models that lower the cost and time barriers of traditional screening programs.
Portable X-Ray Equipment for Security Purposes Market
Why 2026 is a strategic inflection point
-
Policy and reimbursement shifts create new commercial pathways. A notable regulatory development in early 2026 is the Centers for Medicare & Medicaid Services' finalization of allowances for HCPCS codes R0070 and R0075, which cover transportation of portable X‑ray equipment and personnel for home and nursing‑home visits. While this change originated in a clinical reimbursement context, it signals the growing policy acceptance of mobile imaging and service‑based delivery models — a capability set that security vendors can adapt for remote deployments, asset tracking, and as a revenue model for sustained field service.
-
Technology convergence is accelerating product differentiation. Advances in generator efficiency, detector sensitivity, and AI‑augmented image interpretation are shifting procurement criteria from pure hardware performance to system‑level value: speed, operator training overhead, integration with command centers, and lifecycle services.
-
Procurement cycles are shortening for pilot and capability‑proof projects, but overall conversion to volume purchases remains driven by multi‑year government budgets and capital planning — making 2026 a critical year to secure pilot wins that convert into multi‑year frameworks.
What PW Consulting’s full report delivers (practical, actionable content)
-
Market sizing and forecasting model (USD Million basis) with base year 2025 and detailed scenarios across 2026–2032. Our model is provided in workbook form for client re‑weighting under custom scenarios.
-
Procurement playbooks tailored to core buyer profiles (civil aviation security, border agencies, law enforcement EOD teams, postal and parcel screening operators), mapping decision timelines, evaluation criteria, and realistic procurement lead times.
-
Vendor benchmarking and scorecards that evaluate product portfolios across technical performance, field reliability, serviceability, software ecosystem, and export/compliance posture.
-
Regulatory and reimbursement matrix that connects device classification, export controls, and emerging reimbursement pathways (including the 2026 Medicare HCPCS updates) to commercial routes and go‑to‑market risks.
-
Technology deep dives on imaging modalities, power & weight tradeoffs, backscatter vs transmission imaging, digital detector roadmaps, and AI/analytics integration strategies.
-
Anonymised procurement case studies and total cost of ownership (TCO) calculations illustrating common failure modes in deployments and how to mitigate them.
-
Strategic recommendations for product, service, and M&A plays with prioritised action roadmaps for 6, 12 and 24‑month horizons.
Core growth drivers and strategic implications
-
Expanded threat vectors and operational decentralisation — airports and border crossings remain steady foundational demand centers, but growth is increasingly driven by mobile requirements (rapid response EOD, remote facility screening, parcel and mail inspection in dispersed postal networks). Companies that combine compact hardware with robust software and field training will capture outsized value.
-
Servitization unlocks recurring revenue — long procurement cycles for capital devices make service contracts, training, software subscriptions and field analytics the highest‑margin, fastest‑growing components of lifetime revenue. Vendors should decompose product offers to expose modular service bundles that buyers can finance separately.
-
Interoperability and systems integration are procurement differentiators — security agencies increasingly require devices to feed into centralized C2 and intelligence systems. Open‑API architectures and certified integrations are becoming non‑negotiable in competitive bids.
-
Supply chain resilience and cost containment — device production involves specialized components (detectors, high‑voltage generators). Nearshoring key subassemblies and establishing multi‑tier supplier relationships will blunt lead‑time spikes and protect bid competitiveness.
-
Regulatory arbitrage and new revenue channels — the formal recognition of mobile imaging service reimbursement in healthcare underscores how vendors can repurpose technology and operational workflows to access adjacent commercial markets.
Competitive landscape — how leading players position
The market remains fragmented: top three vendors represent roughly one quarter of total market revenues, indicating ample room for niche specialists and fast followers. Our competitive analysis focuses on five companies whose strategies exemplify the range of playbooks in the sector:
-
Vidisco Ltd (Israel) — Strength: established presence in digital X‑ray for law enforcement, military, customs and EOD; proven field reliability. Strategic opportunity: translate military heritage into commercial systems that lower operator training requirements and reduce time‑to‑deploy for civilian buyers.
-
Viken Detection (USA) — Strength: expertise in backscatter imaging and handheld solutions for border patrol and tactical operations. Strategic opportunity: combine sensor innovation with analytics and user experience design to win pilot programs that emphasize ease of use in constrained environments.
-
Teledyne ICM (France) — Strength: ultralight constant‑potential generators and digital scanners optimized for EOD and threat ID. Strategic opportunity: scale manufacturing partnerships and pursue certifications that simplify procurement for international agencies.
-
Scanna MSC (UK) — Strength: high‑performance scanners for mail, parcel and baggage screening. Strategic opportunity: leverage postal and logistics partnerships for volume channel penetration and expand software offerings to monetize analytics.
-
3DX‑RAY Ltd (UK) — Strength: breadth of portable inspection systems including handheld and cabinet models. Strategic opportunity: standardize modular platforms to reduce SKU complexity and accelerate service deployment.
For incumbents, the imperative is to move from single‑product vendors to systems providers that bundle hardware, field uptime guarantees, and analytics. For challengers, the path is rapid differentiation through lower TCO, superior user experience, or tightly integrated services that reduce buyer risk.
How to use this report to make decisions in 2026
-
Procurement officers: use our TCO templates to stress‑test bid comparisons beyond headline hardware prices — include training, downtime, software licenses and upgrade pathways.
-
Product leaders: prioritize development investments that compress deployment time and integrate analytics; consider product variants that enable subscription pricing and field servicing.
-
M&A and corporate development teams: target niche service providers, software analytics firms, or local manufacturing partners to accelerate market access without bearing full R&D cost.
-
Policy and compliance teams: monitor reimbursement and export control trends as they materially alter commercial prospects and go‑to‑market constraints; the 2026 HCPCS changes are a reminder that adjacent policy shifts can create new commercial channels.
Methodology and data robustness
PW Consulting’s market model synthesises primary interviews with procurement officials, operators, and vendors, triangulated with public tenders, company filings, and supply‑chain data. The historical series covers 2020–2025 with 2025 as the base year. Forecasts cover 2026–2032 and are expressed in USD Million. Our core forecast assumes a medium growth scenario, producing a 5.2% CAGR for 2026–2032; alternative downside and upside scenarios are included in the full workbook for client use.
Next steps — where to access the full intelligence
This brief is designed to demonstrate the strategic value of our analysis while preserving the core segmented data and vendor scorecards that drive procurement and investment decisions. Subscribers to the full report gain access to:
-
Complete segmentation (by region, product type, and application) with downloadable tables and pivotable financial models;
-
Vendor scorecards with weighted scoring across technical, commercial, and compliance dimensions;
-
Excel workbooks that let you re‑run scenarios with client‑specific assumptions.
Contact PW Consulting to request the full report package, schedule a briefing with our lead analyst, or commission a customized scenario run tailored to your organisation’s strategic questions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Portable X-Ray Equipment for Security Purposes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com