

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Railway Li‑ion Battery Market Poised for Rapid Expansion — 16.45% CAGR Projected Through 2032

Railway Li‑ion Battery Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive summary
As rail operators, OEMs and investors recalibrate deployment plans for decarbonisation and energy resilience, the Railway Li‑ion Battery Market is entering a phase of accelerated growth and strategic reconfiguration. Our PW Consulting market model — grounded in a 2025 base year and extending through 2032 — projects a sustained compound annual growth rate of 16.45% across the 2026–2032 forecast window. The market expands from a mid‑double‑digit USD Million base in 2025 to a substantially larger opportunity by 2032, driven by technology substitution, regulatory tightening, and an inflection of commercial battery‑electric rolling stock programs.
Railway Li-ion Battery Market
This brief summarises the report’s strategic value for corporate decision‑makers in 2026. It highlights the commercial levers, regulatory headwinds and supply‑chain fault lines that will decide winners and laggards — and it explains how our full report equips organisations to translate macro momentum into tactical roadmaps, while intentionally withholding detailed sub‑segment tables here to guide readers to the primary release for transaction‑grade intelligence.
Railway Li-ion Battery Market
Market trajectory and core macro drivers
Rail electrification choices, fleet renewal cycles and a wave of demonstrator-to-commercial rollouts are converging to create a multiyear growth runway for Li‑ion systems in rail traction, depot storage and onboard auxiliary power. Our historical analysis captures the 2020–2025 adoption curve and quantifies the acceleration drivers that underpin the forecast. The 16.45% CAGR reflects a market that is maturing beyond bespoke pilot systems to standardised product families and scalable manufacturing relationships.
Railway Li-ion Battery Market
- Regulatory momentum: Mandatory carbon footprint reporting and elevated recycling targets in the EU, along with tightened railway electronic equipment standards, are forcing producers and buyers to adopt traceable, certifiable battery solutions at pace.
- Technology economics: Rapid declines in LFP cell pricing and improved lifecycle metrics are shifting chemistry choices and system‑level trade‑offs, materially lowering total cost of ownership for battery‑equipped rolling stock.
- Commercial deployment: Recent commercial orders and entry‑into‑service announcements demonstrate a transition from pilots to revenue service, creating reference cases that reduce procurement risk and accelerate fleet adoption.
- Concentration dynamics: Market concentration is meaningful and rising; top vendors collectively account for a majority share of revenue, signalling an environment where strategic partnerships, scale and system integration capability are decisive.
Why this report matters to 2026 decision‑makers
For executives shaping procurement, product strategy, or capital allocation in 2026, timing is critical. The market is at an inflection where early leadership can capture locked‑in production slots and reference projects, while late movers face higher marginal deployment costs and longer qualification timelines. Our report is structured to support three immediate decision priorities:
- Supply‑chain resilience and sourcing strategy: Detailed supplier maps and risk heatmaps identify critical single‑source exposures and the implications of due diligence and third‑party verification requirements that became mandatory in 2025.
- Product architecture and chemistry selection: Scenario‑based TCO models compare lifecycle outcomes for alternative chemistries and packaging approaches under realistic duty cycles and regulatory cost assumptions.
- Commercial execution and partnership models: Contracting blueprints, integration risk matrices and recommended commercial terms help buyers and OEMs structure performance guarantees and warranties that align incentives across the value chain.
Actionable strategic recommendations for 2026
Our analysis translates market dynamics into a prioritized set of actions that executives should take in 2026, balancing near‑term wins with durable competitive positioning.
- Lock critical supply through tiered sourcing and long‑lead agreements. Given the pace of deployment, securing cell and module supply via a mix of contracted capacity and conditional call‑offs is the highest‑impact near‑term move.
- Standardise architecture to reduce qualification time. Operators and OEMs should converge on a limited set of platform architectures and interface standards to accelerate fleet integration and reduce lifecycle service costs.
- Invest in validated recycling and traceability pathways. Compliance with EU carbon‑reporting and recycling efficiency mandates is now table stakes; proactive investment in compliant reverse‑logistics and material recovery capabilities reduces regulatory and reputational risk.
- Pursue system‑level partnerships, not only component deals. The winners will be firms that offer validated system integration — combining cells, BMS, thermal management and service contracts — rather than commoditised cells alone.
- Design procurement to reflect performance risk. Fixed‑price procurement for new chemistries increases risk; we recommend performance‑based contracts with phased acceptance tied to clearly defined test regimes.
Competitive landscape — what to watch in 2026
The market features a mix of established industrial battery manufacturers, rail systems integrators and specialised energy storage firms. Key incumbents and their strategic postures are outlined below, with emphasis on their rail‑specific propositions.
- Saft Batteries (Levallois‑Perret, France) — Offers advanced lithium‑ion systems tailored for rail applications; strength lies in system engineering and railway certification experience that shortens qualification cycles for operators.
- GS Yuasa (Kyoto, Japan) — Longstanding traction battery capabilities and industrial scale manufacturing; positions itself as a vertically integrated supplier for motive power and heavy‑duty applications.
- Hoppecke Batteries (Brilon, Germany) — Focused on LFP‑based solutions for metros and depot storage, emphasising lifecycle and safety credentials aligned with European operator priorities.
- Končar – Electric Vehicles (Zagreb, Croatia) — Emerging as a commercial operator‑OEM with battery‑electric trains now in passenger service, illustrating the pathway from local projects to exportable product platforms.
- Leclanché (Yverdon‑les‑Bains, Switzerland) — Positioned around system‑level electrification and traction modules, with a focus on electrification retrofit programs.
- Toshiba Infrastructure Systems (Tokyo, Japan) — Offers integrated electronic and power supply subsystems, leveraging broad systems engineering experience in rail environments.
- Hitachi Rail (Tokyo, Japan) — Moving aggressively into tri‑mode hybrid trains and battery‑equipped fleets through partnerships and in‑house system integrations.
- AKASOL AG (Bruchsal, Germany) — LFP system specialist with emphasis on hybridisation and high‑performance modules for demanding duty cycles.
Recent market events underscore the competitive dynamics: commercial orders for battery‑equipped locomotives and intercity trains, supply contracts for next‑generation LFP packs, and the first passenger services on battery‑electric routes. These reference projects are compressing procurement risk and creating an innovation cascade among suppliers and integrators.
Operational risks and mitigation
Adoption of railway Li‑ion systems introduces a distinct risk set beyond conventional traction electrification. The report provides diagnostic frameworks and mitigation playbooks for the top operational exposures:
- Regulatory compliance risk — Addressed via mandatory lifecycle documentation, third‑party verification and alignment with the latest rail safety and electronic equipment standards.
- Supply‑chain and raw‑material volatility — Mitigated through diversified sourcing strategies, index‑linked procurement clauses and inventory buffering calibrated to fleet roll‑out schedules.
- Technical obsolescence and chemistry drift — Managed by modular system design, upgrade paths for battery management systems, and clear migration plans for cell chemistry transitions.
- End‑of‑life and recycling liabilities — Handled by embedding recycling obligations into procurement contracts and partnering with certified recyclers to meet rising recovery targets.
Report contents — what you get
The full PW Consulting Railway Li‑ion Battery Market report is designed as a playbook for 2026 execution. Key components include:
- Quantitative market model (2020–2032) with scenario sensitivity and TCO ladders for representative duty cycles.
- Supplier and technology landscape with product architecture comparisons, qualification timelines and supply‑chain risk scoring.
- Regulatory and standards matrix detailing compliance obligations and practical steps to readiness across major markets.
- Commercial contracting templates, warranty structures and performance test protocols tailored to rail procurement cycles.
- Case studies of recent commercial deployments and lessons learned from operator and OEM pilots transitioning to fleet service.
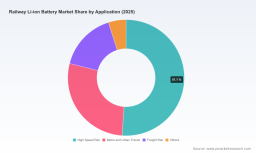
Consistent with the “trailer” approach, this briefing highlights the strategic thrusts and directionally important figures (market size trajectory and CAGR) but intentionally omits the granular regional and application splits and other transaction‑level tables that are included in the paid release. These withheld datasets are critical for procurement negotiations, M&A diligence and capital allocation models.
How to use this intelligence in 2026
Here are practical next steps for leaders using this analysis as a decision accelerator:
- Procurement teams — Use the report’s supplier risk heatmap to prioritise pre‑qualification and secure conditional offtake slots for cell and module supply within the next 6–12 months.
- Product and engineering teams — Adopt the platform standardisation recommendations and begin a 12‑month validation programme aligned with EN 50155:2026 requirements.
- Strategy and corporate development — Run the report’s scenario suite against your fleet renewal timelines to identify attractive M&A or JV targets that can close capability gaps within 18 months.
- Investor relations and finance — Use the market trajectory and concentration metrics to model growth assumptions and capital needs for battery‑enabled rolling stock financing rounds.
Methodology note and transparency
Our modelling combines bottom‑up demand forecasting tied to publicly announced fleet programs, rolling stock replacement cycles, and retrofit pipelines with top‑down adoption curves calibrated against historical market behaviour from 2020–2025. Supplier revenue shares and concentration metrics are built from a synthesis of public filings, procurement awards and proprietary interviews. The report documents assumptions and sensitivities to permit users to adapt the model to bespoke fleet or regulatory scenarios.
Call to action
Decisions made in 2026 will shape a company’s competitiveness through the decade. To access the detailed sub‑segment breakdowns, supplier scorecards, contract templates and the full quantitative model that underpin the strategic recommendations above, please consult the full PW Consulting Railway Li‑ion Battery Market report on our website. The depth required for procurement negotiation, operational implementation and capital allocation is contained within the core release — the essential next step for executives who want to turn this market momentum into durable advantage.
For detailed analysis of this topic, please visit the official page: Railway Li-ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com