

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts WiFi Home Router Market to Grow at a 6.8% CAGR in the 2026–2032 Forecast

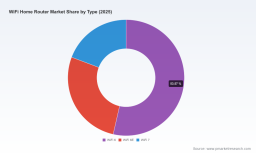
WiFi Home Router Market 2026: Strategic Imperatives for Executive Decision‑Making
Executive snapshot
PW Consulting’s latest WiFi Home Router Market research — anchored on a 2025 base year, a historical window from 2020–2025, and a forward forecast to 2032 — provides the practical market intelligence that senior leaders need to set confident strategies in 2026. The market has expanded steadily from the early 2020s and, after accelerating through the pandemic-driven device refresh cycle, is projected to continue growing at a compound annual growth rate (CAGR) of 6.8% through our forecast horizon. By the start of the forecast period demand momentum and technology upgrades converge to create a multi-year growth runway that both incumbents and newcomers must plan around.
WiFi Home Router Market
Why this report matters for 2026 decisions
Executives face a compressed horizon to make decisions that will determine competitive position by 2028–2030. This study is built to translate macro momentum into executable choices. It does three things for leaders:
WiFi Home Router Market
- It transforms headline growth into prioritized revenue plays — identifying where product investment, route-to-market shifts, and certification efforts will deliver the greatest return on invested capital.
- It models regulatory and supply‑chain contingencies so teams can convert uncertainty into tactical timelines for procurement, testing, and vendor qualification.
- It benchmarks competitive intensity and concentration to clarify when to defend, double down, or divest — with playbooks tailored to OEMs, channel partners, and strategic investors.
Market trajectory and what the numbers mean
Underpinning our narrative is a quantified market progression: the WiFi home router market expanded meaningfully through 2020–2025 and reached a substantive market size in the 2025 base year. Projected growth (6.8% CAGR) produces a substantially larger market by the mid‑2030s, reflecting continued consumer upgrades, faster broadband rollouts, and the migration to multi‑gig home architectures. Those macro figures are the foundation for scenario planning — from conservative replacement-driven demand to more aggressive adoption scenarios tied to WiFi 7 and multi-link consumer applications.
WiFi Home Router Market
For strategic planning in 2026, the implication is clear: the market is neither saturated nor nascent. It is a mature growth market where product differentiation, certification, and channel execution will determine share shifts rather than purely volume expansion. That dynamic favors firms that can combine product roadmaps with supply assurance and rapid compliance to evolving regulatory regimes.
Key dynamics reshaping the competitive field
- Technology upgrade cycles: Transition windows to new standards create retrofit and upsell opportunities. Early availability of robust multi-link, multi-gig-capable home routers yields premium ASPs and higher lifetime revenue per household, but only when paired with clear consumer value propositions and proven interoperability.
- Regulatory disruption: Recent regulatory actions have introduced near‑term restrictions that directly affect product eligibility for certain contract channels and government purchases. These rules introduce both compliance risk and competitive opportunity for vendors with certified supply chains and localized manufacturing footprints.
- Certification and independent validation: Third‑party certifications and lab verification are accelerating from “nice to have” to purchasing prerequisites in certain channels. This increases the cost of market entry but de‑risks the proposition for channel partners and end customers.
- Channel convergence: Retail, telco bundling, and app‑based subscription services are increasingly interwoven. Companies that control end‑user experience (through apps, mesh management, and value‑added security subscriptions) expand beyond device margins into annuity revenues.
- Consolidation and concentration: The market’s competitive concentration points to substantial share held by a small set of global vendors. This raises barriers for new entrants in mainstream retail channels but also creates niches for specialized propositions — portable routers, travel‑optimized devices, and privacy/security-focused products.
Regulatory and certification developments to act on now
2025–2026 saw a cluster of regulatory and certification events with direct operational impact. Independent testing firms have accelerated verification of next‑generation devices, while regulatory authorities have refined rules about foreign-manufactured equipment and the permitted use of consumer-grade routers in professional environments. In practice this means procurement teams and product planners must: secure validated certifications early, document manufacturing provenance in supplier contracts, and design product roadmaps that account for both certification timelines and conditional regulatory exemptions.
Competitive landscape: positioning and strategic moves
The market remains anchored by several global players, each with distinct strategic postures that should inform competitor response and partnership strategies.
- TP-Link — With a broad portfolio of mesh systems and mainstream routers, TP‑Link competes on scale, cost competitiveness, and retail reach. Their rapid product cadence makes them a price and feature benchmark in mass channels, and their strategy suggests that rivals should watch promotional cycles and retail shelf economics closely.
- NETGEAR — NETGEAR’s premium Nighthawk and Orbi lines target performance‑oriented consumers and multi‑gig households. Their focus on multi‑gig and advanced mesh positions them well for ISP bundling and high‑ARPU customers, prompting competitors to defend premium segments with demonstrable performance and service differentiation.
- ASUS — ASUS combines gamer and premium home networking credentials, leveraging high‑performance R&D to command premium pricing. Their play demonstrates the value of vertical specialization — especially when combined with lifestyle marketing and enthusiast communities.
- Cisco — While historically enterprise‑centric, Cisco’s presence in advanced home networking signals a bridge between consumer and prosumer/SMB segments. Their entry validates that professionalism and manageability are increasingly marketable in higher‑end home deployments.
- GL.iNet — As a niche player, GL.iNet highlights the opportunity in portable and travel‑optimized routers. These niche segments are defensive hedges for incumbents and attractive acquisition targets for companies seeking differentiation without competing on mass scale.
- Linksys, Eero, D‑Link — These established brands occupy important channel positions: Linksys and Eero on managed mesh and app‑driven experiences, D‑Link on value and international channels. Their varying strengths in software ecosystems and channel relationships create a complex matrix of partnership potential and competitive pressure.
Practical, actionable content in the report
The full PW Consulting study is intentionally operational. It is designed for product chiefs, commercial leaders, supply‑chain executives, and corporate development teams who need to move from insight to action. Deliverables include:
- — A validated market-sizing model and several forecast scenarios with sensitivities tied to adoption rates, ASP trajectories, and regulatory constraint timelines.
- — A regulatory playbook and supplier due‑diligence checklist aligned to recent certification and policy developments.
- — Competitive scorecards that evaluate product portfolios across performance, price, certification, and channel fit.
- — Go‑to‑market frameworks for monetizing mesh management, security subscriptions, and ISP bundling.
- — Tactical recommendations for procurement timing, inventory buffers, and manufacturing localization options to mitigate regulatory disruptions.
Note: This press briefing intentionally highlights the report’s strategic frameworks and macro projections. The full report contains the granular market splits, regional and application breakouts, and company‑level revenue estimates necessary for detailed planning — those datasets are available exclusively in the full release.
Scenario planning: three plays for 2026
- Defend and monetize: For market leaders, prioritize retention and ARPU growth via subscription services, stronger warranty and security bundles, and preferential ISP partnerships. Capitalize on certification status as a competitive moat for operator contracts that are sensitive to provenance and compliance.
- Scale selectively: For challengers, identify underserved niches (portable, travel, privacy-oriented households) and partner selectively with retail or telco channels to build volume without triggering head‑to‑head price wars. Use certification and targeted product differentiation to justify premium pricing.
- Acquire and integrate: For financial sponsors and strategic buyers, seek targets that close capability gaps (software for mesh management, security stack, localized manufacturing) rather than pure-volume bolt‑ons. The right acquisition accelerates compliance readiness and reduces time to revenue in regulated channels.
Immediate priorities for executive teams
- Accelerate certification pipelines and map regulatory timelines into product release calendars.
- Quantify channel sensitivity to provenance and certification to prioritize where to localize manufacturing or warehousing.
- Revisit pricing architectures to capture service monetization and to offset certification and supply‑chain costs.
- Run rapid scenario exercises (12–24 month) to test inventory and promotional levers against regulatory shocks.
Concluding perspective
The WiFi home router market in 2026 presents a pragmatic growth story: steady headline expansion coupled with concentrated competition and rising regulatory complexity. Winning in the next two to four years will depend less on raw volume assumptions and more on the discipline of certification, channel orchestration, and monetization of software and services. PW Consulting’s report equips leaders with the models, playbooks, and tactical guidance to convert the market’s positive trajectory into durable competitive advantage.
How to obtain the full study
This press release previews the strategic findings and implications. For the full dataset, granular regional and application splits, and company‑level financials and scorecards, please visit the PW Consulting research portal to download the complete WiFi Home Router Market report and accompanying decision tools.
For detailed analysis of this topic, please visit the official page: WiFi Home Router Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com