

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cement and Aggregate Market Poised for a 6.98% CAGR (2026–2032)

PW Consulting Releases Strategic Insight Brief: Cement and Aggregate Market Outlook — A Practical Guide for 2026 Decision-Making
Executive summary
PW Consulting today publishes a strategic industry brief that translates complex market dynamics into an operational playbook for executives, financiers, and planners active in the Cement and Aggregate Market. Anchored by an independent market model, the brief confirms a resilient mid‑single‑digit growth trajectory — a compound annual growth rate (CAGR) of 6.98% across the near‑term forecast — and projects the market to rise from USD 699.09 Million in the 2025 base year to USD 1,182.67 Million by 2032. For leaders preparing capital allocation, M&A, decarbonization roadmaps, or supply‑chain restructuring in 2026, the report converts macro direction into clear, prioritized actions.
Cement and Aggregate Market
Why this matters for 2026
-
Timing of capital and capacity decisions. With the market set to accelerate materially from its 2025 base, 2026 will be a hinge year for capacity investments and debottlenecking programs that must be sequenced around rising demand and input cost volatility.
Cement and Aggregate Market -
Decarbonization and regulation. Regulatory pressure and corporate net‑zero targets are reshaping cost and product strategies; 2026 will be the first year many programs move from planning to measurable capex and operational change.
Cement and Aggregate Market -
Fragmented competitive structure. Despite the presence of global majors, market concentration remains low (CR3 ~24.6%, CR5 ~26.2%), meaning local incumbents and agile new entrants can still capture disproportionate value with targeted investments.
Market trajectory: a numbers‑informed narrative (high level)
Our analysis models historical performance from 2020 through the 2025 base year and forecasts through 2032. The market is recovering from mid‑cycle pressures seen earlier in the decade and is evolving under the combined influence of infrastructure stimulus, urbanization trends, and product substitution dynamics. From USD 480.22 Million in 2020, the market expanded to USD 699.09 Million in 2025, and is forecast to reach USD 1,182.67 Million by 2032 under our central case — implying an average annual expansion consistent with the reported CAGR of 6.98% for the forecast horizon.
This trajectory is not uniform: the model identifies rhythm shifts driven by capacity additions, commodity cycles, and regulatory milestones. Key inflection points in the forecast align with announced plant upgrades and expected policy rollouts that will change the cost base for cement and aggregate producers.
Dynamics shaping near‑term strategic choices
-
Capacity and cost actions by major players. Recent corporate moves show a renewed emphasis on plant debottlenecking and incremental mill/clinker additions to secure regional supply positions and lower unit costs. These actions compress margins for higher‑cost competitors and create short windows of opportunity for pricing leverage in supply‑constrained micro‑markets.
-
Raw material and logistics intensity. Aggregate supply remains locally constrained in many markets; logistics costs and access to quarry reserves will be determinative for project economics and site selection.
-
Regulatory and feedstock dynamics. USGS and other agency data collected through 2025 highlight that cement and crushed stone shipments and consumption patterns are influenced by fuel mix shifts (e.g., changes in coal and natural gas generation) and by evolving blended‑cement norms — all of which feed through to synthetic gypsum availability and other by‑product inputs.
-
Fragmentation and consolidation potential. The industry’s low top‑three/top‑five concentration suggests scope for bolt‑on M&A focused on scale in priority corridors, build‑to‑fit greenfield projects, or roll‑ups of niche aggregate portfolios.
Competitive landscape: what the majors are signaling
The market’s institutional players — including multinational cement producers, large aggregates suppliers, and vertically integrated ready‑mix operations — are pursuing three overlapping strategies: (1) capacity optimization and debottlenecking, (2) product diversification (low‑carbon blends and recycled aggregates), and (3) downstream integration to lock in offtake.
-
LafargeHolcim Ltd. (Switzerland) — continuing investments in integrated plants and downstream ready‑mix capabilities to defend market share and reduce unit costs. Recent plant program activity highlights the effectiveness of adding incremental mill capacity to serve cross‑border demand corridors.
-
Heidelberg Materials (Germany; US operations) — focused on capacity expansions and low‑carbon product lines; the company’s operational posture evidences an intent to preserve margins through balanced CAPEX in both traditional and decarbonization‑oriented assets.
-
CEMEX and CRH — both pursuing blended cements and recycled aggregates as commercial differentiators while retaining broad geographic footprints and integrated supply chains.
-
Vulcan Materials and Martin Marietta — primary aggregate producers in the US that are optimizing quarry portfolios and logistics networks to capture increased public infrastructure spending.
-
Regional integrated players — including GCC, Buzzi Unicem, Taiheiyo, and CNBM — are expanding capacities or completing debottlenecking programs to enhance export optionality and domestic competitiveness.
Notable recent developments underline these themes: Holcim’s mid‑2025 expansions increased output capacity and improved cost position in North America, while multiple debottlenecking programs completed in 2025 by regional producers have added meaningful incremental capacity in targeted corridors. These moves will reshape short‑term supply dynamics and create new benchmarks for unit economics.
What PW Consulting’s report delivers (practical, actionable modules)
-
Strategic scenario sets. Three forward scenarios (Base, Accelerated Investment, and Constrained Supply) with sensitivity tables that translate demand swings, input‑cost shocks, and policy changes into P&L and IRR impacts for representative asset archetypes.
-
Investment prioritization matrix. A framework to rank greenfield, brownfield, and debottlenecking projects by payback, scalability, and regulatory risk — with decision criteria tailored for 2026 capex cycles.
-
M&A target profiles. High‑conviction acquisition archetypes and screening criteria (asset type, reserve life, logistics access, and carbon intensity) that identify where buyers can capture both scale and decarbonization optionality quickly.
-
Pricing and contract playbook. Practical contract design and pricing tactics that protect margins in volatile input environments and preserve market share in fragmented end‑markets.
-
Operational decarbonization pathway. A stepwise guide covering fuel switching, clinker substitution opportunities, and scope 1/2 accounting choices tied to plausible capex and opex implications.
-
Local market dashboards. Proprietary micro‑market views with demand drivers, competitor footprints, and logistics pinch points. (Note: detailed micro‑market tables and regional split data are intentionally reserved for the full report to ensure subscribers obtain the full analytic value.)
How executives should apply the insight in 2026
-
Prioritize near‑term debottlenecking projects in corridors where pricing power can be rapidly enforced; use the report’s scenario outputs to stress‑test IRR under multiple cost regimes.
-
Lock first‑mover advantages on sustainable product lines by pairing modest capex in blending and recycled aggregate capability with clear commercial pilots — the report identifies high‑impact, low‑cost pilot designs.
-
Use the M&A archetypes to assemble bolt‑on plays that increase urban corridor density and reduce haul distances; our screening filters fast‑track target lists and diligence checklists.
-
Integrate regulatory and feedstock intelligence into procurement strategies — for example, anticipate changes in by‑product availability and design contingency for synthetic gypsum supply shocks described in public agency data.
-
Adopt the pricing playbook to protect margins during intermittent supply surges brought on by announced expansions among global majors.
Why PW Consulting — methodological clarity and independent judgment
Our analysis blends proprietary shipment and price models with primary interviews across producers, large infrastructure contractors, and logistics providers conducted during 2025. We stress‑test assumptions against public agency data and integrate recent corporate announcements and capacity programs. The market model is transparent and auditable; subscribers receive scenario engines and a pack of decision templates to embed in board‑level debates.
Trailer: what we are not releasing here (and why you should download the report)
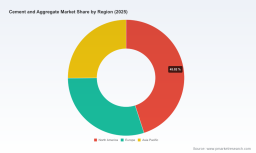
In keeping with the “trailer” principle, this brief presents high‑conviction findings and practical frameworks while deliberately withholding the granular segmentation tables and region/application‑level percentage breakdowns that underpin our micro‑market guidance. Those detailed splits — including the full regional, product‑type, and application allocations that drive localized strategy — are available exclusively in the full report and interactive dashboard. This approach preserves the value of our proprietary modeling and ensures subscribers get the actionable granularity necessary for project‑level decisions.
Next steps and access
For executive teams preparing 2026 capital plans, procurement roadmaps, or M&A pipelines, PW Consulting’s Cement and Aggregate Market report provides the tactical and financial tools required to move from analysis to execution. The full report includes the complete dataset, regional dashboards, scenario model, and a prioritized action checklist tailored to the 2026 operating year.
To request the full report and companion tools, or to arrange a briefing with PW Consulting’s sector lead, visit our official report page. Our team stands ready to translate the model outputs into customized decision packages for boards, investor committees, and executive leadership teams.
For detailed analysis of this topic, please visit the official page: Cement and Aggregate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com