

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
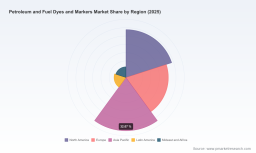
PW Consulting: Petroleum & Fuel Dyes Market to Reach USD 720.97 Million by 2032, Growing at a 4.08% CAGR — Asia Pacific Leads at USD 175M

Petroleum and Fuel Dyes and Markers Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting today releases a strategic preview of our latest market study on the global Petroleum and Fuel Dyes and Markers Market (base year 2025), designed to inform executive-level decisions in 2026. Built from a rigorous historical baseline (2020–2025) and forward-looking scenarios through 2032, the study combines hard market sizing with actionable tools for procurement, regulatory compliance, product development, and M&A. The global market grew from approximately USD 446.2 Million in 2020 to USD 545.7 Million in 2025 and is projected to expand to roughly USD 721.0 Million by 2032, representing a compound annual growth rate of about 4.08% over the forecast period. This release explains why that trajectory matters for leaders planning budgets, partnerships, and product strategies in 2026—while preserving the proprietary segment-level intelligence available in the full report.
Petroleum and Fuel Dyes and Markers Market
Why this matters for 2026 strategy
-
Compliance and fiscal risk have moved from occasional operational issues to strategic priorities. Shifts in regulatory regimes and the adoption of forensic markers have raised the cost of non-compliance and increased the strategic value of marker selection and supplier contracts.
Petroleum and Fuel Dyes and Markers Market -
Moderate but meaningful market growth (4.08% CAGR) and a market size approaching three-quarters of a billion USD by 2032 create a stable platform for targeted product investments, niche differentiation, and selective consolidation.
Petroleum and Fuel Dyes and Markers Market -
Market concentration metrics indicate a fragmented supplier base. With the top three suppliers accounting for under one-third of the market and the top five representing just over a third, there is room for technology leaders and private-equity-backed consolidation plays—particularly among differentiated forensic-marker providers and suppliers addressing tax-rebated fuel niches.
Dynamics shaping supplier and buyer choices
-
Regulatory acceleration: Recent regulatory moves have elevated specific marker chemistries from “best practice” to mandated solutions in some jurisdictions. For example, the selection of a particular molecular marker as a common fiscal marker for tax-rebated fuels in the European Union (implementation beginning in 2024) is already reshaping procurement specifications and compliance timelines for manufacturers, distributors, and downstream fuel users.
-
Raw material and cost pressure: Feedstock and specialty-chemical inputs—such as aromatic intermediates used in marker chemistries—remain a source of margin volatility. Historical evidence of petrochemical feedstock pricing demonstrates how upstream swings can compress supplier margins and shift the competitive landscape for dye and marker formulators.
-
Technology differentiation: The market is bifurcating between visible, economical dyes for grade identification and covert/forensic markers (including non-extractable near-infrared and molecular markers) intended for anti-fraud, traceability, and law-enforcement applications. Buyers increasingly value markers that are robust to adulteration, durable in storage and use, and compatible with analytical toolchains deployed by customs and fiscal authorities.
-
Supply-chain resilience and service: With many end-users sourcing across regions, manufacturers’ ability to provide technical support, analytical verification, and regulatory documentation has become a competitive differentiator.
What the PW Consulting report delivers (operationally focused)
Our proprietary report is designed as a toolkit for corporate decision-makers. It goes beyond high-level forecasts to provide execution-ready intelligence across the following components:
-
Market sizing and methodology: Transparent approach to historical reconstruction (2020–2025) and scenario-driven forecasts (2026–2032), including sensitivity testing around raw material and regulatory shock scenarios.
-
Regulatory tracker and implications matrix: Jurisdictional mapping of mandatory marking regimes, timelines for compliance, and penalty frameworks—translated into tactical procurement and certification checklists.
-
Supplier benchmarking and risk matrix: Comparative profiles of leading suppliers, capability maps (visible dyes vs. forensic markers vs. non-extractable NIR technologies), and contracting templates designed to mitigate supply disruption and intellectual property risk.
-
Technology deep dives: Performance, detectability, and extractability tradeoffs for the principal marker families, plus analytical workflows used by enforcement agencies and forensic laboratories.
-
Commercial playbooks: Go-to-market strategies for manufacturers (product-packaging, pricing levers, channel segmentation) and procurement playbooks for fuel distributors and government agencies looking to specify markers in tender documents.
-
Scenario and M&A opportunity assessment: Deal screens based on capability gaps, geographic footprint, and technological differentiation—backed by valuation sensitivities to regulatory adoption rates and raw-material price scenarios.
Competitive landscape — what to watch (strategic takeaways)
-
Innospec Inc. (United States): A well-established supplier of hydrocarbon-soluble dyes and a suite of marker products, including non-extractable near-infrared and Euromarker-based lines. Their product set and technical support footprint position them as a preferred supplier where performance under regulatory scrutiny is required. For buyers, Innospec’s breadth means fewer integration hurdles for multi-jurisdiction deployments; for competitors, it raises the bar on analytical validation and regulatory dossiers.
-
Dow Inc. (United States): Dow’s entries include molecular forensic markers and visible dyes marketed under several brand names. A notable strategic inflection is the selection of a Dow-associated marker chemistry as the EU common fiscal marker in recent policy moves—this highlights the power of aligning R&D investments with public-sector standardization processes. Dow’s scale and petrochemical feedstock integration also give it an advantage when raw-material cost inflation becomes a primary margin driver.
-
United Color Manufacturing, Inc. (United States): Positioned around economical liquid dyes and covert marker products, UCM serves customers needing cost-effective, standardized coloring across fuels. Their value proposition is operational simplicity and price competitiveness—attractive to distributors managing high volumes with thin margins.
-
John Hogg Technical Solutions (United Kingdom): A specialist with deep experience in tax-rebated fuel solutions and high-performance solvent-soluble dyes. Their focus on niche use cases and international petroleum applications makes them a go-to partner where bespoke formulations and regulatory liaison are necessary.
Taken together, these profiles illustrate a market where technology leadership and regulatory alignment can create durable advantage, but where fragmentation creates acquisition opportunities for players that can scale verification services and laboratory networks.
How executives should use this intelligence in 2026
-
Procurement and sourcing: Lock in multi-year supply agreements that include analytical-verification clauses and price-adjustment mechanics tied to raw-material indices. Use the report’s supplier risk matrix to prioritize dual-sourcing for high-risk lines.
-
Compliance and certification: Update compliance roadmaps to reflect the growing importance of forensic verification and ensure tender specifications include marker detectability thresholds aligned with enforcement laboratory capabilities.
-
Product strategy: Allocate R&D resources between low-cost visible dyes and higher-margin forensic markers, guided by expected regulatory mandates in target markets and the report’s scenario analysis for adoption curves.
-
M&A and partnerships: Use the report’s deal screens to identify targets that provide complementary lab services, geographic access to high-growth fuel markets, or proprietary non-extractable marker chemistries.
-
Operational resilience: Incorporate feedstock price scenarios into margin models and maintain contingency inventories for key intermediate chemicals to avoid production interruptions during sudden price spikes.
PW Consulting’s deliverables and client engagement options
-
Executive briefings and workshops tailored to procurement, compliance, and R&D teams.
-
Custom scenario modeling based on client-specific exposure to jurisdictions, marker types, and contract durations.
-
Data-room services: access to the report’s underlying time-series, methodology, and anonymized supplier evaluation matrices for buyers conducting tenders or investors conducting diligence.
Our preview aims to arm leaders with the strategic frame necessary to act decisively in 2026. For companies that must allocate R&D budgets, negotiate long-term supply contracts, or evaluate acquisition targets, the difference between proactive and reactive strategies will be determined by the quality of market intelligence—particularly in a market where regulatory mandates and marker technologies can rapidly change the economics of compliance.
Next steps — where to find the complete intelligence
This article highlights the strategic contours of the Petroleum and Fuel Dyes and Markers Market and summarizes PHASES of risk and opportunity. The full PW Consulting report contains proprietary segment-level breakdowns, regional and application splits, supplier scorecards, and model-ready datasets that we intentionally reserve for report subscribers and licensed clients. Access to that granular intelligence is available through our report page and consulting engagement channels; it is the definitive asset for teams needing to convert the market’s 4.08% CAGR and near-term regulatory inflection points into executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Petroleum and Fuel Dyes and Markers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com