

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Amorphous Polyolefins Market to Reach USD 762.1 Million by 2032, Growing at a 4.85% CAGR

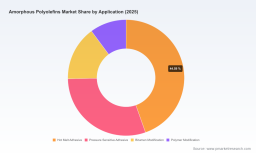
Amorphous Polyolefins Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive summary
As manufacturers, investors, and procurement leaders prepare budgets and capital plans for 2026, understanding the trajectory of the amorphous polyolefins (APO) market has moved from advantageous to essential. PW Consulting’s latest market research — anchored to a 2025 base year and projecting through 2032 — shows a resilient APO market expanding at a compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. Our proprietary modelling projects the global APO market to advance from USD 551.8 million in 2025 to approximately USD 762.1 million by 2032, with near-term inflection points driven by regulatory recyclability requirements, bio-based product adoption, and episodic raw-material shocks.
Amorphous Polyolefins Market
Why 2026 is a strategic inflection point
-
Regulatory alignment and commercial pressure converge. With tighter recyclability targets in major markets and incentives for bio-based formulations gaining momentum, 2026 will be the year where product portfolios are scrutinized against compliance and circularity outcomes.
Amorphous Polyolefins Market -
Supply-side volatility is elevated. Propylene price fluctuations and regional refinery dynamics are producing materially asymmetric cost exposures across supply chains, influencing margin sustainability and creating short-duration arbitrage opportunities.
Amorphous Polyolefins Market -
Competitive repositioning is underway. Leading producers are increasing capacity, launching differentiated grades, and promoting “sustainable” credentials — moves that will reshape procurement tactics and partnership strategies in 2026.
Market trajectory — what the numbers mean for decisions
PW Consulting’s topline projection presents a clear, actionable signal: the APO market is not static commodity plumbing; it is a growing, innovation-driven segment. The market expanded through 2020–2025, reached USD 551.8 million in our 2025 base year, and is forecast to continue expanding to roughly USD 762.1 million by 2032 at a 4.85% CAGR. For 2026, this trajectory implies continued demand tailwinds for adhesive, sealant, polymer-modification, and packaging applications, even as raw-material-induced cost cycles add execution risk.
For resource allocation, the implication is twofold: (1) near-term investments in formulation and recycling-friendly grades will capture elevated return on sales as customers prioritize mono-material and recyclable solutions; (2) mid-term capacity and logistics investments should incorporate scenarios for disrupted propylene supply and regional feedstock variance.
What PW Consulting’s report delivers — practical content for 2026 execution
-
Scenario-driven supply-demand modelling: granular supply curves, stress-tested under raw-material spikes and capacity outages to quantify EBITDA sensitivity and fill-rate risk.
-
Price and margin playbooks: hedging approaches tailored to APO value chains, with sensitivity matrices for propylene and co-monomer swings.
-
Product strategy frameworks: specification matrices mapping APO chemistries to recyclability compliance thresholds, adhesive performance tiers, and low-odor/hygiene segmentation.
-
Go-to-market roadmaps: commercial segmentation, channel optimization, and partner archetypes for license, tolling, and co-development agreements.
-
Operational guidance: CAPEX phasing, plant utilization scenarios, and feedstock sourcing pathways to reduce single-point vulnerabilities.
-
M&A and JV playbooks: target screening criteria, valuation yardsticks, and integration checklists for bolt-on capacity or technology acquisitions.
-
Sustainability pathways: lifecycle assessment templates, recycled-content strategies, and policy-compliance templates for major jurisdictions.
Note: This release illustrates the depth of the report and its practical utility while reserving detailed regional and application-level splits for subscribers seeking the full dataset and bespoke advisory packages.
Competitive landscape — positioning and recent moves
The APO competitive set remains moderately fragmented: the top three players account for under a quarter of market share, and the top five just over 30% — an environment that favors both large-integrated chemical players and specialized, agile producers.
-
Evonik Industries AG (Essen, Germany) continues to leverage scale and sustainability branding. Recent commissioning of a new APO line and public showcases of eCO sustainable grades underscore a dual strategy: defend industrial adhesives and accelerate recyclable, low-solvent solutions for packaging.
-
Eastman Chemical Company (Kingsport, Tennessee) is targeting formulation-led differentiation. Their 2025 introduction of a butene-free APO optimized for sanitation and packaging reflects a product innovation play to capture hygiene and food-contact demand with low-odor profiles.
-
REXtac LLC (Odessa, Texas) and other reactor-specialists remain important innovation engines, offering proprietary catalyst-enabled grades that allow formulators to tune melt viscosity and tack profiles for high-performance hot-melt applications.
-
Asian producers (examples include Liaoyang Liaohua Qida and Hangzhou Hangao) are scaling capacity and introducing bio-based options, combining cost competitiveness with sustainability narratives — a combination that accelerates adoption in regional markets.
-
Major polymer majors (Mitsui Chemicals, Dow Inc., LyondellBasell) remain strategic suppliers, integrating APO grades into broader adhesive and packaging solutions, and enabling global distribution reach.
These shifts mean that 2026 commercial plans should treat product differentiation and supply security as co-equal priorities. Tactical alliances, licensing of reactor technologies, or off-take agreements with diversified feedstock clauses will be decisive tools.
Raw material and regulatory dynamics to factor into 2026 plans
-
Propylene volatility: Recent months show meaningful regional price movement. Short-term spikes and historical supply disruptions (including a pronounced 2023 surge) materially reduced regional output and shifted trade flows. Procurement teams must embed index-linked contracts, alternative sourcing routes, and feedstock flexibility into supplier scorecards.
-
Recyclability mandates: Policy steps that require higher recyclability thresholds for packaging are accelerating mono-polymer design adoption. For APO producers and formulators, this magnifies the premium for grades that enable recyclable PP-based laminates and coatings.
-
Incentives for bio-based formulations: In several major markets, fiscal and regulatory incentives make bio-based APOs commercially attractive to brand-owners seeking recycled- or renewable-content claims, altering long-term procurement preferences.
Strategic playbook for 2026 choices
-
Prioritize product and portfolio triage. Rapidly assess product families against recyclability, VOC profiles, and cost-to-serve. De-list or re-formulate low-performing SKUs to redirect R&D and marketing budgets.
-
Secure feedstock optionality. Negotiate hybrid supply contracts (spot/term), invest in alternative monomer chemistries where feasible, and evaluate tolling arrangements to buffer refinery-driven shocks.
-
Deploy targeted capacity investments. Use PW Consulting’s scenario tool to time brownfield expansions or debottlenecking versus greenfield commitments, minimizing stranded-asset risk.
-
Accelerate sustainability claims with verifiable pathways. Invest in LCA and third-party verification now to be “go-to” suppliers for brand-owners constrained by packaging recyclability rules.
-
Consider non-dilutive routes to market. Licensing, contract manufacturing, and JV models can expand footprint without full CAPEX exposure while testing regional demand elasticity.
-
Prepare M&A playbooks. The moderate concentration and divergent strategies among incumbents indicate attractive bolt-on opportunities for technology, regional footprint, or bio-feedstock access.
Why PW Consulting’s report is a 2026 decision-maker’s tool
Our research blends quantitative forecasting (market sizing from 2020 historicals through a 2032 projection), supplier-level benchmarking, commercial playbooks, and scenario modelling that explicitly integrates raw-material shocks and regulatory ramps. The report is structured to convert insight into executable initiatives: CAPEX timelines, procurement clauses, innovation roadmaps, and M&A scorecards — each calibrated to the 2026 decision cycle.
Getting the full picture
This release signals the depth and practical orientation of PW Consulting’s APO market analysis while intentionally reserving the granular regional and application-level tables and proprietary segmentation models for subscribers and advisory clients. For organizations that need to translate the market’s 4.85% CAGR and multi-year growth trajectory into capital budgets, supplier strategies, and product roadmaps for 2026, the full report and our tailored advisory engagement are available via the PW Consulting portal.
Methodology and credibility
Our assessment combines bottom-up plant- and SKU-level supply analysis, independent propylene and co-monomer price scenarios, and end-market demand modelling across adhesives, sealants, packaging, and polymer modification applications. We triangulate company disclosures, trade flows, and SBU-level capacity moves to generate a defensible forward view — and we explicitly stress-test outcomes under the kinds of propylene and logistics dislocations that have reshaped APO availability in recent years.
Closing perspective
Entering 2026, APO market participants face a classic strategic trade-off: act early to capture premium positions rooted in recyclability and bio-based credentials, or defend on cost and scale as propylene volatility persists. Our analysis suggests that the highest-return path combines selective product investment, feedstock diversification, and commercial structures that transfer or share raw-material risk. PW Consulting’s market report offers the playbook and tools to operationalize that path — with the detailed regional and segment analytics accessible to subscribers and clients ready to make the pivotal decisions that 2026 demands.
For detailed analysis of this topic, please visit the official page: Amorphous Polyolefins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com