

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Cleaners & Degreasers Market Set to Expand at a 4.8% CAGR During 2026–2032

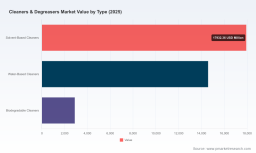
Cleaners & Degreasers Market — 2026 Strategic Preview
Executive overview
PW Consulting’s latest Cleaners & Degreasers Market report (base year 2025, forecast 2026–2032) frames the sector at a pivotal juncture. The market — valued at roughly USD 35.4 billion in 2025 — is projected to expand at a compound annual growth rate (CAGR) of 4.8% through 2032, reaching an estimated USD 48.6 billion by the end of the forecast window. That trajectory reflects steady demand from industrial maintenance, manufacturing operations, and institutional cleaning, tempered by rising regulatory, sustainability and supply‑chain pressures that are reshaping product portfolios and capital plans.
Cleaners & Degreasers Market
This preview surfaces the strategic actions corporate leaders should prioritize in 2026. It showcases the analytical depth of our full report — market sizing, scenario analysis, regulatory impact models and competitive playbooks — while deliberately withholding the granular segment-by-segment tables and proprietary breakouts that are available in the paid study.
Cleaners & Degreasers Market
Why the 2026 planning cycle is different
-
Regulatory tightening is moving from future risk to immediate capex reality. New and updated standards for product ecolabelling and industrial equipment (including updated GreenSeal standards and proposed regulatory rulemaking in key jurisdictions) are converting product formulation choices into near-term investment decisions for manufacturers and end-users alike.
Cleaners & Degreasers Market -
Certification-driven demand is accelerating procurement shift. Buyers in food & beverage, healthcare and institutional facilities increasingly require third‑party credentials; the expanded NSF listings and GreenSeal clarifications that appeared in 2025–2026 materially change qualification timelines and supplier shortlists.
-
Sustainability is altering the product ladder. The transition to lower-toxicity chemistries, higher‑performance aqueous systems and validated biodegradable options is progressing, but not uniformly. Firms that marry credible environmental credentials with operational performance will capture premium distribution channels.
-
Market structure is moderately concentrated. The top tier of suppliers controls a meaningful share of commercial volumes, but specialist regional players and industrial formulators preserve room for targeted growth strategies and bolt‑on acquisitions.
What this means for corporate strategy in 2026
For executive teams preparing budgets and strategic initiatives, the implications are immediate and actionable. Below are the priority moves that separate leaders from followers:
-
Portfolio triage: Reallocate R&D and commercial spend toward formulations that reduce regulatory and end‑customer friction (e.g., formulations positioned for current ecolabels and NSF categories). Prioritize projects where product redevelopment yields both compliance and differentiated performance.
-
Regulatory readiness investment: Treat equipment and monitoring demands (especially for vapor degreasers and solvent management) as capital projects. Our scenario models show that compliance-driven CAPEX and operating-cost shifts are among the largest near-term margin pressures.
-
Channel and go‑to‑market redesign: Differentiate routes-to-market by customer segment (industrial maintenance, institutional cleaning, parts cleaning) and create certification-driven selling motions for food, pharma and regulated manufacturing customers.
-
M&A and capability buys: Seek tuck-in acquisitions that add validated ecolabels, proprietary aqueous/biodegradable chemistries, or distribution access to regulated end markets. Smaller specialist suppliers provide high-value access to niche channel partners and technical competencies.
-
Supply-chain resilience: Rebalance procurement strategies for solvent and surfactant inputs, establish dual sourcing, and accelerate inventory optimization to manage volatility in feedstock prices and regulatory-induced supply constraints.
Competitive landscape — strategic read of core players
The full report contains deep company profiles; here we summarize the strategic posture of prominent suppliers to orient decision-makers.
-
Brulin (Indianapolis, Indiana, USA) — Strengths lie in industrial degreasers spanning vapor and aqueous technologies and in eco‑credentialing (Green Seal Certified®; ISO 9001:2015 & ISO 14001:2015). Recent product catalog updates in mid‑2026 emphasize super‑concentrated eco options, signaling a deliberate push to capture sustainability-driven specification wins.
-
Zep, Inc. (Atlanta, Georgia, USA) — A broad institutional and industrial portfolio with deep channel penetration in maintenance and foodservice applications. Zep’s distribution footprint and solution breadth make it a logical partner for large facility chains seeking one‑stop procurement simplicity.
-
Simple Green (United States) — Recognized for concentrated degreasers and NSF‑listed formulations across multiple categories. Recent confirmations of NSF listings expand Simple Green's credibility in food and industrial spaces and reduce buyer qualification friction.
-
4‑U Products / Metalube (Corona, California, USA) — Niche player specializing in non‑toxic, biodegradable formulations for industrial and aerospace applications. Their value lies in targeted technical solutions and environmental positioning that appeal to high‑specification users.
-
DeltaGreen Products Inc. (Gardena, California, USA) — Focuses on non‑hazardous, heavy-duty concentrates suitable for heavy‑soiling applications; a practical choice for firms seeking performance without hazardous material handling complexity.
-
ATCO International (United States) — Supplier of high-performance industrial degreasers designed for heavy soils and carbon deposits; plays to customers valuing performance certainty in demanding environments.
-
Romaine Companies (United States) — Bulk commercial and industrial supplier with strengths in large‑volume facility contracts and distribution relationships across manufacturing and commercial services.
-
SC Product Group (Dallas, Texas, USA) — Produces performance cleaning chemistries for professional applications, with an emphasis on recreational and specialty industrial markets.
Collectively, these firms illustrate a market where brand, channel scale, and validation credentials (NSF, GreenSeal, ISO) materially influence procurement decisions. The top three firms capture a sizable portion of total volumes, and the top five approach half of the market, creating a competitive dynamic where partnerships and certification capabilities are as important as price.
Regulatory and certification dynamics to factor into 2026 plans
-
GreenSeal standard updates (including GS‑34 and GS‑37 revisions) have clarified product testing and labeling expectations; companies should update claim substantiation workflows now, not later.
-
Regional ecolabelling authorities (e.g., Nordic Ecolabelling) have increased life‑cycle disclosure expectations, putting pressure on formulators to capture upstream scope‑3 data and to rethink solvent choices.
-
U.S. EPA rule proposals affecting vapor degreasers and continuous exposure monitoring introduce new equipment and operational costs for certain solvent‑based technologies. Our regulatory-cost models show measurable margin pressure for non-compliant installations.
-
Certifications such as NSF categories broaden product access to regulated segments; firms securing these listings in 2025–2026 are already shortening procurement cycles and accelerating qualification wins.
What the PW Consulting report delivers — the practical toolkit
The full Cleaners & Degreasers Market report is built for decision-makers who need executable outputs, not just charts. Key deliverables include:
-
Validated market sizing and growth scenarios (base year 2025; forecast 2026–2032) with sensitivity analysis tied to regulatory and feedstock shocks.
-
Regulatory impact matrices that translate standards and proposed rules into CAPEX, OPEX and product‑qualification timelines by technology family.
-
Competitive playbooks and customer shortlists for channel expansion, featuring go‑to‑market motions by end‑use and procurement profile.
-
M&A screening tools and a candidate list framework to identify high‑value tuck‑ins (technical chemistries, certification assets, channel access).
-
Operational checklists for product reformulation programs, including supplier sourcing templates, regulatory submission timelines and certification costing.
-
Scenario-based pricing and margin models that allow CFOs to stress-test portfolios under differing regulatory and raw‑material cost environments.
How to use this intelligence in 90, 180 and 365 days
-
90 days: Complete product‑portfolio triage and fast‑track certification for highest-potential SKUs; begin supplier audit for critical solvent and surfactant inputs.
-
180 days: Implement channel segmentation pilot, align sales incentives to certified SKUs, and begin minor plant upgrades required for projected equipment monitoring rules.
-
365 days: Execute one strategic inorganic acquisition or joint venture to secure technical capability or new channel access; roll out systemic compliance and sustainability reporting frameworks.
Final perspective — a trailer, not the full film
This briefing captures the decisive issues that will shape 2026 strategy for manufacturers, distributors and large end‑users in the Cleaners & Degreasers market. It demonstrates the analytical lines of the full study — which contains the granular segmentations, regional and application breakouts, company financials and the proprietary models necessary to size opportunities and prioritize investments.
PW Consulting’s report is intentionally designed to be decision‑centric: data you can act on, templates you can deploy, and scenario outputs you can plug into board‑level investment debates. For procurement officers, product strategists, M&A teams and regulatory leads preparing 2026 budgets, the full report provides the missing leg of insight between market narrative and executable plan.
Next steps
To access the full market breakdowns, detailed company profiles, and our executable tools and models, please visit PW Consulting’s Cleaners & Degreasers Market report page or contact your PW Consulting account lead. The complete report contains all segment and regional line items, primary‑research transcripts, and downloadable scenario models that underpin the strategic guidance summarized here.
For detailed analysis of this topic, please visit the official page: Cleaners & Degreasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com