

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Sterilization Equipment Market Set to Expand at 8.15% CAGR (2026–2032), PW Consulting Finds

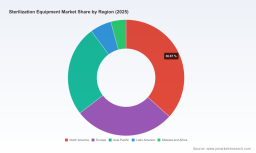
Sterilization Equipment Market 2026: Strategic Imperatives for Corporate Leadership
Executive snapshot
As healthcare systems and regulated industries accelerate investment in sterile processing, the global sterilization equipment market has entered a sustained growth phase. PW Consulting’s new market study (base year 2025) documents a clear trajectory: the market more than doubled in the early 2020s and reached a base-year size of USD 17.7 Billion in 2025. Our forecast modelling projects continued expansion through 2032, with a compound annual growth rate of approximately 8.15% across the 2026–2032 horizon, reflecting robust demand for both traditional steam-based systems and an increasingly diverse set of low-temperature, radiation, and monitoring solutions.
Sterilization Equipment Market
Why this matters for 2026 decision-makers
-
Regulatory inflection points are creating windows of both risk and opportunity. Recent regulatory actions — from the FDA’s evolving recognition of sterilization consensus standards to U.S. environmental agencies proposing revisions to emissions rules for ethylene oxide — materially alter compliance costs and timelines for operators and vendors alike.
Sterilization Equipment Market -
Reimbursement and internal funding structures are changing. The introduction of dedicated CPT codes for sterile processing services has begun to reframe how hospitals and health systems justify CapEx and operating investments, elevating automation and digital monitoring as economically defensible projects.
Sterilization Equipment Market -
Capital allocation priorities are shifting toward automation and integration. Purchasers are prioritizing systems that reduce manual labor, improve throughput, and deliver auditable digital records — an urgent consideration for procurement and engineering teams planning 2026 and 2027 capital cycles.
-
Market structure favors focused specialization and service-enabled models. With measured concentration at the top—indicative of a market where the largest three and five vendors do not yet dominate—there is ample room for regional specialists, technology innovators, and service integrators to scale.
What PW Consulting’s report delivers — practical intelligence for immediate action
-
High-confidence market forecasts and scenario-led sensitivity analysis for 2026–2032, including baseline, regulatory-stress, and accelerated-adoption scenarios mapped to procurement cycles.
-
Regulatory risk matrix keyed to sterilization modalities and facility types — measuring compliance cost probabilities, expected timelines, and mitigation levers for each scenario.
-
CapEx and ROI playbooks for health systems and commercial sterilizers that compare automation, digital monitoring, and lifecycle service models—built for CFOs to present to boards.
-
Actionable vendor and technology scorecards that evaluate product portfolios (steam, low-temperature, radiation, EO), service capability, digital readiness, and aftermarket economics—designed to accelerate vendor selection and negotiation.
-
M&A and partnership opportunity maps, identifying targets by capability gaps, regional strength, and service footprints—supported by commercial due-diligence templates.
-
Operational integration guides for sterile processing departments: CIP considerations, washer-sterilizer interoperability, automated loading, and digital traceability requirements for high-throughput facilities.
-
Executive dashboards and KPI sets for monitoring program performance: throughput per sterilizer, turnaround time, cost per cycle, regulatory compliance score, and spare-parts availability.
Competitive landscape — qualitative signals and strategic implications
The market is characterized by a mix of global OEMs with full-suite sterile processing offerings, specialists focused on particular modalities, and regionally strong equipment manufacturers and integrators. Key players profiled in our study include Getinge, STERIS (including Cantel business lines), Advanced Sterilization Products (ASP), 3M, Tuttnauer, MMM Group, Andersen Sterilizers, Steelco, and Shinva. While the largest suppliers bring scale and integrated sterile reprocessing solutions, many mid-sized and regional vendors retain competitive advantages in price, service responsiveness, and localized regulatory know-how.
-
Getinge — A leader in hospital-focused solutions, Getinge’s suite of steam sterilizers, washer-disinfectors, and automated sterile reprocessing systems positions the company to capture hospital automation budgets and integrated sterile workflow projects.
-
STERIS Corporation (and Cantel) — With a broad product mix spanning steam, hydrogen peroxide gas plasma, and low-temperature systems, STERIS is well-suited to offer end-to-end sterile processing platforms and aftermarket services that align with health systems consolidating vendors.
-
Advanced Sterilization Products (ASP) — Specialists in hydrogen peroxide gas plasma technologies, ASP’s regulatory progress (notably an FDA-cleared pathway for a sterilizable duodenoscope in 2025) signals a tactical advantage for heat-sensitive device sterilization markets and underscores the clinical adoption curve for advanced low-temperature methods.
-
3M — With a portfolio covering biological and chemical indicators, ethylene oxide sterilizers and monitoring systems, 3M’s strengths lie in process validation and monitoring—capabilities that will be increasingly valuable as operators face tighter emissions and traceability requirements.
-
Tuttnauer, MMM Group, Steelco, Shinva — These manufacturers maintain strong positions in autoclaves, washer-disinfectors, automated loading, and hospital-lab equipment, often winning on total cost of ownership and service networks in their respective regions.
-
Andersen Sterilizers — Focused on ethylene oxide solutions and flexible chamber technologies, vendors in this space are particularly sensitive to evolving emissions regulations and therefore represent both regulatory risk and potential acquisition targets for firms seeking to broaden modality coverage.
Recent regulatory and market developments shaping 2026 strategy
-
April 2025 — ASP announced the U.S. launch and FDA clearance of a sterilizable duodenoscope using its STERRAD platform; a milestone that accelerates acceptance of low-temperature sterilization for complex, heat-sensitive instruments.
-
November 2025 — The FDA published transitional enforcement guidance addressing ethylene oxide sterilization facility changes for high-risk devices, creating temporary compliance pathways that providers must understand to avoid service disruption.
-
January–March 2026 — Regulatory clarifications: the FDA recognized ISO 22441:2022 for vaporized hydrogen peroxide as an established category, reducing certain premarket burdens, while the U.S. EPA proposed revisions to NESHAP for ethylene oxide facilities that may rescind prior requirements for smaller operators; both actions recalibrate risk for sterilizers and commercial facilities.
-
Industry financing and operational dynamics — New CPT codes effective 2025 supporting sterile processing services and ongoing capital reallocation toward automation are already influencing purchase cycles and vendor contracting strategies.
Strategic playbook: five priorities for 2026
-
1. Regulatory-first procurement: Integrate regulatory scenario modelling into RFPs. Shortlist suppliers who demonstrate compliance agility for both emissions and device-specific sterilization standards; require traceability and validation toolchains as part of procurement contracts.
-
2. Prioritize automation ROI: When capital is constrained, prioritize investments that reduce FTE dependence in sterile processing—automated loading, washer-sterilizer integration, and digital cycle management tend to deliver faster economic payback under the new reimbursement landscape.
-
3. Define service-based commercial models: Move from equipment purchase toward lifecycle and uptime contracts. Vendors and health systems that adopt outcome-based or managed service models can de-risk operations and stabilize margins.
-
4. Targeted M&A and partnerships: For suppliers seeking rapid capability expansion, prioritize bolt-on acquisitions that close modality gaps (e.g., low-temperature sterilization, biological monitoring) or expand aftermarket service footprints in strategic regions.
-
5. Operational readiness and skills: Invest in sterile processing workforce reskilling and digital adoption pilots. Establish cross-functional rapid-response teams (clinical engineering, infection control, procurement, and compliance) to accelerate deployment and governance.
How PW Consulting helps executives convert insight into decisions
Our report is designed for leaders who must make decisive 2026 choices under uncertainty: hospital CFOs allocating CapEx, device OEMs planning sterilization strategies, industrial sterilization facility operators navigating emissions rules, and private-equity sponsors evaluating buy-and-build opportunities. We combine econometric market models, regulatory scenario tools, vendor benchmarking, and executable playbooks so you can move from diagnosis to implementation within a single planning cycle.
Next steps — access deeper intelligence
This release intentionally presents high-level growth, trajectory and strategic guidance while withholding the granular regional, type and application splits contained in the full dataset. Those detailed tables—regional and application breakdowns, vendor scorecards with quantitative metrics, and the financial models used to stress-test scenarios—are available in the complete PW Consulting Sterilization Equipment Market report and online decision toolkit. To accelerate your 2026 planning, contact our Sterilization Equipment practice to arrange a tailored briefing, model walkthrough, or a workshop that maps the findings directly to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Sterilization Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com