

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polyurethane Dispersions Market to Rise from USD 283.0 Million in Base Year 2025 to USD 473.31 Million by 2032 at a 7.7% CAGR — Asia‑Pacific, Anionic Systems and Paints & Coatings to Dominate in Fragmented Market (CR3: 25%)

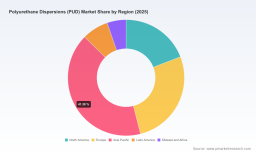
Polyurethane Dispersions (PUD) Market Report 2026 — Strategic Briefing for Executive Decision-Making
PW Consulting today releases a strategic briefing extracted from our forthcoming Polyurethane Dispersions (PUD) Market report. Designed as a decision-ready preview for CEOs, product leaders, procurement heads, and corporate development teams, this briefing synthesizes the macro trajectory, competitive posture, and operational playbooks that will shape PUD-related choices in 2026. The full report contains proprietary segmentation, granular country- and application-level forecasts, and transaction-ready valuation templates; this preview highlights what to act on now while reserving the detailed slices for subscribers and clients.
Polyurethane Dispersions (PUD) Market
Market at a glance: growth, scale and near-term inflection
After a measured recovery from the early-2020s disruption, the global PUD market has accelerated into a clear growth phase. Our base-year inventory shows the market expanding from approximately USD 196.4 Million in 2020 to USD 283.0 Million in 2025. Momentum carries into the forecast horizon: PW Consulting projects the market will grow at a compound annual growth rate (CAGR) of 7.7% over 2026–2032, reaching a projected USD 473.31 Million by 2032. In absolute terms, the market is expected to pass roughly USD 301.3 Million in 2026 and continue to scale as regulatory, technology, and supply-side dynamics converge.
Polyurethane Dispersions (PUD) Market
Two immediate strategic implications flow from this trajectory: first, product and capacity investments made in 2026 must assume continued demand growth rather than short-term cyclical recovery; second, competitive advantage will accrue to players that simultaneously manage raw-material exposure and accelerate waterborne, low-VOC innovations.
Polyurethane Dispersions (PUD) Market
Why 2026 is a leverage year for corporate strategy
- Regulatory acceleration creates windows of opportunity. Tightening VOC and air-quality standards in major markets are shifting formulators and specifiers to waterborne PUD solutions. Regulatory triggers—ranging from U.S. EPA NESHAP updates to EU VOC directives and China’s Blue Sky initiatives—are compressing adoption timelines for many downstream sectors.
- Raw-material volatility forces trade-offs. Manufacturers face material-cost pressure and input risk. Notably, recent TDI pricing adjustments and logistics-driven cost increases have altered margin dynamics for solvent and semi-solvent systems, accelerating reformulation programs toward waterborne chemistries.
- Fragmented supplier landscape invites consolidation and partnerships. Market concentration remains low by industrial-chemical standards, creating room for targeted M&A, JV capacity plays, and co-development agreements that can secure downstream channels or raw-material positions.
Competitive landscape — who matters and why
The PUD competitive field mixes global chemical majors, regional integrators, and specialized formulators. Leading global players such as BASF SE, Covestro AG, and The Dow Chemical Company play distinct roles—combining broad polyurethanes portfolios, channel reach, and applied R&D into modular PUD platforms. Specialty suppliers such as Lubrizol and Mitsui Chemicals focus on differentiated formulations (e.g., high-solids dispersions, synthetic leather grades), while regional champions—including Wanhua and other Asia-based producers—are executing capacity expansions and aggressive commercial penetration in construction and coatings.
- BASF SE — leveraging broad raw-material integration and applied coatings know-how; recent moves include capacity expansion and a near‑zero SVOC product launch to capture interior coatings demand.
- Covestro AG — focused on waterborne technologies for synthetic leather and automotive applications, with product portfolios tailored to high-performance end uses.
- The Dow Chemical Company — retains strengths in industrial-scale supply and multi-application formulations suited to coatings and adhesives markets.
- Lubrizol Corporation — drives innovation in high-solids dispersions for wood finishes and OEM coatings, seeking application-specific premium positioning.
- Wanhua Chemical Group — executing regional capacity additions, with an emphasis on price-competitive waterborne offerings for construction and coatings.
- Mitsui Chemicals, Alberdingk Boley, Stahl, Hauthaway, Chase — represent the specialist cohort supplying tailored dispersions for leather, textile, and architectural niches; collectively they are attractive partners for co-development and market extension.
Recent corporate actions underscore the strategic priorities of 2026: BASF’s production expansion and low-SVOC product launch (early 2026) reflect a two-pronged approach of capacity and regulatory-driven innovation; Mitsui’s capacity ramp in 2025 and Lubrizol’s new high-solids Sancure line position them to win specification changes in wood and OEM channels. These moves confirm that the next wave of share gains will be won by firms combining supply security with application-led differentiation.
Market structure and concentration: implications for strategy
PUD is relatively fragmented by global-share metrics (CR3 and CR5 concentration levels remain low), which has multiple implications for strategists: margins are more contestable, price leadership is achievable via scale or specialization, and bolt-on M&A can meaningfully shift national or application-specific share. For potential acquirers, the landscape favors focused roll-ups in specific application verticals—leather finishing, textile, or high-performance wood coatings—where technical lock-in creates defensible economics.
Operational and commercial playbooks for 2026
PW Consulting’s fieldwork and client engagements distill four practical playbooks that leaders should adopt in 2026:
- Procurement hedging and supplier dual-sourcing. Implement dynamic hedges for TDI and polyol exposure; establish alternate supply lines in adjacent geographies to mitigate transport and regulatory interruptions.
- Fast-follower product platforms. Develop near-zero-SVOC and high-solids formulations that map to OEM and architectural specifications, fast-tracked through pilot scale and customer co-testing programs.
- Value-based commercial segmentation. Move from price-per-kilo selling to outcome-based contracts (e.g., lower lifecycle VOC compliance costs, reduced application time, improved durability) to capture higher margins.
- Selective capacity and asset plays. Prioritize modular capacity investments that can be repurposed across dispersions types and applications to maintain optionality as demand patterns evolve.
Risk matrix — regulatory, raw materials and demand shifts
Key downside scenarios to model in 2026 decision frameworks:
- Accelerated raw-material inflation. Unexpected TDI or polyol supply shocks could compress margins and force price escalations; contracts and pass-through mechanisms must be stress-tested.
- Regulatory tightening with phased enforcement. While regulation incentivizes PUD adoption, uneven enforcement across jurisdictions creates patchwork demand; go-to-market plans must be locally adaptable.
- Technology substitution. Emergence of alternative binders or bio-based chemistries could shift specification windows—monitor early adopters and pilot programs closely.
What’s in the full PW Consulting report (operationally actionable)
The full report provides the datasets and executable tools that teams will need to convert strategy into measurable outcomes. Highlights include:
- Proprietary historical and forecast market model (2020–2032) with downloadable scenarios and sensitivity inputs calibrated at national and application levels.
- Supplier scorecards and factory-level capacity maps, including utilization assumptions and build-out timelines.
- Raw-material price-impact models that translate TDI/polyol scenarios into PUD margin outcomes under different pass-through regimes.
- Commercial playbooks for OEM engagement, specification-change case studies, and partner-selection matrices for co-development.
- M&A and partnership valuation frameworks geared to fragmented chemical markets, plus a shortlist of transaction targets and strategic buy/sell triggers.
- Regulatory risk maps and compliance timelines by major jurisdiction tied to practical reformulation checklists.
To preserve competitive integrity in this executive preview, granular segmentation numbers (regional and application shares, product-type breakdowns, and company-specific revenue shares) have been reserved for the full report and client data packs. These items contain the proprietary intelligence required for negotiation and transaction execution.
Recommended next steps for 2026 planning
- Immediate (0–3 months): Run scenario stress-tests for raw-material inflation and VOC-driven demand shifts; prioritize product SKUs for accelerated reformulation pilots.
- Near-term (3–9 months): Secure conditional supply agreements and evaluate modular capacity investments; initiate customer co-development agreements in target end-markets.
- Medium-term (9–18 months): Execute go-to-market segmentation pilots, implement outcome-based pricing trials, and explore bolt-on acquisitions or JVs in underpenetrated regions.
How PW Consulting supports your 2026 agenda
Our advisory work pairs the full PUD market model with hands-on transaction support, supplier negotiations, and commercialization roadmaps. Clients receive the granular data needed to underwrite investments, a tactical playbook to accelerate specification wins, and deal-level valuation templates adapted to this fragmented market structure. If your 2026 plan involves capacity, M&A, or a shift toward low-VOC PUD platforms, PW Consulting’s full market report and bespoke advisory services will convert market intelligence into executable strategy.
To access the complete dataset, country- and application-level forecasts, and proprietary company profiles (including revenue fingerprints, margins, and asset maps), visit our report page or contact PW Consulting’s industry practice for an executive briefing and sample model inputs.
For detailed analysis of this topic, please visit the official page: Polyurethane Dispersions (PUD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com