

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Synchronous Condenser Market to Reach USD 0.95 Billion by 2032 at a 4.6% CAGR (2026–2032)

PW Consulting: Synchronous Condenser Market — Strategic Intelligence Brief for 2026 Decision-Makers
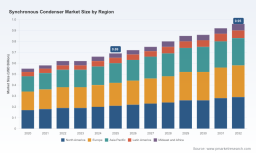
PW Consulting today publishes a strategic intelligence brief accompanying our full Synchronous Condenser Market report (base year 2025, forecast period 2026–2032). The report consolidates five years of historical performance (2020–2025) and forward-looking analysis to inform capital allocation, procurement, M&A, and grid-modernization strategies in the critical decade ahead. At the macro level, the market has expanded from roughly USD 0.55 Billion in 2020 to USD 0.69 Billion in 2025 and is projected to reach approximately USD 0.95 Billion by 2032 — a steady trajectory consistent with a compound annual growth rate (CAGR) of about 4.6% through the forecast horizon.
Synchronous Condenser Market
Why this report matters for 2026 strategic decisions
-
Timing and scale: Power system operators, utilities, and industrial end-users are operating against narrow windows to add inertia, short-circuit strength and reactive power capability as variable renewables scale rapidly. Decisions taken in 2026 about procurement models, retrofit versus new-build, and supplier selection will determine project economics and operational resilience over the next decade.
Synchronous Condenser Market -
Regulatory inflection points: European and North American grid codes, alongside regional reliability standards, increasingly formalize requirements for reactive capability and verified generator response. These regulatory signals are converting technical needs into procurement requirements and CAPEX commitments; integrating these mandates into commercial models is central to any 2026 investment case.
Synchronous Condenser Market -
Technology and execution evolution: Advances in modularisation, integrated flywheel systems, and experimental high‑temperature superconducting (HTS) machines are shifting project-level trade-offs between capex, O&M, footprint and delivery time. Organizations deciding on pilot deployments, retrofit pathways or technology bets in 2026 must weigh near-term deliverability against medium-term efficiency gains.
-
Competitive dynamics: The vendor landscape is characterized by a mix of global OEMs, regionally specialized suppliers and service-led entrants. Market concentration metrics indicate room for both established players and focused challengers to capture aftermarket and retrofit revenue pools; this creates multiple pathways for strategic partnerships, carve-outs and bolt-on acquisitions.
What PW Consulting’s report delivers — pragmatic, transaction-ready outputs
-
Comprehensive market sizing and scenarios: Up-to-date historical series (2020–2025) and three-tier forecast scenarios (base, accelerated energy‑transition, and delayed deployment). These scenarios quantify exposure to regulatory and renewable deployment variability without disclosing client-sensitive segmentation minutiae in this brief.
-
Procurement and project execution playbooks: Standardised tender templates, risk allocation matrices, and milestone-driven gantt models tailored to new installations, conversion/repurposing of retired generators, and modular fast-track builds.
-
Cost and value engineering toolkits: CAPEX and OPEX benchmarking, life‑cycle cost modelling, and sensitivity modules that let organizations stress-test price inflation, labour constraints and commodity shocks at the plant level.
-
Supply‑chain risk heat map: Component concentration, long-lead item tracking and alternative sourcing pathways for transformers, excitation systems, cooling technology and rare materials for advanced superconducting prototypes.
-
Vendor scorecards and negotiation playbooks: Qualitative and quantitative profiles of major vendors, delivery performance indicators, and contract clauses to protect buyers from scope creep and schedule slippage.
-
Commercial and investment cases: Project-level IRR/payback templates, service-revenue models for aftermarket and retrofit contracts, and playbooks for monetizing inertia and ancillary services where market designs permit.
-
Implementation timelines and prioritized action plans: Tactical 90‑day, 6‑month and 18‑month checklists aligned to procurement cycles and regulatory milestones to accelerate value capture.
Market dynamics shaping strategy
The market’s 4.6% CAGR reflects the confluence of technical necessity and commercial opportunity. As thermal synchronous generation retires, system operators are compensating with dedicated synchronous condensers to preserve frequency stability, manage voltage profiles and provide short‑circuit strength. That technical imperative is amplified by grid codes and reliability standards that now specify reactive capability and generator verification procedures.
Technology innovation is creating new strategic trade-offs. Integrated flywheel designs are being delivered at scale, enabling higher inertia in more compact footprints and supporting faster deployment timelines. Concurrently, early-stage HTS development promises lower mass and potentially higher efficiency, which—if commercialised—could alter LCOE-equivalent calculations for large-scale deployments during the latter half of the forecast period.
Execution models are also evolving. Asset repurposing and modular packages reduce delivery cycles and up-front capital needs, unlocking an attractive route for utilities seeking rapid grid strengthening without large greenfield builds. These approaches materially affect procurement strategy: the choice between turnkey OEM supply, conversion/repurposing contractors and hybrid contracting models will be a central determinant of both cost and schedule outcomes in 2026.
Competitive landscape — leading players and recent market movements
The competitive field features global engineering and power equipment majors alongside regional specialists. PW Consulting’s full report includes deep vendor profiles; below we summarise strategic positions and recent moves that should inform 2026 engagement strategies:
-
Siemens Energy (Berlin): A leading supplier of synchronous condensers and grid-strengthening solutions, active in multi‑unit deployments in renewable zones. Recent contract wins underline a focus on large-scale grid support projects.
-
ABB (Zurich): Positioned around turnkey synchronous condenser systems with integrated inertia solutions such as flywheels and prefabricated eHouse deployments—an approach that shortens site assembly time for utility clients.
-
Eaton (Dublin): Accelerating work on conversions and repurposing of decommissioned assets for grid stability, with notable projects demonstrating the feasibility of asset repurposing as a lower‑cost pathway.
-
Ansaldo Energia (Genoa), Mitsubishi Electric Power Products (Tewksbury), WEG (Brazil), ANDRITZ (Vienna), BHEL (New Delhi) and GE Vernova (Boston): Each offers differentiated packages—from modular and air-cooled systems to high‑capacity MVAr machines—creating options for buyers across project typologies.
Recent, market-significant developments include multi‑unit supply contracts, delivery of integrated flywheel fleets, and major orders for large MVAr condensers in utility grids—signals that demand is moving from pilot projects into repeatable procurement patterns. PW Consulting’s market concentration metrics indicate a marketplace where top-tier vendors capture a meaningful but not dominant share, leaving openings for focused technology specialists and regional integrators.
Actionable recommendations for executives in 2026
-
Prioritise near-term retrofit pipelines: Speed-to-service matters. For operators facing immediate grid stability constraints, modular and conversion options frequently outperform greenfield timelines on an economic basis.
-
Lock flexible supply contracts: Negotiate options and staged deliveries for long‑lead components. Include performance-based milestones and penalty structures to protect project schedules.
-
Pilot advanced technologies selectively: Allocate capital to HTS and integrated flywheel pilots where regulatory frameworks support ancillary service monetisation; avoid wholesale technology switches until field data matures.
-
Translate regulatory requirements into procurement specs: Convert code-level reactive and inertia requirements into measurable contract parameters—response times, verified reactive capability and short‑circuit contribution—so tenders are unambiguous and enforceable.
-
Build aftermarket and service propositions: Given the lifecycle nature of synchronous condensers, companies that combine supply with long‑term O&M and retrofit services can capture disproportionate lifetime value.
How to access the full intelligence suite
This brief is a strategic summary designed to orient executive decision-making for 2026. PW Consulting’s full Synchronous Condenser Market report contains the complete data tables, interactive financial models, supplier scorecards, detailed scenario outputs and transaction playbooks that underpin the recommendations above. The full dataset includes proprietary segmentation, region- and application-level analysis, and downloadable Excel modelling tools that support transaction diligence and capital planning.
For procurement leads, strategy teams and investors preparing 2026 programs, the full report is an operational resource: it translates market dynamics into executable actions and quantified investment cases. To obtain the complete report and supporting tools, please visit PW Consulting’s report page or contact our industry team to schedule a briefing and model walk-through.
PW Consulting’s Synchronous Condenser Market report equips decision-makers with the market context, execution playbooks and vendor intelligence needed to convert technical necessity into strategic advantage. In a market where regulatory deadlines and renewable build-outs set the tempo, the actions you take this year will define grid resilience and commercial outcomes for the decade ahead.
For detailed analysis of this topic, please visit the official page: Synchronous Condenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com