

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Special Epoxy Resin for Wind Power Blades Market to Reach USD 2,030 Million by 2032 at 6.0% CAGR — Asia‑Pacific Leads with USD 448.09M

Special Epoxy Resin for Wind Power Blades Market: Strategic Imperatives for 2026 Decision-Making
Executive summary
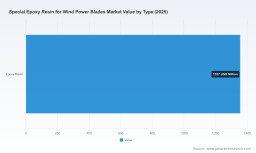
PW Consulting’s Special Epoxy Resin for Wind Power Blades Market study (base year 2025) consolidates a seven-year historical view (2020–2025) with a forward-looking forecast through 2032. The market has expanded from roughly USD 1.0 billion in 2020 to about USD 1.36 billion in 2025 and is projected to grow to approximately USD 2.03 billion by 2032, representing a compound annual growth rate (CAGR) of 6.0% across the 2026–2032 forecast window. Our analysis combines demand-side dynamics from accelerating wind-turbine build programs, shifting blade architectures, and regulatory drivers with supply-side shifts including capacity additions, raw-material cycles, and consolidation among specialty resin suppliers.
Special Epoxy Resin for Wind Power Blades Market
Why this report matters for 2026 strategy
2026 is shaping up as a decision inflection point for suppliers, OEMs, composites fabricators, financial sponsors, and national procurement agencies. The market’s steady mid-single-digit CAGR masks structural changes that will determine winners and losers: larger, higher-performance blades for both onshore and offshore deployments; pressure to lower lifecycle costs and carbon footprint; and the acceleration of capacity projects across liquid epoxy production. For leaders contemplating capital allocation, partnership structures, or product roadmaps in 2026, our report converts macro direction into practical, actionable options.
Special Epoxy Resin for Wind Power Blades Market
What the report delivers — practical, operational intelligence
- Robust market sizing and validated growth scenarios: Our base-case and alternate scenarios quantify upside and downside paths to 2032, driven by turbine size growth, offshore deployment rates, and regulatory support frameworks.
- Supply-chain and capacity analysis: A detailed map of resin feedstocks, conversion steps, and announced capacity expansions—together with a probabilistic view of which projects become operational by 2026–2027 and the resulting implications for pricing and spot availability.
- Technology roadmaps and materials selection guidance: Comparative evaluation of epoxy systems (including cure kinetics, Tg performance, toughness, and processability) aligned to blade manufacturing methods and cycle-time economics.
- Commercial playbooks: Sourcing strategies, hedging recommendations for key feedstocks, and negotiation tactics tailored to blade-makers and resin suppliers under varying market tightness scenarios.
- M&A and partnership target lists: High-priority profiles and valuation sensitivities for potential bolt-ons or JV partners that accelerate capability capture in resin chemistry, processing know-how, or regional footprint.
- Regulatory and circularity assessment: The report operationalizes relevant policy initiatives—permitting timelines, recycling pilots, and extended producer responsibility regimes—into compliance checklists and capex planning inputs.
- Decision-support assets: Financial models, supplier scorecards, and a scenario dashboard that can be adapted into 2026 budgeting and strategic review cycles.
Competitive landscape — who matters and why
The market demonstrates moderate concentration: the top three suppliers account for roughly 45.5% of the market, while the top five reach about 68.2%. This structure creates both opportunity and risk for challengers and incumbents.
Special Epoxy Resin for Wind Power Blades Market
- BASF SE (Ludwigshafen, Germany — https://www.basf.com/global/en): Renowned for its integrated epoxy systems and coating solutions, BASF targets blade toughness and process efficiency. In 2025 BASF announced a partnership to co-develop high-performance systems aimed at balancing mechanical performance with manufacturability—an instructive signal that R&D-led commercial alliances will accelerate time-to-market for next-generation resin systems.
- Hexion (Columbus, Ohio — https://www.hexion.com/): Hexion’s strategic positioning emphasizes formulations that enable longer, stronger blades. Their mid-2025 sustainability commitments underscore the growing premium for products that simultaneously extend blade life and reduce cradle-to-grave emissions—criteria increasingly embedded into procurement tenders.
- Olin Corporation (Chesterfield, Missouri — https://olin.com/): With a focus on formulated epoxy solutions, Olin is a core participant in innovation consortia aiming to close the circularity loop for blades. Collaborative projects that develop recyclable end-of-life pathways are likely to influence buyer preferences within regulatory regimes that prize reuse and remanufacturing.
- Dow Inc. (Midland, Michigan — https://www.dow.com/): Dow’s recent integration moves—expanding its epoxy franchise through strategic acquisitions—are creating a more vertically integrated supply model that seeks to shorten lead times and provide co-engineered solutions for large-scale blade programs.
- Solvay S.A. (Brussels — https://www.solvay.com/en/): Solvay brings high-performance polymer know-how focused on specialty composites. Its capability set is attractive where performance and environmental durability are prioritized, such as in harsh offshore environments.
- Gurit Holding AG (Baar, Switzerland — https://www.gurit.com/): As a supplier of composite material systems, Gurit plays a critical role in translating resin chemistries into manufacturable blade components—especially for manufacturers pursuing optimized laminate architecture and reduced cure cycles.
Recent industry developments and regulatory context
- Partnerships and consolidation continue to reshape competitive dynamics. Notable examples include BASF’s 2025 co-development agreement to enhance toughness and Dow’s 2024 acquisition to broaden its resin portfolio. These moves exemplify a twin-track strategy: proprietary product differentiation alongside scale-driven supply assurance.
- Policy and circularity initiatives are material. Collaborative research—such as the CETEC project working on recovering base components from epoxy composites—signals a forthcoming shift where recyclability and end-of-life solutions become procurement criteria, not just R&D curiosities.
- Demand drivers are clear: macro investments in offshore wind (endorsed by multi-hundred-billion-euro commitments over multi-decade horizons) will underpin growth in large-format resin demand. At the same time, announced capacity expansions in liquid epoxy production suggest meaningful supply-side response; our work models a scenario where roughly half of announced expansion projects become operational in the 2026–2027 window, materially influencing price dynamics.
Strategic implications for 2026
For executives preparing budgets, partnerships, or R&D milestones in 2026, we highlight five priority pathways:
- Secure feedstock and conversion capacity proactively. Given the timing of announced expansions, early contracting and dual-sourcing strategies will mitigate spot exposure during ramp cycles.
- Differentiate on manufacturability, not just performance. Suppliers that can demonstrate faster cure cycles and lower processing energy will win share as blade manufacturers pursue throughput and carbon targets.
- Invest in circularity pilots now. Participation in collaborative recycling programs can reduce long-term input risk and offer a commercial advantage in markets where lifecycle credentials are procurement criteria.
- Pursue selective M&A and partnerships. Acquisitions that add formulation depth or regional capacity create defensible positions; partnerships with universities and institutes accelerate commercialization of next-gen chemistries.
- Align commercial terms with lifecycle value. Consider moving from unit-price negotiations to value-based contracts that reward longer-life blades and lower total lifecycle cost—especially for offshore projects where TCO matters most.
How PW Consulting can support your 2026 planning
Our report is built to be operational within board cycles and procurement QBRs. We provide customized scenario stress-tests, supplier shortlists, negotiation playbooks, and technical due-diligence templates that clients can deploy immediately. For corporates evaluating capital allocation between resin capacity and composite manufacturing, we offer bespoke valuation models that incorporate policy risk, feedstock price volatility, and recyclability premiums.
Access the intelligence
This news release highlights the strategic contours and decision levers driving the Special Epoxy Resin for Wind Power Blades market through 2032. PW Consulting’s full report contains the granular segmentations, supply-by-region and application breakdowns, and the proprietary financial models that empower 2026 decision-making. To preserve the commercial utility of these insights for clients, detailed subsegment tables and supplier scorecards are available only in the full report and datasheets.
For access to the full report, tailored briefings, and to discuss a 2026-ready execution plan, please contact PW Consulting. The decisions made during 2026 will shape portfolio resilience throughout the decade—our work equips leaders to make those choices with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Special Epoxy Resin for Wind Power Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com