

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Therapeutic Nuclear Medicines Market Poised for 3.85% CAGR Through 2032

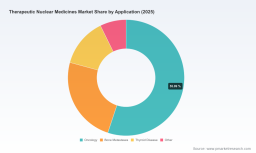
Therapeutic Nuclear Medicines Market 2026: Strategic Directions from PW Consulting’s New Market Report
Executive summary
Therapeutic nuclear medicine has moved from niche specialty to a structurally important segment within oncology and targeted therapies. PW Consulting’s new market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — shows a market that has expanded steadily and is expected to continue growing at a compound annual growth rate (CAGR) of 3.85%. Measured in USD Million, the market size increased meaningfully from the early 2020s and reached a notable midpoint in our base year (2025), with projections pointing to further upside by 2032.
Therapeutic Nuclear Medicines Market
This briefing summarizes the report’s strategic value for corporate decision-makers in 2026: it synthesizes the drivers and constraints shaping near-term commercialization, outlines operational and investment imperatives, and sketches practical actions executive teams should prioritize. In keeping with the “preview” objective, we illustrate the depth of our analysis without disclosing the granular segment-level figures reserved for subscribers to the full report.
Therapeutic Nuclear Medicines Market
Market trajectory: what the headline numbers mean for strategy
From 2020 through our base year of 2025, the therapeutic nuclear medicines market recorded steady expansion as novel approvals, indication expansions, and growing clinical adoption pushed revenues higher. Our model — denominated in USD Million — maps this progression and projects the market forward through 2032 under a calibrated set of assumptions. With a 3.85% CAGR across the forecast window, the market is neither hyper-explosive nor stagnant: it is maturing. That maturity brings both advantages (predictable reimbursement trajectories, clearer regulatory pathways) and commercial challenges (intensifying competition, pressure on pricing and margins).
Therapeutic Nuclear Medicines Market
For 2026 decision cycles, the key takeaway is this: the market is transitioning from opportunity capture to share capture. Early movers that secured clinical evidence and supply-chain capacity now face competitive entries and label expansions that redistribute value. The strategic question for leadership teams is how to defend or extend control of high-value indications while building flexible operations to capture incremental growth across the forecast period.
Competitive landscape — strategic implications
-
Market concentration and what it implies. The therapeutic nuclear medicines market exhibits meaningful concentration among the top companies. Our CR3 and CR5 metrics signal that a handful of established firms command a dominant share of commercialized assets and distribution channels. For incumbents, this concentration supports bargaining power with payers and providers; for challengers, it raises the bar for entry, underscoring the need for differentiated clinical data or partnership-led access strategies.
-
Profiles and recent competitive movements. Our report includes deep profiles of leaders whose strategic choices are shaping the market:
- Novartis AG — has solidified its franchise with therapeutic radioligand products and, in 2025, secured indication expansions that broaden earlier-line use. Those label changes materially affect patient flow and payer negotiations.
- Bayer AG — remains a strategic anchor in symptomatic bone metastases applications, with an established commercial footprint and specialist relationships in oncology networks.
- Lantheus Holdings — combines marketed niche products with moves toward generic and biosimilar equivalents, an approach that can compress prices in commoditizing segments while opening volume opportunities.
Additionally, late-stage entrants and clinical-stage innovators have advanced regulatory milestones in 2025–2026, including accepted NDAs and first-in-human dosing for targeted alpha therapies. These developments are signposts for competition in the second half of the decade: incumbents must defend label breadth while preparing for technologic and therapeutic-mode competition.
Regulation, reimbursement and their practical effects
Regulatory decisions in 2025–2026 materially re-shaped adoption curves. Several approvals and indication expansions broadened earlier-line use in oncology, and the FDA’s actions to accept new NDAs have accelerated the timeline for competitive launches. For commercial and market-access teams, the strategic impact is threefold:
- Reimbursement dynamics shift rapidly after label-expansion events: payer policy updates can convert previously marginal indications into reimbursable treatments, but they also invite tighter utilization management.
- Regulatory momentum increases the importance of health economics and outcomes research (HEOR). Demonstrating value versus alternative systemic therapies is now a precondition for favourable coverage.
- Regulatory acceptance of new candidates shortens the window where first-mover clinical data deliver a durable advantage; thus, lifecycle strategies must accelerate evidence-generation and real-world outcomes capture.
Technology and clinical trends to watch
Therapeutic nuclear medicines are differentiated by radionuclide type and delivery modality. The market is dynamically balancing three technical vectors: established beta-emitting radiopharmaceuticals, growing alpha-emitter programs that promise higher potency with different toxicity profiles, and isotope-based brachytherapy approaches for localized disease control. Each vector demands distinct manufacturing, dosimetry, and clinical-support capabilities — factors that materially influence cost-to-serve and adoption speed.
From a strategic planning standpoint in 2026, firms should prioritize platforms that: (a) align with scalable isotope supply, (b) accommodate accelerated evidence generation (including registries and pragmatic trials), and (c) integrate with oncology care pathways to minimize friction in adoption.
Operational and supply-chain realities
Operational constraints remain one of the most tangible barriers to growth. Manufacturing capacity, non-carrier-added radionuclide availability, specialized logistics (cold chain and radiological handling), and the limited number of treatment centers with nuclear-medicine expertise create chokepoints. Our report maps these bottlenecks and offers practical mitigation measures, including supply diversification, capital investment models for on-site or regional production, and hub-and-spoke distribution designs.
Investment risk and scenario planning
Investment decisions in 2026 must be stress-tested against three scenarios that our model operationalizes:
- Base case: Moderate, steady growth aligned with current CAGR assumptions, driven by label expansions and incremental adoption in defined oncology indications.
- Upside case: Accelerated uptake following favorable payer policies, breakthrough clinical readouts for alpha emitters, and scalable manufacturing investments that reduce unit costs.
- Downside case: Price compression from generic entrants and/or slower-than-expected reimbursement updates that depress volumes and margins.
Each scenario in the full report is accompanied by actionable KPIs and a decision-tree that translates clinical- and regulatory-events into predefined corporate responses — a tool designed for quick use in board-level strategic reviews.
Practical takeaways: a 2026 playbook for executives
- Prioritize evidence generation: invest in HEOR early and design real-world studies that align with payer endpoints to accelerate coverage decisions post-approval.
- Secure flexible supply: negotiate multi-source agreements for critical isotopes and consider partnerships for regional production to reduce single-point failure risk.
- Differentiate commercially: focus on service models (patient navigation, dosimetry support, site training) as a source of defensible value beyond molecule-level competition.
- Pursue strategic M&A and alliances selectively: target capabilities that shorten time-to-market (manufacturing, distribution) or broaden clinical breadth (complementary targeting ligands or alpha platforms).
- Embed scenario-based governance: create trigger-linked budgets and go/no-go gates tied to regulatory milestones and payer policy shifts.
- Elevate cross-functional readiness: align clinical, regulatory, supply-chain, and market-access teams to execute pre-launch and post-launch activities seamlessly.
What’s in the full PW Consulting report (practical content highlights)
The full report contains a comprehensive, operationally focused toolkit designed for decision-makers preparing 2026 strategies. Key deliverables include:
- A calibrated market model (2020–2032) with downloadable datasets and scenario toggles;
- Regulatory and reimbursement trackers that map recent approvals/expansions and anticipated milestones;
- Company dossiers and comparative benchmarking for leading incumbents and emerging entrants;
- A supply-chain risk matrix with mitigation playbooks and supplier prioritization frameworks;
- Go-to-market templates for hospital-network access, pricing strategy playbooks, and HEOR study designs;
- Deal and pipeline tracker covering clinical-stage assets, NDA filings accepted, and first-in-human dosing events.
These materials are engineered for immediate application in 2026 planning cycles: financial modeling spreadsheets, prioritized capability investments, and a 90-day launch-readiness checklist are included to accelerate execution.
Conclusion — why 2026 matters
As therapeutic nuclear medicine moves into a more mature growth phase, 2026 will be a pivot year. Regulatory expansions and new entrants observed through 2025–2026 are reordering competitive dynamics; market concentration metrics indicate both the power and vulnerability of incumbency; and operational bottlenecks will determine who captures scaled commercial value.
For executive teams, the prescription is clear: move beyond product-level strategy to orchestra cross-functional capabilities that convert regulatory wins into durable market share. PW Consulting’s report provides the evidence base, scenario tools, and operational playbooks to make those choices with confidence.
Learn more
To access the full dataset, company-level analysis, and the operational playbooks referenced in this release, please visit our report landing page. The complete Therapeutic Nuclear Medicines Market report contains the detailed segment-level intelligence, methodologies, and appendices required for transaction diligence and board-level strategic planning.
For detailed analysis of this topic, please visit the official page: Therapeutic Nuclear Medicines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com