

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Antifreeze & Coolants Market to Climb from USD 215.0 Million in 2025 to USD 304.6 Million by 2032 at a 5.23% CAGR

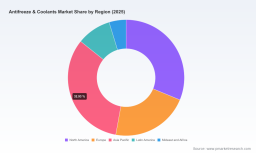
Antifreeze & Coolants Market — Strategic Outlook 2026: A PW Consulting Intelligence Brief
Why this matters for 2026 decision-makers
Global demand for antifreeze and coolants is no longer a simple function of vehicle parc growth. By 2025 the market reached approximately USD 215.0 Million (base year), after growing steadily from 2020, and PW Consulting’s integrated forecast anticipates expansion to roughly USD 231.9 Million in 2026 and to about USD 304.6 Million by 2032 — a compound annual growth rate of 5.23% over the forecast horizon. For manufacturers, suppliers, OEM procurement teams, fleet operators and investors, that trajectory signals both sustained baseline demand and differentiated pockets of premiumization and innovation. The question for 2026 is not whether the market will grow, but who will capture higher-margin, resilient slices of that growth while insulating profit pools from raw-material volatility and regulatory change.
Antifreeze & Coolants Market
What our report delivers — pragmatic, decision-ready intelligence
- Concise executive synthesis that links macro trends to commercially actionable options for 90-day and 12-month horizons.
- Proprietary historical demand reconstruction (2020–2025) and a bottom-up/ top-down integrated forecast engine for 2026–2032, with scenario toggles for raw material shocks, OEM-spec shifts and EV adoption curves.
- Supply-side playbooks: supplier benchmarking, cost-to-serve models, and a provider scorecard built on performance metrics that matter to procurement and business development teams.
- Raw-material risk matrix and pricing scenarios that quantify margin exposure to feedstock swings and regional supply constraints.
- Regulatory mapping tied to product compliance pathways, including recommended testing and certification timelines aligned with updated standards.
- Commercial go-to-market templates for concentrate vs ready-mix strategies, packaging innovations, and aftermarket distribution optimization.
- An interactive financial model (confidential Excel) to stress-test pricing, inventory and capex decisions under multiple market-stress scenarios.
Market dynamics shaping strategic choices in 2026
Three interlinked forces will determine winners and laggards in the coming 12–36 months: raw-material volatility, regulatory tightening, and product/packaging innovation.
Antifreeze & Coolants Market
- Raw-material pressure. Feedstock tightness and rising monoethylene glycol (MEG) costs have become a core margin lever. By early 2026 Asian spot MEG prices rose materially, reflecting tightening supply and higher upstream feedstock costs. European MEG pricing also experienced abrupt uplifts due to supply concerns. For midstream formulators and downstream converters, these movements translate into compressed gross margins and the need for deliberate hedging strategies or contract re-negotiation with customers.
- Regulatory and standards evolution. Industry stakeholders must incorporate updated performance standards into product development timelines: ASTM International’s revised heavy-duty engine coolant specification (D6210-25) came into effect in late 2025. That update raises the bar for formulators serving commercial vehicle and industrial cooling markets, creating both compliance costs and an opportunity to differentiate through verified extended-life performance.
- Product and packaging innovation. The market is seeing rapid iterations around extended-life chemistries (including organic-acid technologies), concentrated formulations, and packaging formats that reduce logistics and waste. Recent launches demonstrate how small changes in format — e.g., pouch systems or higher-concentration offerings — can materially affect logistics, shelf-space economics and sustainability positioning.
Competitive landscape — strategic positioning of the core players
The current competitive topology is moderately concentrated, with a handful of global majors exerting scale advantages while regional and specialty players compete on formulation, service and aftermarket reach. Key competitor archetypes and their strategic levers include:
Antifreeze & Coolants Market
- Global integrated majors (e.g., ExxonMobil, Shell, Chevron, TotalEnergies). These players leverage global distribution networks, integrated lubricant portfolios and scale purchasing to offer extended-life and heavy-duty formulations. Their advantage is speed-to-market for spec-compliant products and the ability to bundle product-service offerings for fleet customers.
- Specialist formulators and brand leaders (e.g., Prestone, Valvoline, Old World Industries, Recochem). These companies focus on consumer-facing brands, aftermarket penetration and formulation diversity (including premium OEM-facing products). Their strategic moves often center on packaging innovation, consumer convenience and targeted marketing to repair chains.
- Advanced-chemistry and B2B suppliers (e.g., BASF, Motul). These firms concentrate on R&D-driven product differentiation, OEM approvals and niche segments such as two-wheel or performance cooling systems.
Recent market activity illustrates these archetypes in action. Consumer packaging innovations that cut package weight and materials have been launched by major aftermarket brands, and formulation rollouts using Organic Acid Technology (OAT) are being introduced to meet newer OEM and aftermarket expectations. These developments signal that 2026 will reward players who can combine formulation compliance, supply security and lowered total cost of ownership.
Strategic implications by value chain node
- Manufacturers / formulators: Re-assess raw-material procurement strategies to include layered hedges and regional sourcing diversification; accelerate qualification cycles for new formulations that meet updated ASTM standards; evaluate conversion at source to capture value in concentrates.
- OEMs & fleets: Recalibrate service interval recommendations and coolant specifications to account for extended-life chemistries; integrate coolant performance metrics into warranty and maintenance economics; negotiate longer-term supply agreements with indexed pricing clauses tied to MEG movements.
- Distributors & aftermarket operators: Test packaging changes that reduce logistics cost and shelf-inventory risk; prioritize SKU rationalization to improve fill-rates and working capital.
- Investors & M&A teams: Target assets with strong OEM approvals, regional production footprints that mitigate freight exposure, or specialty chemistries that can be scaled economically.
Actionable 90-day and 12-month playbooks for 2026
Our clients have found the highest near-term returns come from focused, executable moves that reduce downside and set the stage for growth:
- 0–90 days: Run a margin-at-risk assessment under the latest MEG price scenarios; implement spelled-out procurement actions (short-term hedges, secured allocation agreements); accelerate ASTM compliance testing paths for heavy-duty portfolio items; pilot a reduced-packaging SKU in one major market to validate logistics savings.
- 3–12 months: Rebalance product portfolio toward higher-value extended-life formulations where justified by OEM demand; deploy regional blending hubs to lower freight and inventory costs; negotiate partnership agreements with reclamation/recycling providers to secure circular glycol streams and improve sustainability credentials; pursue bolt-on acquisitions to fill formulation gaps or expand aftermarket reach.
Why PW Consulting’s report matters — methodology and unique assets
This report is built for decision-makers who need prescriptive answers, not just descriptive charts. Our methodology blends granular shipment and consumption build-ups, proprietary pricing series for key feedstocks, a scenario engine that models regulatory and technology adoption inflection points, and direct supplier intelligence gathered from interviews and plant-level benchmarking. The output is a set of priority-ranked initiatives with quantified P&L and cash-flow impacts across scenarios — enabling leadership teams to commit capital with greater confidence.
Next steps — how to use this intelligence
If your 2026 planning includes pricing resets, contract renegotiations, product reformulation, or M&A horizon-scanning, this report provides the evidence base and executable templates to move from strategy to action. PW Consulting also offers confidential executive workshops to translate the forecast and scenarios into bespoke commercial plans, procurement hedges and R&D roadmaps.
To access the full dataset, vendor scorecards and the interactive scenario model — including the granular segmentation tables and map-based supply-risk analytics that underpin the projections in this brief — please visit PW Consulting’s Antifreeze & Coolants Market report page or contact our industry practice lead for a guided walkthrough. The summary above is intended to demonstrate our analytic depth and to identify the most impactful decisions for 2026; the complete report contains the detailed segment tables, supplier profiles and price-sensitivity matrices required to implement the actions described.
PW Consulting — Turning market foresight into decisive commercial advantage.
For detailed analysis of this topic, please visit the official page: Antifreeze & Coolants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com