

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Glyoxal Market Set to Hit USD 469 Million by 2032 with 3.87% CAGR; Asia‑Pacific Leads at USD 146.84 Million

Glyoxal Market 2026 Strategic Outlook — A PW Consulting Executive Brief
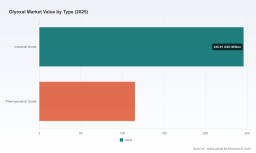
As organizations reset strategies for 2026, glyoxal sits at an inflection point driven by raw-material volatility, tightening regulatory scrutiny, and evolving end-use demand. PW Consulting’s Glyoxal Market Report (base year: 2025; forecast: 2026–2032) synthesizes historical performance, supply-chain dynamics, and future scenarios into a practical decision-making toolkit. Our baseline model projects the global glyoxal market to grow at a compound annual growth rate (CAGR) of 3.87% from 2026 through 2032, moving from approximately USD 361 million in 2025 toward a materially larger market by 2032 under our central scenario.
Glyoxal Market
Why this report matters for 2026 corporate decisions
- It translates macro trends into actionable levers — pricing exposure, product-mix shifts, and capex timing — that directly affect margins in the near term.
- It frames regulatory risk as an operational and commercial constraint, not just a compliance checkbox, enabling revenue-protection measures and product reengineering priorities.
- It maps competitive positioning against a market that is moderately concentrated (CR3 ≈ 46%, CR5 ≈ 54%), identifying where scale buys resilience and where niche specialization buys margin.
What’s inside — practical, implementation-oriented analysis
The report is structured to move rapidly from insight to action. Key deliverables include:
Glyoxal Market
- Executive playbook: scenario-based guidance for procurement, pricing, and product strategy under three near-term market paths (conservative, baseline, accelerated).
- Supply-chain heatmaps: supplier concentration, logistics chokepoints, and critical feedstock exposures with mitigation options (contract structures, hedging, backward integration).
- Regulatory and product-risk matrix: jurisdictional monitoring priorities, reformulation triggers, and compliance-cost estimates tied to likely timelines.
- Commercial playbooks for end-use sectors: high-level demand elasticity, switching risk, and go-to-market options for specialty vs. commodity grades.
- Valuation and M&A checklist: target profiles, integration risks, and deal-structuring templates for bolt-on scale or capability purchases.
- Operational benchmarking: margin drivers, utilization sensitivities, and capital scheduling guidance keyed to forecast inflection points through 2032.
Market dynamics shaping 2026 strategy
Three dynamics require board-level attention when forming 2026 plans:
Glyoxal Market
- Feedstock volatility and margin pressure. Glyoxal production remains exposed to formaldehyde and upstream methanol markets. For example, regional formaldehyde benchmarks showed significant movement across late 2025 and early 2026 — Northeast Asia levels registered a notable uptick in December 2025 compared with September, while European quotes rose by early 2026 driven by resin and panel manufacturing demand. India exhibited a different rhythm with marked quarterly swings in late 2025 and early 2026. These divergences create opportunities for geographically agile suppliers but increase short-term margin erosion for players lacking hedging strategies.
- Regulatory tightening and product requalification risk. Regulatory authorities are intensifying scrutiny of dialdehydes. The European Chemicals Agency has signaled a reassessment of workplace exposure limits, and global health reviews are amplifying concerns around glyoxal’s role in advanced glycation end-products. Concurrently, U.S. states are implementing restrictions tied to formaldehyde-releasing chemicals in personal-care products. These developments mandate earlier investment in alternative formulations, occupational controls, and extended product stewardship programs.
- Market structure: consolidation vs. specialization. The glyoxal market shows moderate concentration — the top three and top five players control meaningful but not overwhelming shares of market supply. That structure favors both large integrated producers (who win on scale and reliability) and focused specialists (who win on premium grades and technical service). 2026 decisions should explicitly weigh whether to pursue scale, deepen specialty capabilities, or partner to access complementary channels.
Competitive landscape — who matters and why
The competitive field combines global diversified chemical majors, regional producers, and specialty suppliers. Representative players include large integrated manufacturers with world-scale production and supply-chain reach, alongside niche firms focused on high-purity or regionally important end markets. Strategic implications by operator type:
- Integrated majors (scale + integration): Companies with colocated production of upstream intermediates and downstream derivatives are advantaged when feedstock prices are volatile. They can optimize internal streams and offer stable offtake terms to key resin, textile, and oil & gas customers.
- Regional champions (distribution reach): Firms with dense local networks provide quick response and customized logistics—critical in textile hubs and fast-moving consumer sectors.
- Specialists (high-purity, pharma-grade): Suppliers of pharmaceutical and laboratory-grade glyoxal command premium pricing and tighter technical relationships, making them attractive acquisition targets for companies seeking product differentiation.
PW Consulting’s report profiles leading companies and distills their strategic postures — from world-scale producers emphasizing integrated supply to specialized manufacturers targeting high-value applications. These profiles identify potential partners, acquisition targets, and competitive threats without disclosing proprietary market shares or unit economics that buyers must review in the full study.
Strategic priorities for 2026 — actionable recommendations
Based on our analysis, management teams should prioritize the following strategic moves in 2026:
- Lock in feedstock resilience. Negotiate flexible, indexed contracts with methanol and formaldehyde suppliers, and evaluate backward integration where scale economics permit.
- Develop a regulatory-first product roadmap. Fast-track testing for lower-release and alternative cross-linking chemistries; create rapid regulatory submission pathways to maintain market access in sensitive jurisdictions.
- Differentiate through service and derivatives. Invest in formulation labs and technical application support that convert commodity supply into sticky, higher-margin relationships.
- Revisit capex timing against demand scenarios. Use the report’s scenario outputs to phase capacity projects and avoid the classic “overbuild-then-reprice” cycle in cyclical end markets.
- Pursue disciplined M&A and partnerships. Target regional distribution platforms or specialty producers to expand addressable markets quickly while hedging greenfield execution risk.
- Enhance commercial agility. Implement dynamic pricing tools linked to feedstock indices and develop tiered product offerings (commodity, technical, pharma) to capture broad customer willingness-to-pay.
Risk register — what keeps CFOs awake
Key risks that should be stress-tested in 2026 planning include:
- Regulatory tightening leading to restricted use in certain consumer categories and added compliance costs.
- Persistently higher feedstock prices or sudden supply disruptions cascading into margin compression.
- Demand shifts in major end-use sectors driven by substitution, circular-material innovations, or end-market slowdowns.
- Competitive overcapacity from new entrants that erode returns in key regional markets.
How executives can use the PW Consulting report today
The report is built to be operational: executive summaries for boards, a two-page procurement playbook, scenario-ready capex models, and a legal-regulatory tracker ready for immediate adoption. Senior leaders will find the report useful for setting 2026 budgets, designing supply agreements, prioritizing R&D spend, and shaping M&A screening criteria.
What we intentionally withhold here — and why you should read the full study
To preserve the report’s commercial integrity and encourage direct engagement, we have deliberately summarized strategic insight while withholding granular segmentation tables, exact regional or application-level revenue splits, proprietary price-elasticity curves, and full company-level financial models. These elements are included in the full report because they are essential for transaction diligence, procurement negotiations, and precise financial forecasting.
Next steps — engaging with PW Consulting
For executives preparing 2026 plans, PW Consulting offers three immediate options:
- Download the full Glyoxal Market Report for the detailed segmentation, 2020–2032 historicals and forecasts, and downloadable financial models.
- Commission a bespoke deep-dive: tailored analysis by region, application, or counterparty due diligence for an M&A target.
- Schedule a strategy workshop: a half-day session to convert report scenarios into a board-ready action plan with prioritized initiatives and ROI forecasts.
Glyoxal may appear as a medium-sized ingredient in chemical portfolios, but its strategic ripples — via feedstock linkage, regulatory scrutiny, and end-use dependency — can decisively affect margins and market access. Our 2026 guidance equips leaders to convert visibility into competitive advantage: by protecting margin, aligning to emerging regulations, and selectively investing in the capabilities that matter most as the market evolves through 2032.
For detailed analysis of this topic, please visit the official page: Glyoxal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com