

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Toilet Partitions Market to Reach USD 3.59 Million by 2032 at a 4.5% CAGR as Top 5 Players Command 76.4% Share

Toilet Partitions Market: Strategic Outlook for 2026 — PW Consulting Issues Actionable Intelligence to Guide Executive Decisions
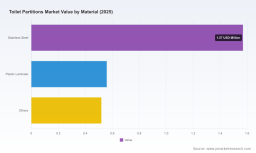
As organizations prepare capital and procurement plans for 2026, PW Consulting releases a focused industry briefing derived from our full Toilet Partitions Market research. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, this executive-grade analysis translates market dynamics into decision-ready guidance. At the core of the study is a market trajectory that reflects steady expansion: the sector’s baseline value stands at approximately USD 2.65 Million in 2025 and, under our central-case assumptions, is projected to reach roughly USD 3.59 Million by 2032—implying a compound annual growth rate of about 4.5% across the forecast window.
Toilet Partitions Market
Why this matters for 2026 decisions
- Capital planning: Procurement timetables and facility upgrades should be calibrated to a market that is growing predictably but subject to episodic cost pressure and regulatory shifts.
- Supplier strategy: With a market that shows meaningful concentration among leading vendors, buyers and vendors alike must refine sourcing and partnership models to secure margins and delivery assurance.
- Product innovation and specification: Material choice, hygienic performance, and sustainability credentials are increasingly decisive inputs for public and institutional projects—areas that will determine access to higher-margin contracts.
Market snapshot and growth dynamics
The market’s modest but consistent expansion reflects three intersecting forces. First, replacement and retrofit cycles in institutional, commercial, and public infrastructure segments continue to generate steady baseline demand. Second, building codes and accessibility requirements are raising minimum specification thresholds in many procurement processes, prompting upgrades even where new construction is muted. Third, selective investment in higher-value partitions—driven by antimicrobial surfaces, recycled-content specifications, and premium finishes—has been a growth lever for suppliers that can execute custom and specification-heavy projects.
Toilet Partitions Market
PW Consulting’s modeling incorporates recent pricing trends, labor and input cost volatility, and a multi-scenario assessment of construction activity across public and private sectors. The result is a robust central forecast that assumes a 4.5% CAGR to 2032 while also presenting downside and upside scenarios that stress-test procurement and supply-chain strategies under tighter or looser capital spending conditions.
Toilet Partitions Market
Key market forces to watch in 2026
- Regulatory compliance and accessibility: Ongoing enforcement of accessibility standards is sustaining demand for compliant compartment configurations. Project teams that build compliance checks into early-stage design reduce change orders and schedule risk.
- Input-cost pressure and pricing dynamics: Manufacturers are adjusting list prices in response to partner and labor cost shifts; some vendors have implemented notable price increases within the last 12–18 months. Buyers should expect continued negotiation around price escalators and should structure contracts to mitigate warranty and service liabilities tied to material performance.
- Material and sustainability considerations: Durable metals and engineered polymers remain the dominant choices; however, lifecycle performance, recycled content, and end-of-life considerations are gaining traction in public tenders and ESG-aligned private projects.
- Delivery and lead-time risk: Quick-ship offerings and modular systems are reshaping competitive positioning. Organizations with tight project timelines benefit materially from prioritizing suppliers with demonstrated quick-ship capabilities and regional distribution breadth.
Competitive landscape — what procurement and strategy teams need to know
The market shows a meaningful degree of concentration among established manufacturers and systems providers. Our market-concentration metrics indicate that the top three competitors control a significant majority of market share, with the top five extending that dominance. This structure creates both opportunities and risks for market participants: scale advantages in manufacturing, catalog breadth, and logistics capacity favor incumbents, while nimble niche players can compete on customization, speed, and service.
Leading suppliers evaluated in the report illustrate distinct competitive plays:
- Bobrick Washroom Equipment, Inc. (United States): A full-spectrum provider with strong emphasis on engineered selections, ADA compliance, and custom configurations. Recent catalog updates reflect an intensified product-engineering push and a broader specification toolkit for complex projects.
- Hadrian Inc. (United States): Differentiates through coated and phenolic systems and explicit support for green-building certifications. Hadrian’s product positioning targets projects where certified recycled content and lifecycle performance are procurement priorities.
- Bradley Corporation (United States): Competes with a diverse portfolio that includes premium finishes and antimicrobial surfaces—an attractive profile for healthcare and hygiene-sensitive environments.
- General Partitions Manufacturing Corp. (United States): Known for HDPE offerings and fast-turn privacy solutions; recent catalog activity highlights its quick-ship capabilities that de-risk schedule-sensitive programs.
- Inpro Corporation (United States): Positions on durability and institutional-grade systems, with strengths in metal and laminate partitions for long-life installations.
- ASI Global Partitions (Canada): Competes via integrated privacy solutions and a range that includes high-height and ceiling-hung systems—useful in projects seeking architectural continuity.
- Scranton Products (United States): A leading HDPE supplier with deep customization capacity and recent portfolio expansion through asset acquisitions, strengthening its reach in government and healthcare verticals.
Recent vendor activity underscores the strategic vectors shaping competition: several major catalog refreshes in 2026 signal a renewed emphasis on engineered options and specification clarity, while M&A activity among privately held portfolio companies indicates consolidation of manufacturing and distribution assets in select product segments.
Strategic implications for executives in 2026
- Procurement playbooks should explicitly incorporate supplier concentration risk. For large projects, adopt a dual-track sourcing strategy that balances incumbent performance with secondary suppliers for contingency supply.
- Contract structures must account for input-cost escalation and lead-time guarantees. Including well-defined price escalation formulas, change-order protocols, and service-level clauses reduces execution volatility.
- Design teams should standardize specification families that optimize for total cost of ownership rather than first-cost alone. Material selection, serviceability, and end-of-life considerations materially affect lifecycle budgets in public and institutional portfolios.
- Manufacturers and distributors should invest in quick-ship SKUs, configurable modular systems, and digital specification tools to capture projects with compressed schedules and to reduce sales friction for specification-driven buyers.
- Investors and M&A teams should weigh the benefits of scale in distribution and production versus the attractive margins available in niche, specification-led segments. Our concentration metrics point to continued acquisition opportunities that can consolidate manufacturing footprints and broaden catalog depth.
What the PW Consulting report delivers — practical, implementable tools
Beyond market sizing and scenario forecasts, the full report provides an actionable toolkit designed for use by procurement directors, facility managers, architects, and private equity investors. Highlights include:
- Decision matrices that map product families to typical project risk profiles and lifecycle cost outcomes.
- Supplier scorecards and due-diligence templates that translate qualitative strengths (e.g., customization, quick-ship capability, sustainability credentials) into procurement-ready metrics.
- Contract clause libraries covering price escalation, warranty obligations, delivery milestones, and remediation pathways to reduce project friction.
- Bid and cost-model templates that allow buyers to compare total cost of ownership across alternative material and mounting choices.
- Scenario-based sensitivity analyses that stress-test capital allocation decisions under differing construction spending paths and input-cost inflation regimes.
- Market-concentration and competitive-moves playbooks to inform M&A screening or partnership strategies, supported by vendor profiles and recent development summaries.
How to use this intelligence in practice
For a facilities director planning a multi-site retrofit, the most immediate application is to align specification standards across the estate to reduce SKUs and leverage volume discounts—use our supplier scorecards and TCO templates to quantify trade-offs. For procurement teams managing public tenders, integrate the provided regulatory checklist and contract clauses to minimize compliance-driven change orders. For investors and corporate strategy leaders, leverage the concentration analysis and scenario models to prioritize acquisitions that fill distribution or product gaps.
Next steps and access to full findings
PW Consulting’s Toilet Partitions Market briefing is intentionally constructed as a high-value executive preview: it surfaces the structural trends, competitive dynamics, and operational levers that matter to 2026 strategy while reserving the granular segmentation tables and full numeric breakdowns for subscribers to the complete report. For organizations serious about converting market intelligence into procurement advantage or strategic investment, the full report contains the proprietary segment analyses, supplier market shares, and localized demand forecasts that support transaction-level decision-making.
Contact PW Consulting to obtain the full study, which includes downloadable procurement templates, contract language libraries, and a workshop package designed to translate the findings into a 90-day action plan. Our team stands ready to run bespoke scenario analyses that reflect your project pipeline, risk tolerances, and supplier network.
For detailed analysis of this topic, please visit the official page: Toilet Partitions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com