

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Vertical Probe Cards Market to Expand at 8.5% CAGR Through 2032

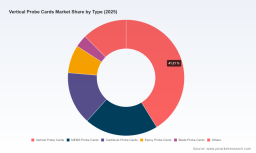
Vertical Probe Cards Market: Strategic Imperatives for 2026 — PW Consulting Preview
The Vertical Probe Cards market has transitioned from a niche test-equipment segment into a strategic choke point for advanced semiconductor throughput and qualification. Our base-year assessment (2025) positions the sector on a robust growth path, expanding from roughly USD 1.1 billion in 2020 to about USD 1.64 billion in 2025, and projecting toward nearly USD 2.93 billion by 2032 at an 8.5% compound annual growth rate. For executives making capital, sourcing, or product decisions in 2026, this report preview outlines the precise levers that will determine competitive advantage — while reserving granular segment-level tables and region/application breakdowns for the full publication.
Vertical Probe Cards Market
Why 2026 Is a Strategic Inflection Point
- Node compression and heterogenous integration: The combination of sub-5nm node qualification needs and the rise of chiplet architectures is forcing probe-card providers and device-makers into more intensive co-development cycles. Development costs for next-generation cards are materially higher — a trend we quantify and model in the full report.
- Cost and complexity escalation: Leading-edge probe cards now carry significant development and validation price tags (industry reports indicate costs for advanced cards can exceed multi-million-dollar thresholds), which changes procurement calculus from transactional sourcing toward strategic partnerships and risk-sharing models.
- Supply-chain and raw-material volatility: Limited availability of ultra-low-resistance materials and specialty ceramics is already creating bottlenecks; our supply-stress modeling shows these constraints amplify qualification timelines and margin pressure through 2026.
- Geopolitics and regulatory fragmentation: Export controls and trade-policy shifts are fragmenting supply chains, creating both demand for localized production and new opportunities for vendors that can certify designs under constrained technology transfer regimes.
- Market concentration and innovation dynamics: Market concentration metrics reveal a top-tier supplier group holding a commanding share of advanced vertical probe card capability, accelerating consolidation and selective M&A as companies race to secure IP and qualification pathways.
What the PW Consulting Report Delivers to Decision‑Makers
Our Vertical Probe Cards Market report is constructed as an operational playbook, not an academic snapshot. It combines granular market sizing with scenario-driven strategy tools designed for procurement directors, test-engineering leads, CTOs, and corporate development teams who must make 2026 commitments under uncertainty.
Vertical Probe Cards Market
- Market-sizing with scenario overlays: A base forecast anchored on the 2025 baseline, plus three alternative demand scenarios that stress-test node adoption, wafer fab CAPEX, and test-content per die.
- Technology and qualification roadmap: Comparative diagnostics of vertical probe architectures (including MEMS, spring, and hybrid approaches), qualification complexity by node, and recommended development timelines to hit typical wafer-acceptance windows.
- Total cost models: Build-up models that capture prototyping iterations, materials, multi-temperature validation, and recurring servicing — enabling CAPEX/OPEX trade-off analysis for in-house development versus outsourced sourcing.
- Supplier scorecards and negotiation playbooks: A repeatable evaluation framework for supplier technical competence, capacity risk, qualification throughput, IP robustness, and commercial terms — plus scripts and contracting structures that move risk off the balance sheet.
- Supply-chain stress tests and mitigation templates: Multi-node simulations that reveal where single-source dependencies and material scarcity will create the longest delays, with concrete mitigations such as multi-sourcing roadmaps, long-lead contracts, and collaborative inventory pooling.
- M&A and partnership playbook: Valuation templates calibrated to probe-card economics, a checklist for due diligence on MEMS and spring-technology IP, and a post-merger integration guide focused on manufacturing transfer and qualification acceleration.
- Test-floor optimization and capacity planning: Practical recommendations for test-house layout changes, modular card architectures to shorten changeover, and staffing/skill investments to reduce qualification cycle times.
The preview withheld here omits the full segment-level data and drilldowns that buyers and strategists require to execute changes; those are available in the complete report and dataset.
Vertical Probe Cards Market
Competitive Landscape — Who Matters and Why
The competitive map in 2026 is shaped by a mixture of global incumbents, regional specialists, and aggressive challengers. Market concentration remains high: the top three suppliers account for a dominant portion of advanced capability, and a top-five group consolidates an even larger share. That structure drives both defensive incumbent strategies and tactical openings for high-focus entrants.
- FormFactor Inc. — A strategic innovator in high-parallelism vertical cards and modular designs. Recent acquisitive moves to capture MEMS-related IP and spring optimization patents position them to shorten prototyping timelines and defend fine-pitch automotive/industrial accounts.
- Technoprobe S.p.A. — Aggressive capacity expansion in Europe signals a play for localized fab qualification work and near-shore supply to mitigate geopolitical disruption risks.
- Micronics Japan Co., Ltd. — Qualification by a major foundry for advanced nodes is a watershed: it validates their vertical MEMS roadmap and demonstrates the commercial payoff from long co-development cycles with leading fabs.
- MPI Corporation, Feinmetall, STAr Technologies, Japan Electronic Materials and regional players — These vendors specialize across MEMS verticals, chiplet-ready designs, and localized manufacturing, creating a mosaic of suppliers that customers must evaluate not only on price, but on qualification speed, field serviceability, and IP compatibility.
Recent corporate actions underscore two converging trends: (1) incumbents acquiring targeted IP to shave prototyping iterations and (2) facility and partnership investments aimed at shortening supply chains and accelerating qualification (notably for sub-2nm pathways and chiplet test cells). For procurement and product teams, supplier selection in 2026 must prioritize demonstrated qualification throughput and modularity over low initial price.
Risk Matrix and Mitigation Priorities for 2026
- Material scarcity and price volatility — Mitigate with long-term raw-material contracts, staggered sourcing, and design allowances that accept material substitution without requalification where possible.
- Qualification slippage — Use co-development agreements that include milestone-based payments and shared testing facilities; prioritize suppliers with field-replaceable component designs to reduce on-floor downtime.
- Regulatory fragmentation — Map regulatory constraints to supplier capability early; consider dual-sourcing strategies to retain access to multiple technology paths.
- Concentration risk — For critical programs, underwrite second-source program development with cost-sharing models to ensure capacity elasticity during ramp phases.
- Cost escalation on next-gen development — Use our cost-model templates to evaluate build-versus-buy and to price in iterative prototyping cycles, enabling defensible go/no-go decisions for in-house investments.
How to Use This Preview — A Practical 2026 Playbook
- Executive alignment: Use the headline market trajectories and risk framework here to align board and executive expectations around test-content inflation and qualification lead times.
- Run the PW scenarios: Apply our three demand scenarios to your product roadmap to quantify required probe-card capacity and to prioritize which programs merit co-developed designs versus commodity sourcing.
- Update procurement KPIs: Incorporate qualification speed and field-serviceability into supplier scorecards; renegotiate RFPs to include milestone-based qualification and extended warranty terms.
- Prioritize M&A and partnerships: Evaluate acquisition targets and alliances for IP that reduces prototyping cycles, and prioritize partners that can be rapidly qualified in your primary fabs.
- Stress-test budgets: Use our TCO models to stress-test CapEx requests and to justify investment in modular test-floor upgrades that reduce per-unit test time.
The full PW Consulting Vertical Probe Cards Market report contains the complete datasets, supplier scorecards, downloadable modeling templates, and the segment-by-segment tables that underpin these recommendations. We intentionally reserve detailed region/type/application splits in the full publication to ensure decision-makers have access to controlled, validated inputs before execution.
Conclusion — What to Act On in 1Q–4Q 2026
Decision-makers should treat 2026 as the year to move from reactive procurement to strategic test-supply architectures. With the market expanding from about USD 1.64 billion in 2025 toward nearly USD 2.93 billion by 2032 at an 8.5% CAGR, the window to lock in qualification, secure capacity, and influence supplier roadmaps is finite. Focus investments on suppliers or internal capabilities that reduce qualification time, provide modular serviceability, and demonstrate resilience to material and regulatory shocks. For teams ready to convert insight into action, PW Consulting’s full report provides the playbooks, models, and validated supplier intelligence needed to make defensible 2026 commitments.
Contact PW Consulting or visit our report page to access the complete dataset, supplier scorecards, and executable templates referenced in this preview.
For detailed analysis of this topic, please visit the official page: Vertical Probe Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com