

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Super Hydrophobic Nano Coating Market to Hit USD 258 Million by 2032, Growing at a 7.75% CAGR

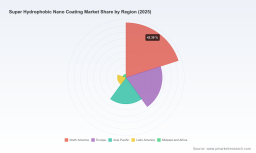
Super Hydrophobic Nano Coating Market — Strategic Imperatives for 2026
PW Consulting’s latest market study on Super Hydrophobic Nano Coatings (base year 2025, historical range 2020–2025, forecast 2026–2032) delivers an actionable roadmap for executives planning investments, product launches, and partnerships in 2026. The market is on a clear upward trajectory — valued at approximately USD 153 million in 2025 and projected to expand at a compound annual growth rate (CAGR) of 7.75% through the forecast window, reaching roughly USD 258 million by 2032. This growth presents focused opportunities for technology owners, OEMs, chemical formulators, and private equity sponsors — but only for those who move from experimentation to scalable commercialization with a disciplined strategy.
Super Hydrophobic Nano Coating Market
Why 2026 Is a Pivotal Year
2026 marks the transition from pilot-heavy adoption to early industrial-scale deployment for many superhydrophobic solutions. Three converging forces make 2026 decisive:
Super Hydrophobic Nano Coating Market
- Commercial readiness: Multiple material and application proofs-of-concept have matured into commercially viable coatings with enhanced durability, abrasion resistance, and manufacturability.
- Regulatory and sustainability pressures: Shifting restrictions on legacy chemistries and rising sustainability criteria are accelerating demand for alternatives and creating winners and losers among material pathways.
- Customer acceptance: OEMs in electronics, transportation, and industrial goods are increasingly receptive to coatings that reduce warranty claims, maintenance, and lifecycle cost — provided the performance and supply-risk profile meet their standards.
What the Report Delivers — Practical, Executable Intelligence
Our report is designed to be used, not shelved. It provides:
Super Hydrophobic Nano Coating Market
- Top-down market sizing and a transparent forecasting model (2026–2032) that links adoption rates to application economics and regulatory scenarios.
- Decision-ready playbooks for R&D prioritization, scale-up sequencing, and capex timing.
- Supplier and technology scorecards that assess formulation approaches, durability profiles, ease of integration, and commercial readiness.
- Go-to-market templates (direct, OEM licensing, coatings-as-a-service) with customer selection criteria and margin models.
- IP and regulatory compendium highlighting areas of patent density, anticipated compliance costs, and likely regional headwinds.
- A curated M&A and partnership screen listing targets by capability, geography, and valuation-bands to accelerate inorganic growth strategies.
We intentionally keep core subsegment tables and proprietary unit economics behind the full report to preserve actionable differentiation for paying subscribers; the summary here is meant to orient strategy teams and provoke targeted follow-up.
Key Strategic Themes Backed by Market Evidence
- Measured, resilient growth: The market’s projected trajectory to 2032 reflects steady commercial demand across multiple verticals. Strategy teams should plan for growth but also for variability across use-cases and geographies.
- Material pathway bifurcation: There is a practical split between ultra-thin, OEM-friendly nano-layers optimized for electronics and tougher, application-focused formulations engineered for industrial and construction environments. Each requires different scale-up investments and go-to-market tactics.
- Durability is the commercial gating factor: Laboratory contact angles and initial repellency are table stakes; abrasion resistance, adhesion under cyclic stress, and long-term chemical stability determine replacement cycles and pricing power.
- Regulatory risk is a strategic lever: Evolving restrictions on certain fluorinated chemistries create both substitution demand and compliance costs. Companies that demonstrate low-risk chemistry and documentation will command premium access to regulated supply chains.
- Fragmentation and opportunity: The competitive field remains fragmented: there are many regional specialists and a few technology leaders. That fragmentation creates opportunities for roll-up strategies, licensing deals, and exclusive supply agreements with OEMs.
Competitive Landscape — Tactical Takeaways
The market features a mix of specialist technology providers, OEM-focused suppliers, and regional manufacturers. Our analysis of leading players yields the following tactical insights:
- Aculon Inc. (United States): Strength in patented chemistries for metals, glass, and polymers. Best-in-class for companies seeking cross-material compatibility and IP-backed formulations. Strategic move: pursue joint development with surface-prep vendors to accelerate OEM acceptance.
- NEI Corporation (United States): Notable for abrasion-resistant graded layers. Advantageous partner for industrial clients requiring wear durability. Strategic move: co-develop application-specific abrasion test protocols to shorten customer qualification cycles.
- Artekya Technology / Nasiol (Turkey/US): Demonstrated high contact-angle, two-layer systems with strong automotive and marine traction. Strategic move: seek OEM coating trials emphasizing long-term aesthetic retention and hydrophobic performance.
- P2i Ltd (United Kingdom): Leader in ultra-thin liquid-repellent coatings for electronics and consumer devices; established OEM relationships and industrialized deposition methods. Strategic move: explore licensing or captive manufacturing partnerships to secure priority access for device launches.
- UltraTech International (United States/Malaysia): Industrial and construction-oriented solutions and spray-and-dry systems. Strategic move: bundle coatings with service offerings for maintenance contracts in infrastructure projects.
- RTP Company & Nanex: RTP’s formulation capabilities and Nanex’s textile specialization reveal white-space opportunities where custom compounds meet technical fabrics for PPE and outdoor products. Strategic move: pilot co-branded products to capture specialty-market premiums.
- Lotus Leaf, HydroBead, Stanvac, EZ Coating: These suppliers represent tactical suppliers and regional plays. They are potential acquisition targets for firms seeking rapid entry into specific verticals or cost-competitive production footprints.
Operational Recommendations for 2026
- Initiate narrowly scoped pilot programs with OEMs that have the fastest qualification cycles (e.g., select electronics and specialty automotive applications) to demonstrate ROI within 12–18 months.
- Prioritize R&D investments into abrasion resistance and adhesion under environmental cycling — the fastest route to justify price premiums and reduce total cost of ownership for customers.
- Diversify raw-material suppliers and develop secondary sourcing plans for critical intermediates to mitigate supply shocks and raw-material price volatility.
- Develop a regulatory & sustainability monitoring function tied to product roadmaps. Anticipate substitution needs and pre-certify alternatives to avoid go-to-market interruptions.
- Construct two commercial tracks: (1) a premium, OEM-integrated model with co-engineering and exclusivity, and (2) a broad-market distribution model leveraging channel partners for retrofit and aftermarket sales.
- Build an M&A playbook: identify regional specialists and formulation innovators as bolt-on targets to rapidly expand capability or capacity while preserving cost discipline.
Scenario Planning — Four Outlooks to 2032
Effective strategy requires stress-testing assumptions. Our report models four scenarios with quantified implications for demand, price erosion, and investment timing:
- Base Case: Steady adoption across target verticals consistent with the market’s medium-term CAGR (7.75%).
- Accelerated Adoption: A faster shift driven by regulatory bans or a major performance breakthrough, prompting earlier scale-up and pricing power.
- Constrained Growth: Slow commercial uptake due to qualification delays and higher-than-expected durability failures, forcing product reengineering.
- Disruptive Substitution: Emergence of a radically different water-repellent platform that re-prices incumbent technologies and reshapes supplier economics.
Each scenario is linked to recommended timing for capex, R&D milestones, and M&A triggers — essential tools for boards and strategy teams deciding how aggressively to commit resources in 2026.
Why This Report Matters to CEOs and Strategy Teams
For leaders planning moves in 2026, the question is not whether the market grows (it will), but whether you are positioned to capture disproportionate value. PW Consulting’s study turns market forecasts into executable choices: where to pilot, when to scale, which partners to lock, and how to price for differentiated durability. The intelligence is designed to shorten learning curves, reduce costly missteps in qualification, and align investment timing with realistic adoption curves.
We have deliberately kept granular subsegment tables and proprietary unit economics in the full report to preserve competitive advantage for subscribers. If your team is evaluating capex, M&A, licensing, or product-line investments in superhydrophobic coatings in 2026, the full PW Consulting report provides the empirical foundations and playbooks needed to act with confidence.
Next Steps
To review the full segmentation, regional and application breakdowns, company scorecards, and the downloadable forecast model that drove our conclusions, visit PW Consulting’s report page. The detailed data and templates will enable your leadership team to convert market opportunity into measurable, defensible outcomes across 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Super Hydrophobic Nano Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com