

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Cryo‑Electron Microscope Market to Expand at a Robust 11.65% CAGR Through 2032

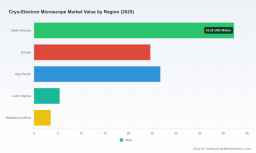
Cryo-Electron Microscope Market: Strategic Insights for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market research synthesizes the macro momentum and tactical considerations that will shape capital allocation, procurement strategies, and R&D roadmaps in the Cryo-Electron Microscope (Cryo-EM) ecosystem in 2026. The market has moved from a nascent niche into a clearly accelerating commercial phase—growing from roughly USD 60 Million in 2020 to USD 102.5 Million in our base year (2025), and projected to expand at a compound annual growth rate of 11.65% through 2032, reaching approximately USD 220.5 Million. For executives and technical leaders who must decide where and when to invest in platforms, services, or enabling technologies, the report provides an actionable bridge between high-level opportunity and procurement-level execution—without giving away the proprietary, segment-level intelligence reserved for full access.
Cryo-Electron Microscope Market
Macro trajectory and what it means for 2026 planning
The Cryo-EM market’s historical trajectory underscores two concurrent dynamics important for strategic planning. First, rapid adoption in structural biology and adjacent fields has driven outsized revenue growth in recent years. Second, the technology stack is undergoing product-level reinvention—integrating AI-enabled automation, higher-voltage optics, and workflow-level modularity that reduce hands-on time and expand use-cases beyond elite national labs.
Cryo-Electron Microscope Market
For 2026 decision-making, this combination implies a narrowing window to capture first-mover advantages in capability investments (e.g., high-throughput single-particle workflows, cryo-electron tomography hubs). Organizations that defer investing until price signals normalize risk paying a premium in both time-to-data and partner selection constraints.
Cryo-Electron Microscope Market
Drivers of adoption and near-term inflection points
- Technology convergence: Vendors are embedding automation and AI to reduce operator dependence, increasing throughput and reproducibility. This shifts value from hardware-only procurement to integrated, subscription-style service models and software licensing.
- Funding and access initiatives: Public funding programs and national center initiatives have meaningfully increased access to high-end instrumentation and training—reducing the barrier-to-entry for academic groups and mid-sized biotech companies while stimulating demand for distributed service providers.
- Workforce and curriculum effects: The integration of Cryo-EM into structural biology training programs is creating a deeper talent pool. The result: more organizations will view owning or co-investing in Cryo-EM capability as strategically viable rather than an exotic luxury.
- Cost-of-ownership realities: High-end platforms carry substantial capital and operating expenses (procurement often in the multi-million-dollar range with significant annual maintenance), so total cost of ownership (TCO) and utilization modeling are decisive in vendor selection and deployment models.
Implications for buyers: shaping procurement and operational strategy
Buyers should approach the 2026 procurement cycle with a three-layered strategy.
- Capacity-first scenario planning: Model utilization across optimistic, base, and conservative demand curves—incorporating shared-access and service-provider options. Given procurement lead times and funding cycles, many organizations will find hybrid ownership/service models optimal in the near term.
- Vendor capability assessment: Beyond headline performance (voltage, resolution), evaluate vendors on automation maturity, software roadmaps, detector performance, and service network density. Contracts should include measurable milestones for uptime, software updates, and data-handling interoperability.
- TCO and upgrade path negotiation: Negotiate multi-year maintenance, calibrated trade-ins, and predictable upgrade pathways. Because high-end systems require meaningful annual upkeep, procurement teams must fold maintenance and consumables into capital planning, not treat them as marginal line items.
Supplier landscape: competition, consolidation, and strategic positioning
The vendor landscape is increasingly stratified. Established instrument OEMs continue to dominate the high-end of the market by combining optical performance with integrated workflows; accessory and subsystem providers compete on modularity and cross-vendor interoperability. The market demonstrates significant concentration among the top suppliers, with the largest vendors collectively holding the majority of industry revenues—an important consideration for supply resilience and negotiation leverage.
Selected strategic profiles (illustrative):
- Thermo Fisher Scientific: Reinforced its market leadership with the Krios 5 launch, emphasizing enhanced optics and AI-enabled automation that shorten time-to-structure for demanding structural biology applications. Their integrated platform strategy and global service footprint make them a natural choice for large-scale centers and pharma-scale deployments.
- JEOL Ltd.: Continued focus on field-emission instruments optimized for single-particle analysis maintains JEOL’s relevance in labs prioritizing raw imaging performance for beam-sensitive specimens.
- Carl Zeiss AG: By bringing cryogenic FIB-SEM capabilities into the ecosystem, Zeiss is enabling 3D imaging workflows that complement single-particle Cryo-EM, positioning them well for cross-disciplinary material and biological research.
- Gatan, Inc.: Specialized detectors, automation modules, and cryo-FIB workflow integration keep Gatan central to throughput and data-quality improvements irrespective of microscope OEM selection.
- Oxford Instruments: As a supplier of cryogenic stages and cooling systems, they are a critical partner for labs seeking reliable thermal performance and uptime—factors that materially impact effective resolution and instrument availability.
Regulation, funding dynamics, and ecosystem effects
Recent policy and funding developments are reshaping the market’s demand profile. National-level funding opportunities and continued support for shared-access networks have a direct impact on capital formation and utilization rates. These initiatives accelerate adoption, expand training pipelines, and foster regional nodes of excellence—creating new opportunities for equipment-as-a-service providers and shared-facility operators.
From a compliance perspective, procurement and deployment teams should monitor requirements tied to federally funded infrastructure, including data management, access policies, and reporting obligations. These conditions will influence vendor selection, partnership agreements, and long-term operational liabilities.
Technology trends to watch (and hedge for)
- AI and automation: Expect software-driven productivity gains that reframe value capture away from raw hardware specs. Organizations should prioritize vendors with transparent AI roadmaps and reproducible performance claims.
- Modular ecosystems: The emergence of third-party detectors, cryo-FIB integration, and stage subsystems creates opportunities to mix-and-match solutions—if interoperability standards mature.
- Distributed infrastructure models: Shared facilities, regional hubs, and commercial service providers will proliferate, creating competition for institutional ownership while expanding market accessibility.
What PW Consulting’s report delivers (practical contents)
Our full report is designed as an operational playbook for 2026 decision-makers. Highlights include:
- Market sizing and high-confidence forecasts anchored to supplier revenues and cross-validated demand models, with sensitivity analyses under multiple adoption scenarios.
- Buyer playbooks for academia, pharma/biotech, and national labs—covering go/no-go criteria, contract templates, utilization benchmarks, and recommended service-provider engagement models.
- Vendor assessment frameworks and an actionable scorecard to evaluate optics, detectors, automation, service network, and software maturity—designed to reduce selection bias and accelerate procurement timelines.
- TCO templates and financial models that consolidate capital expenditure, maintenance, consumables, training, and depreciation across realistic utilization profiles.
- Market-entry strategy options for new entrants and accessory suppliers, including partnership archetypes, channel strategies, and IP monetization pathways.
- Scenario planning and risk matrices addressing supply-chain fragility, regulatory shifts, and funding cycles—plus contingency playbooks for high-impact outcomes.
These deliverables are purpose-built so that C-suite and lab directors can align budget cycles, grant strategies, and partnership negotiations with empirically grounded market timing.
Actionable recommendations for calendar-2026 decisions
- Align capital requests with multi-year utilization forecasts and secure conditional access agreements with regional hubs to mitigate first-mover risk.
- Prioritize vendors that demonstrate a clear software and services monetization pathway—this will reduce lifecycle costs and protect data continuity.
- Negotiate service-level agreements that include measurable automation-uptime guarantees and clearly defined software update cadences.
- Leverage public funding and shared-access grants to accelerate workforce readiness and offset early-stage capital commitments.
Why this report matters now
2026 is a pivotal year: technology maturation, public funding initiatives, and shifting procurement models converge to create a compressed decision window. Organizations that act with a strategy informed by rigorous market sizing (the market reached USD 102.5 Million in 2025 and is forecast to grow at a 11.65% CAGR to roughly USD 220.5 Million by 2032) will be better positioned to secure advantageous supplier terms, attract talent, and define franchise-defining capabilities.
Next steps
PW Consulting has packaged the full analytical dataset, vendor scorecards, and procurement playbooks behind the complete report—intentionally withholding segment-level revenue breakdowns and proprietary scoring outputs in this public summary. For procurement teams, R&D heads, and investor groups seeking the complete intelligence set and customizable Excel models, please visit PW Consulting’s Cryo-EM Market page to request the full report and discussion with our lead analysts.
For detailed analysis of this topic, please visit the official page: Cryo-Electron Microscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com