

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Soldering Flux Paste Market to Grow from USD 295.0 Million in 2025 to USD 418.44 Million by 2032 at a 5.1% CAGR — North America Leads with USD 119.1M; Rosin-Based Pastes and SMT Assembly Dominate, Top 3 Hold 55%

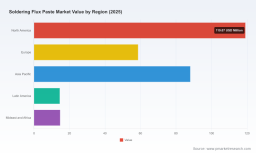
Soldering Flux Paste Market — Strategic Preview for 2026: PW Consulting Insights
Executive snapshot
As senior strategic consultants at PW Consulting, we present a focused preview of our comprehensive Soldering Flux Paste Market report (base year 2025, historical coverage 2020–2025, forecast horizon 2026–2032). The market’s macro trajectory is unambiguous: total industry revenue expanded from approximately USD 220 million in 2020 to roughly USD 295 million in 2025, and our forecast projects a continuation of steady growth to the low‑to‑mid hundreds of millions by 2032. The underlying compound annual growth rate for the forecast period (2026–2032) is 5.1% — a pace that demands strategic clarity from executives planning product, supply chain, and M&A moves in 2026.
Soldering Flux Paste Market
Why this briefing matters for 2026 decision cycles
-
Timing: 2026 is a pivot year. Post‑pandemic normalization, accelerated electronics miniaturization, and tightening environmental regulations are converging to reshape product requirements and cost structures for flux paste manufacturers and downstream assemblers.
Soldering Flux Paste Market -
Capital allocation: With predictable top‑line growth but rising input volatility, leaders must choose between margin protection through product premiumization and volume capture through cost leadership. Our report models both paths with stress tests tied to commodity shocks and regulatory scenarios.
Soldering Flux Paste Market -
Risk mitigation: Raw material dynamics and compliance risk have moved from operational to strategic. Companies that align reformulation roadmaps, hedging strategies, and supplier partnerships in 2026 will materially reduce disruption risk into 2028–2032.
Key market dynamics shaping 2026 strategy
-
Cost and commodity pressure. Refined tin — a primary input — recorded a notable dealer‑price uptick in 2025, and supply tightness coupled with broader metals market volatility has elevated cost pass‑through risk for paste makers. Our pricing models quantify breakeven points for common formulation changes and identify thresholds where product mix shifts become necessary.
-
Regulatory compression. In 2024–2025 regulators across major jurisdictions intensified restrictions on volatile organic compounds and other hazardous chemistries. That regulatory push has forced rapid reformulation cycles; manufacturers who invested early in halogen‑free and low‑VOC chemistries preserved both market access and customer goodwill.
-
Technology and application trends. Surface‑mount technology (SMT) throughput, tighter pitch components, and higher‑reliability semiconductor packaging are shifting performance requirements toward fluxes with better tack control, residue behavior, and compatibility with lead‑free alloys. These are technical demands with direct implications for R&D roadmaps and quality assurance investments.
-
Consolidation and concentration. The competitive landscape exhibits moderate concentration: the top three suppliers account for a majority share of industry revenues, and the top five widen that dominance. This structure creates both barriers and opportunities — scale enables R&D and distribution reach, while focused innovation and niche specialization create entry points for challengers.
Competitive landscape — what the leading players are doing
Our competitive assessment synthesizes public filings, product literature, and recent market activity to map strategic postures across established incumbents. Three companies emerge as reference points for 2026 competitive benchmarking:
-
Kester (Philadelphia): a legacy player with strong credentials in no‑clean and tacky flux technologies, aligned to IPC J‑STD‑004 classifications and active in lead‑free formulations. Kester’s strengths are certification depth and channel reach; their strategic challenge is translating product pedigree into rapid reformulation cycles under stricter environmental regimes.
-
Indium Corporation (Clinton, NY): positions itself on halogen‑free and high‑reliability solutions, recently recognized via multiple industry awards for new product introductions. Indium’s cadence of innovation and external validation via awards underpin a go‑to‑market narrative focused on high‑performance segments (reflow, rework, and advanced packaging).
-
MG Chemicals (Vancouver): emphasizes practical, application‑centered paste formulations designed for both lead‑free and legacy alloys, marketed through strong distributor relationships. Their advantage lies in pragmatic product design and accessibility for small to mid‑scale assemblers.
Collectively, these profiles illustrate two clear strategic vectors in 2026: (1) larger vendors leverage scale to manage reformulation and compliance costs; (2) agile specialists capture share in performance‑differentiated niches through targeted product wins and channel partnerships. Recent product launches and awards, particularly those by Indium Corporation in late 2025 and early 2026, validate the commercial impact of innovation-led strategies.
What our full report contains — practical tools for executives
The complete PW Consulting Soldering Flux Paste Market report is designed as an operational playbook for 2026. Highlights include:
-
Market sizing and validated historical series (2020–2025), with base‑year reconciliations and methodology transparency.
-
Forecast models (2026–2032) built on scenario‑based assumptions (baseline, accelerated adoption, and downside regulatory shock), including sensitivity tables executives can adapt to corporate inputs.
-
Segmentation frameworks by region, product type, and application — with a cell‑level taxonomy, growth levers, and served‑available market (SAM) overlays. Note: in this briefing we intentionally withhold detailed numeric splits to preserve the report’s commercial value and to encourage direct access to our interactive datasets.
-
Competitive teardown: strategic profiles, technology scorecards, patent landscape snapshots, and recent M&A and innovation activity timelines.
-
Margin and pricing playbooks: formulation cost models, pass‑through levers, and recommended hedging instruments for commodity exposure.
-
Regulatory compliance matrix: jurisdictional mapping of VOC/hazard restrictions, reformulation roadmaps, and recommended testing protocols to accelerate time‑to‑market for compliant chemistries.
-
Actionable go‑to‑market templates: distributor evaluation scorecards, sample contract clauses to manage raw material price volatility, and prioritized investment roadmaps (R&D, automation, quality assurance).
Strategic recommendations for 2026 (clear, actionable)
-
Prioritize reformulation projects now: allocate >60% of near‑term R&D capacity to low‑VOC and halogen‑free chemistries where your customer base includes high‑reliability electronics. The regulatory timeline and customer qualification cycles mean decisions made in 2026 determine commercial access in 2027–2028.
-
Hedge critical inputs: implement a dual approach of financial hedging for refined tin exposure and operational hedging via multi‑sourcing agreements and inventory strategies. Our models quantify the cost of delayed hedging under realistic price scenarios.
-
Segment the portfolio: adopt a two‑tier product architecture — a premium performance line for advanced packaging and high‑reliability SMT, and a value line optimized for cost‑sensitive industrial applications. Tailored go‑to‑market plans will protect margins while capturing volume growth.
-
Deploy fast‑track qualification pilots: partner with lead customers on pilot lines to accelerate qualification of reformulated pastes; offer co‑validation incentives to shorten adoption cycles and defensibly raise switching costs.
-
Monitor consolidation and opportunistic M&A: with a moderately concentrated market structure, strategic acquisitions of niche formulators or regional players can deliver rapid access to compliant chemistries, local certifications, and distribution networks at favorable multiples.
-
Invest in sustainability and transparency: ESG‑aligned product declarations and lifecycle assessments are increasingly procurement table stakes. Early adoption creates differentiation and reduces future compliance liabilities.
How to act on these insights
PW Consulting’s full deliverable contains the datasets, worksheets, and strategic playbooks needed to operationalize the recommendations above. We intentionally present a high‑value preview here — showing the analytical scaffolding and strategic implications — while reserving the granular segmentation numbers, downloadable Excel forecast models, and supplier scorecards for the full report package. This ensures decision teams get both rigorous analysis and executable outputs tailored to corporate assumptions.
Closing perspective
The soldering flux paste market presents a classic 2026 strategic dilemma: predictable, mid‑single‑digit growth at the macro level, coupled with asymmetric risks at the input and regulatory level. Companies that synchronize reformulation investments, procurement resilience, and targeted commercial strategies will convert steady market expansion into durable competitive advantage. PW Consulting’s Soldering Flux Paste Market report equips executives with the evidence‑based scenarios, commercial tools, and competitor intelligence to make those decisions with confidence.
Next steps
For access to the full report, including downloadable models and proprietary segmentation tables, visit our report page or contact PW Consulting’s industrial materials practice. Our team is available to run a tailored briefing and to translate report outputs into an implementation plan customized to your organization’s 2026 priorities.
For detailed analysis of this topic, please visit the official page: Soldering Flux Paste Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com