

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Chemical Milling Market to Grow from USD 126.0 Million in 2025 to USD 188.85 Million by 2032 at a 6.0% CAGR, Led by Aerospace

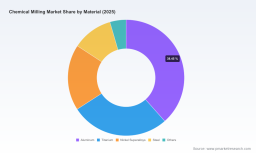
PW Consulting Releases Strategic Brief: Chemical Milling Market Outlook to 2032 — A Tactical Guide for 2026 Decision-Makers
As aerospace, defense, medical, and high-precision industrial supply chains recalibrate for a period of steady demand and accelerating regulatory scrutiny, PW Consulting today publishes a focused strategic briefing derived from our full Chemical Milling Market report. The briefing synthesizes macro growth dynamics, regulatory pressure points, supplier positioning, and the practical playbooks procurement, operations and corporate development teams will need to act confidently in 2026. This release is written to demonstrate the depth of insight available in the full study while reserving the detailed segment-level intelligence for subscribers and report purchasers.
Chemical Milling Market
Market Snapshot: Growth Trajectory and Structural Characteristics
Using 2025 as the base year, the chemical milling market has demonstrated resilient expansion through the first half of the decade and is forecast to continue this trajectory through 2032. Our high-conviction scenario projects a compound annual growth rate (CAGR) of approximately 6.0% over the 2026–2032 forecast window. Measured on a total-market basis, the market has expanded materially from the start of the historical series to the 2025 base year and is projected to reach a substantially larger market size by 2032.
Chemical Milling Market
Two structural features deserve emphasis for 2026 planners:
Chemical Milling Market
- Moderate consolidation at the supplier level: concentration metrics indicate that the top three and top five suppliers account for a majority share of market revenue, creating a competitive environment where scale, accreditation, and value-added services are differentiators.
- Cost and compliance exposures that disproportionately affect facilities performing advanced alloys and aerospace-qualified work — these exposures shape capital allocation, pricing frameworks, and supplier selection strategies.
Why this matters for 2026 decisions
For executive teams setting budgets and go-to-market strategies in 2026, the chemical milling sector presents a mix of organic growth opportunities and non-trivial risk factors. The report translates this mix into six immediate implications:
- Accreditation as a de facto market access cost: NADCAP and equivalent aerospace accreditations have moved from “nice-to-have” to a gating factor in many OEM supply chains. Accreditation carries both margin upside (recognized price premiums in aerospace programs) and baseline investment requirements — manufacturers should assume accreditation-related cost and timetable impacts when evaluating suppliers or greenfield investments.
- Regulatory tightening requires CAPEX and operational re-engineering: Environmental regulation on hazardous chemistries (including HF and other aggressive etchants) is increasing. Facility compliance upgrades should be budgeted as discrete projects; our modelling shows compliance-driven capital expenditures can range materially depending on facility scale and the alloys processed.
- Material mix drives unit economics: Processing titanium and nickel-based alloys requires different chemical systems, safety protocols and disposal streams compared with aluminum. These differences translate to higher per-unit-area costs and different margin profiles. Commercial strategies that ignore material-driven cost variation risk margin compression when pursuing premium alloy work.
- Specialization and value-added services win in consolidation: Scale alone is insufficient. Providers that bundle NADCAP credentials, finished-part inspection, machining co-processing, and just-in-time logistics command positioning advantages across aerospace and defense programs.
- Pricing dynamics will bifurcate: The market is likely to sustain premium pricing for accredited, high-alloy work while preserving competitive pressure on commoditized aluminum processing. Procurement teams should model dual-sourcing strategies to reconcile cost control with program risk mitigation.
- M&A and partnerships as rapid-capability levers: Given the moderate market concentration and capital intensity of compliance upgrades, strategic acquisitions or long-term partnerships are an efficient route to buy capability, accreditation, and customer access.
What’s in the full PW Consulting report (practical, action-oriented deliverables)
Our full study is designed to be immediately operational for corporate, procurement and technical stakeholders. Key deliverables include:
- Market sizing and a validated growth model (historical analysis and base-year anchoring), including alternative scenarios and sensitivity testing to raw material and regulatory shocks.
- Regulatory impact models that quantify capital and operating cost ranges associated with hazardous-chemical compliance upgrades, emissions control, and accreditation maintenance.
- End-to-end supplier capability matrices and a vendor shortlisting tool that allows buyers to rank providers by accreditation, alloy capability, lead times, and service bundling.
- Unit-cost templates and break-even calculators tailored to aluminum, titanium, and nickel-based alloy processing to support sourcing and make-vs-buy decisions.
- Commercial playbooks: procurement negotiation checklists, contract structures that insulate buyers from compliance cost pass-through, and pricing-index recommendations for long-term agreements.
- M&A and inorganic growth playbooks highlighting target criteria, integration risks, and typical valuation levers in the chemical milling sector.
- Technology and operations roadmap covering photochemical machining, micro-laser finishing, closed-loop effluent systems, and discrete automation adoption patterns.
- Appendices with supplier profiles, NADCAP and equivalent accreditation scoring, and a catalogue of data points used in our models (available to subscribers).
Note: the report purposefully reserves the granular, segment-level revenue tables and share breakdowns for the data appendix and subscriber portal; high-level conclusions and tactical templates are included to enable immediate action while protecting proprietary segmentation intelligence.
Competitive Landscape — Strategic Profiles & Tactical Takeaways
The market is populated by a blend of specialized boutique processors and larger aerospace-focused finishers. Representative profiles and strategic observations include:
- Valence Surface Technologies (United States) — https://www.valencesurfacetech.com/ PW Consulting view: A broad-spectrum aerospace metal finishing provider with deep chemical milling capability across common aerospace alloys. Strengths include large-program delivery experience and end-to-end processing. Strategic advice for competitors and customers: assume premium pricing for accredited aerospace services and build contingency plans if supplier single-source exposure exists.
- Tech Met, Inc. (Glassport, PA, United States) — https://www.techmetinc.com/ PW Consulting view: A NADCAP-accredited precision miller serving high-reliability sectors. Tech Met exemplifies the premium that accreditation and precision process controls command. For buyers, this type of supplier is a logical choice for flight-critical and medical components.
- MET Manufacturing Group, LLC; Etchit; VACCO Industries; Great Lakes Engineering — https://metaletching.org/ (corporate pages) PW Consulting view: These firms illustrate the diversity of capability in the market — from photo-chemical etching of thin components to precision stencil and micro-feature production. Their competitive positioning is strongest where process specialization and value-added finishing are required.
- Ducommun Structural Systems Group (United States) — https://www.ducommun.com/structuralsolutions/chemMill.aspx PW Consulting view: A provider focused on complex structural parts with demonstrated capability in weight-reductive chemical milling for aerospace structures. Ducommun’s offering highlights the persistent demand for chemical milling as a design-enabling technology for structural optimization.
Across these profiles, PW Consulting’s analysis emphasizes an important dynamic: accreditation, process breadth, and integrated finishing services are the strongest predictors of supplier resilience and customer willingness to pay premiums. Concentration metrics show measurable advantage for top-tier providers, but opportunity exists for nimble specialists that can demonstrate validated processes and regulatory compliance.
Regulatory & Raw-Material Dynamics — The Cost Drivers Shaping Strategy
Three operational realities should be embedded into every 2026 planning exercise:
- NADCAP accreditation is operationally decisive in aerospace supply chains and is reflected in price negotiation outcomes; accredited providers frequently achieve meaningful price premiums relative to non-accredited peers.
- Titanium and other high-performance alloys require more aggressive etchants and enhanced controls, producing a significant increase in per-unit processing cost versus conventional aluminum workstreams. Buyers and providers must model these premiums explicitly rather than assuming linear cost scaling.
- Environmental regulation is tightening in many jurisdictions. Facility compliance upgrades — from containment and effluent treatment to monitoring and training — are non-trivial capital and operating commitments that materially affect supplier cost structures and, by extension, contract pricing.
These factors are quantified and stress-tested in our full report; readers seeking to understand the specific CAPEX ranges, margin impacts, and payback timelines for different plant footprints should consult the detailed regulatory and cost modelling sections.
How to use this briefing to shape 2026 actions
PW Consulting recommends four immediate steps for stakeholders preparing budgets and strategies in 2026:
- Integrate accreditation risk into supplier selection: require NADCAP (or equivalent) evidence for aerospace programs and price-risk clauses for accreditation maintenance.
- Run a targeted CAPEX review for any owned chemical milling lines processing hazardous chemistries; incorporate regulatory upgrade scenarios into 2026–2028 capital plans.
- Segment procurement by material/alloy economics and establish differentiated sourcing streams for aluminum versus titanium/nickel processing.
- Evaluate M&A or alliance options to accelerate access to accredited capacity or to acquire specialist etching capability that improves lead times and margin capture.
Next steps & how to obtain the full study
The full PW Consulting Chemical Milling Market report contains the proprietary segmentation tables, supplier scorecards, scenario models, and downloadable tools referenced here. For teams that must make sourcing decisions, capital-allocation choices, or M&A moves in 2026, the full report converts hypothesis into executable plans.
To access the complete analysis, including the detailed data appendices and vendor due-diligence templates, please visit the PW Consulting publications page (report access and subscription details are available online). Our advisory practice is also available for bespoke modeling, supplier diligence, or transaction support engagements.
PW Consulting remains committed to delivering actionable industry intelligence that balances transparency with the confidentiality our clients require. This briefing outlines the strategic priorities for 2026; the full report provides the operational maps and financial models to realize them.
For detailed analysis of this topic, please visit the official page: Chemical Milling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com