

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 1,8‑Diaminonaphthalene Market Set to Grow at 6.5% CAGR During 2026–2032

1,8-Diaminonaphthalene Market — Strategic Intelligence Brief for 2026 Decision-Makers
PW Consulting's new market study on 1,8-diaminonaphthalene (1,8-DAN) delivers a focused, actionable compass for executives, investors, and procurement leaders preparing strategic moves in 2026. The report synthesizes a decade of market behavior with a forward-looking forecast, combining proprietary modeling, supplier benchmarking, and regulatory-risk mapping to translate chemical-market complexity into high-confidence choices. This brief previews the report’s strategic value while deliberately withholding granular segment-level datapoints to encourage direct engagement with the full analysis.
1,8-Diaminonaphthalene Market
Why 1,8-DAN merits board-level attention in 2026
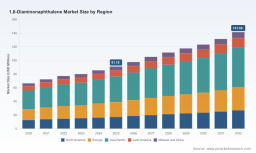
1,8-DAN is a small but strategically important intermediate: a building block for dyes, pigments, and pharmaceutical syntheses. The total market has demonstrated steady expansion through the 2020–2025 base period and, under our central forecast, continues to grow at a compound annual growth rate (CAGR) of 6.5% across 2026–2032. To put that in operational perspective, the market size measured in our base-year accounting rises from a mid-double-digit Million USD footprint in 2020 to a projected six-point larger Million USD figure by 2032, reflecting resilient end-market demand and pricing dynamics.
1,8-Diaminonaphthalene Market
For procurement directors, R&D heads and CEOs, that trajectory signals two concurrent realities: first, the addressable market is large enough to justify investment in supply security and quality differentiation; second, growth is not uniform — it is driven by specific grades, customer segments and regulatory-driven demand for higher-purity material. The consequence is that a one-size-fits-all supply strategy will leave margin and innovation value on the table.
1,8-Diaminonaphthalene Market
Key strategic takeaways
- Lock in quality-sensitive supply for specialty demand: Pharmaceutical- and specialty-chemical consumers increasingly require ultra-high-purity grades and full regulatory traceability. Buyers should prioritize suppliers with integrated naphthalene chemistry platforms and GMP-capable facilities, and embed long-term quality KPIs into contracts.
- Hedge raw-material and freight exposure: Naphthalene spot and contract prices have firmed, with notable month-on-month volatility in Northeast Asia, Europe and India through mid-2026. Given the commodity’s direct impact on input cost, scenario-based hedging and index-linking clauses can materially protect margins.
- Regulatory and logistics risk become commercial differentiators: Classification under transport and chemical safety frameworks requires specific documentation and handling. Manufacturers that have invested in compliance and export-quality documentation will be preferred partners, particularly for cross-border pharmaceutical supply chains.
- Identify consolidation and partnership opportunities: The market shows a relatively concentrated supplier structure; strategic M&A or offtake agreements with top industrial producers can secure scale advantages and shorten time-to-volume for product development.
What the full PW Consulting report contains (practical highlights)
- Proprietary market-sizing and trend model covering 2020–2032 with bottom-up verification and scenario runs for upside and downside demand paths.
- Supplier scorecards and capability maps that assess manufacturing route (solvent-free, integrated naphthalene platforms), purity capability, regulatory readiness, and service levels.
- Commercial playbook for procurement, including contract templates, price-index design options, and supplier segmentation for dual-sourcing versus single-sourcing strategies.
- Regulatory and logistics playbook detailing classification, packaging, and cross-border documentation requirements for major trading corridors, plus a compliance-cost estimator.
- Investment & capacity planning tool showing how incremental capacity or modernization investments translate to market share and margin outcomes under multiple price and demand scenarios.
- Risk heatmaps and mitigation options centered on raw material shocks, export controls, and supply interruptions—presented with estimated financial impacts to EBITDA for typical user-company profiles.
These deliverables are designed to be executable: the report does not end at insight but provides templates, checklists and financial-statement level sensitivity tables to accelerate board-level decision cycles in 2026.
Competitive landscape — who matters and why
The commercial topology of the 1,8-DAN market blends global chemical majors, regional champions and specialized Chinese producers. Three dynamics dominate competitive positioning: technological differentiation (purity and route), scale and vertical integration, and regulatory/service capability for cross-border pharmaceutical supply.
- BASF SE (Ludwigshafen, Germany; https://www.basf.com) — BASF’s integrated naphthalene chemistry and ultra-high-purity output position it as the preferred partner for pharmaceutical-grade intermediates. Their capability to deliver 99.8%+ specification material and to integrate quality documentation into supply contracts makes them a natural counterparty for customers prioritizing regulatory defensibility.
- Huntsman Corporation (The Woodlands, TX, US; https://www.huntsman.com) — Huntsman’s offering is oriented toward lower-purity grades optimized for azo dye precursor use. Their strategic strength lies in integrating 1,8-DAN into broader textile-colorant value chains, enabling cost and logistics synergies for large dye houses.
- Lanxess AG (Cologne, Germany; https://www.lanxess.com) — Lanxess blends pharmaceutical-grade production with a diversified specialty portfolio and GMP-capable manufacturing. Their flexibility across grades allows them to serve both regulated pharma supply chains and high-value specialty chemistries.
- Solvay S.A. (Brussels, Belgium; https://www.solvay.com) — Solvay differentiates through technical capabilities in naphthalene-based intermediates and is focused on specialty applications that require tailored performance characteristics and technical support.
- Evonik Industries AG (Essen, Germany; https://www.evonik.com) — Evonik’s core value is technical service and customer-specific optimization—critical for formulators who require minor but performance-critical tweaks to 1,8-DAN-derived intermediates.
- Chinese and regional producers (e.g., Nantong Haidi, Jining Jintai Lihua, Nantong Longxiang, Ningbo Inno Pharmchem, Henan New Blue, Sarna Chemicals) — These players deliver scale, cost-competitive bulk supply and increasingly, high-purity variants. Notably, one major Chinese producer has established a significant share of global revenue and continues to invest in refined pharmaceutical-grade variants and production automation.
Competitive moves to watch in 2026 include capacity modernization (automation to lift yield and reduce impurity profiles), product differentiation toward higher-solubility pharmaceutical variants, and supplier consolidation through strategic partnerships or M&A.
Recent industry developments that change the calculus
- Product innovation: In late 2024, a leading Chinese manufacturer launched a refined pharmaceutical-grade 1,8-DAN variant with improved solubility and tighter purity specs — a clear signal that upstream producers are moving up the value chain into pharma intermediates.
- Capacity and automation: A Jiangsu-based producer increased line efficiency substantially via automation in 2023, demonstrating that productivity plays and digitalization materially shift unit economics for high-purity production.
- Raw-material trends: Naphthalene price movements across key sourcing regions have firmed into 2026, driven by downstream demand from dye intermediates. This dynamic increases the importance of input-cost management and pass-through mechanisms in commercial contracts.
- Regulatory and transport constraints: 1,8-DAN’s classification under chemical safety and transport frameworks imposes specific documentation and packaging obligations, while REACH and similar substance-evaluation regimes increase compliance costs for suppliers serving regulated markets.
Concrete actions for executives in 2026
- Procurement: Execute a two-tier sourcing strategy: secure at least one GMP-capable supplier for regulated applications and one cost-competitive bulk supplier for industrial volumes. Negotiate multi-year offtake agreements with indexation to naphthalene or a blended cost formula to stabilize margins.
- R&D and product development: Prioritize formulation work that exploits higher-purity 1,8-DAN variants (e.g., improved solubility grades) to reduce downstream processing or raise product performance thresholds.
- Regulatory/compliance: Audit suppliers’ transport and export documentation practices and require supplier-side certification for cross-border shipments; this reduces shipment rejections and time-to-market delays for pharmaceutical intermediates.
- Corporate development: Assess targeted bolt-on acquisitions or long-term joint ventures with regional manufacturers that have automation and scale—this can be the fastest path to secure feedstock and capacity for differentiated grades.
- Finance: Run scenario stress-tests that combine raw-material price shocks with delayed capacity ramp-up; model the impact on gross margins and working capital to inform covenant negotiations and capex timing.
Why PW Consulting’s study is the right tool for 2026 decisions
The study is intentionally constructed to bridge technical chemical knowledge and board-level commercial strategy. Our integrated deliverables—market-size modeling, supplier scorecards, and executable procurement and compliance templates—reduce the time from insight to decision. We provide a balanced view of growth opportunities and operational risks so that leadership teams can prioritize investments with quantified ROI under multiple market scenarios.
Note: This preview highlights the report’s strategic contours. Detailed regional and application-level splits, supplier-specific volume and pricing models, and downloadable contract templates are available only in the full PW Consulting report. Those elements contain the granular intelligence required to execute sourcing strategies and capital plans in 2026 and are intentionally withheld here to protect proprietary model outputs and to encourage direct engagement with our advisory team.
Next steps
- Contact PW Consulting for an executive briefing tailored to your company’s exposure to 1,8-DAN (supply risk, purity requirements, and contract strategy).
- Request a demo of our supplier-scorecard dashboard and the investment sensitivity tool to run your company’s P&L through 2032 scenarios.
- Commission a focused due-diligence package if considering partnership or acquisition targets among the leading producers identified in this brief.
In a market characterized by steady growth, rising raw-material pressure, and tightening regulatory expectations, the decisive advantage in 2026 will go to companies that combine supplier selectivity, contractual intelligence and targeted product development. PW Consulting’s 1,8-Diaminonaphthalene Market study equips leadership teams to make those decisions with precision.
For detailed analysis of this topic, please visit the official page: 1,8-Diaminonaphthalene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com