

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 1,2,3,4-Butanetetracarboxylic Acid (CAS 1703-58-8) Market to Reach USD 226.3 Million by 2032, Expanding at a 6.3% CAGR (2026–2032)

Strategic Outlook: 1,2,3,4-Butanetetracarboxylic Acid (CAS 1703-58-8) — A 2026 Decision Playbook
PW Consulting’s newest market research release on 1,2,3,4-Butanetetracarboxylic Acid (BTCA, CAS 1703-58-8) is designed as an operational compass for executives making capital, procurement, and product strategy decisions in 2026. Drawing on a five‑year historical base (2020–2025) and an actionable forecast window (2026–2032), the study blends quantitative trajectory modeling with practical supply‑side intelligence to convert market signals into measurable business moves.
1,2,3,4-Butanetetracarboxylic Acid (CAS 1703-58-8) Market
Why this market matters to your 2026 roadmap
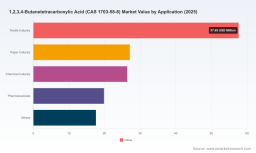
BTCA is a specialist chemical whose demand profile intersects textile finishing, polymer cross‑linking, pharmaceutical intermediates, and several industrial chemistries. Between 2020 and 2025 the addressable market expanded from approximately USD 113.2 Million to USD 148.6 Million (base year 2025), reflecting steady adoption across application areas and the emergence of higher‑purity use cases. Our forecast models — anchored on a 6.3% compound annual growth rate for the 2026–2032 period — project continued expansion, bringing the market to roughly USD 226.3 Million by 2032 under the baseline scenario.
1,2,3,4-Butanetetracarboxylic Acid (CAS 1703-58-8) Market
For decision makers, that growth profile is a signal: the market is large enough to merit dedicated sourcing strategies and small enough that supplier concentration and purity segmentation materially affect margin, supply risk, and product positioning. The report translates these macro dynamics into concrete, prioritized actions for procurement, manufacturing, and R&D leaders.
1,2,3,4-Butanetetracarboxylic Acid (CAS 1703-58-8) Market
What the PW Consulting report delivers (practical, not theoretical)
- Proprietary market-sizing model: a reproducible financial model spanning 2020–2032, calibrated to product purity tiers, application demand drivers, and price dynamics.
- Supply‑chain intelligence pack: supplier mapping, plant footprints, lead‑time baselines, export patterns, and a risk matrix for regulatory and logistics disruption.
- Commercial playbooks: three buyer personas (volume manufacturer, specialty compounder, and research supplier) with tailored sourcing and contracting templates.
- Scenario toolkit: base, upside, and downside demand cases with triggers, sensitivity tables, and decision thresholds for CAPEX timing and inventory hedging.
- Regulatory and sustainability checklist: compliance requirements, likely inspection vectors, and a staged roadmap to meet emerging environmental and purification standards.
- Technology and purity roadmap: assessment of process improvements, purification trade‑offs, and how purity tiers translate into margin and application eligibility.
- Executive dashboards: downloadable datasets and KPIs designed for rapid integration into procurement and strategy meetings (note: detailed segment-level datasets and region/application splits are accessible in the full report).
Competitive landscape — who matters and why
Market supply is dominated by a mix of large global chemical suppliers and a substantial number of China‑based manufacturers. This structure creates a strategic tension: global suppliers offer brand, traceability, and high‑purity research grades, while regional producers frequently provide cost flexibility and manufacturing scale for industrial uses. PW Consulting’s analysis profiles each relevant player and assesses their strategic posture across three dimensions: product purity capability, export and distribution reach, and operational compliance (e.g., ISO 9001 or equivalent).
- Autech Industry (Jinan, Shandong, China) — positioned for textile finishing and polymer synthesis with high‑purity offerings and targeted industrial sales channels. ( https://www.autechindustry.com)
- Qingdao Jinyu Chemical Co., Ltd. (Qingdao, Shandong, China) — exporter and manufacturer with high‑solubility crystalline products suited to industrial applications. ( https://qdjychemical.en.made-in-china.com)
- Sinochem Nanjing Corporation (Nanjing, Jiangsu, China) — corporate supplier with institutional capabilities and compliance credentials. ( https://www.sinochem-nanjing.com)
- Hebei Chuanghai Biotechnology Co., Ltd. (Hebei, China) — supplier focused on high‑purity grades. ( https://www.chemicalbook.com)
- Hefei TNJ Chemical Industry Co., Ltd. (Hefei, Anhui, China) — export network and manufacturing scale in specialty chemicals. ( https://www.tnjchem.com)
- Shanghai UCHEM Inc. (Shanghai, China) — bulk supplier of high‑purity crystalline powder. ( http://www.myuchem.com/)
- ANHUI WITOP BIOTECH CO., LTD (Anhui, China) — biotech‑grade focus for specialized applications. ( https://www.chemicalbook.com)
- Yangzhou Model Electronic Materials Co., Ltd. (Yangzhou, Jiangsu, China) — niche supplier for specialty material uses. ( https://www.modeltemol.com)
- Wuhan Fortuna Chemical Co., Ltd (Wuhan, Hubei, China) — domestic producer with export capabilities. ( http://www.fortunachem.com/)
- Guangzhou TongYi Biochemistry Technology Co., LTD (Guangzhou, Guangdong, China) — variety of purity and packaging options. ( http://tongyon.com/)
- Amadis Chemical Company Limited (Shanghai, China) — research and industrial grades supplier. ( http://www.amadischem.com)
- Sigma‑Aldrich (Merck KGaA) (St. Louis, Missouri, USA) — global supplier of research-grade BTCA. ( https://www.sigmaaldrich.com)
- Thermo Fisher Scientific (Alfa Aesar) (Waltham, Massachusetts, USA) — cross‑linking and polymer‑grade supplier. ( https://www.thermofisher.com)
- Santa Cruz Biotechnology, Inc. (Dallas, Texas, USA) — supplier for biochemical and research markets. ( https://www.scbt.com)
Our competitive assessment shows a moderately concentrated supplier base where a small group of producers accounts for a substantial portion of available capacity. That concentration creates both bargaining power for large buyers and supply risk for those without diversified sourcing. In practice, the market dynamics favor buyers who combine long‑term agreements with multi‑sourcing and quality auditing programs.
Key strategic implications for 2026 (what to act on now)
- Prioritize purity optimisation. With value increasingly tied to higher‑purity grades in specialty applications, R&D and procurement must align on acceptable purity bands and associated price‑to‑performance trade‑offs.
- Design layered sourcing. Combine a primary long‑term supplier with secondary regional partners to manage lead times and geopolitical exposure. Include formal audit plans and quality release protocols.
- Embed scenario triggers into CAPEX decisions. Use the report’s scenario toolkit to set go/no‑go thresholds for capacity expansions, balancing the baseline 6.3% CAGR with upside demand triggers.
- Negotiate conditional pricing clauses. Given volatility in feedstocks and logistics, tie multi‑year contracts to clear indices and fluorescence points to protect margins without sacrificing supply security.
- Invest in downstream formulation competence. For firms seeking premium positioning, marginal improvements in formulation and application knowledge unlock price premiums that outstrip raw material cost increases.
- Account for compliance and ESG. Environmental controls and product stewardship are rising procurement criteria among global buyers; early compliance investments reduce future retrofit costs and protect market access.
Risk map — what keeps us awake
Our stress tests identify a handful of high‑impact risks: feedstock and precursor price volatility, regulatory tightening around chemical processing and emissions, logistics bottlenecks affecting export flows, and consolidation among regional suppliers. Any one of these can compress margins or create temporary shortages. The PW Consulting report provides mitigation playbooks for each risk, including inventory strategies, supplier development programs, and legal clauses for force majeure and price pass‑through.
How to use the report in boardroom debates and procurement negotiations
- Shortlist suppliers using a fit‑for‑purpose matrix: purity capability, lead times, certification status, export track record, and contingency capacity.
- Translate the macro trajectory into budget lines: use the report’s revenue and price scenarios to stress test three‑year procurement budgets and CAPEX requests.
- Leverage scenario triggers in supplier contracts: establish renegotiation points tied to realized market growth, major regulatory changes, or raw material cost bands.
- Deploy a two‑tier inventory policy: strategic safety stock for continuity vs. tactical stock for opportunistic pricing capture during downturns.
Final note — the trailer principle in practice
This briefing is intentionally directional: it furnishes the high‑value insights executives need to reframe strategy heading into 2026 while withholding the detailed segment and regional matrices that are central to tactical execution. Those granular splits — purity tiers by application, region‑level consumption patterns, and per‑supplier capacity tables — are included in the full PW Consulting report and interactive datasets available on our report page.
For procurement leaders, R&D heads, M&A teams, and strategy officers, the full report provides the executable intelligence required to convert the projected market growth and supplier dynamics into measurable competitive advantage. If you are preparing sourcing strategies, negotiating long‑term agreements, or sizing production investments for 2026 and beyond, this research furnishes the models, templates, and supplier profiles to move from analysis to action.
Access and next steps
- Review the executive summary and scenario dashboards to align leadership on risk tolerance and investment timing.
- Engage PW Consulting for a tailored supplier due‑diligence package or a customized sensitivity analysis tied to your cost structure.
- Download the full datasets and decision templates from our report page to integrate into your procurement and capital planning cycles.
Pursue the full report to unlock the segment‑level intelligence and supplier KPIs that will be decisive in 2026 procurement and investment decisions. PW Consulting’s BTCA market study is built to convert market foresight into boardroom outcomes — rigorous, actionable, and ready to inform your next move.
For detailed analysis of this topic, please visit the official page: 1,2,3,4-Butanetetracarboxylic Acid (CAS 1703-58-8) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com