

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: L‑Menthol Market to Rise from USD 224 Million in 2025 to USD 306 Million by 2032 at 4.5% CAGR — Asia‑Pacific, Natural Grade (USD 150M) and Food & Beverage Lead; Top‑5 Hold 65%

PW Consulting: L‑Menthol Market — Strategic Imperatives for 2026 Decision‑Makers
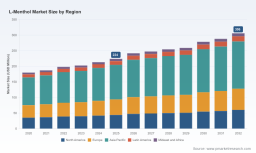
As global supply chains recalibrate and sustainability becomes a non‑negotiable procurement criterion, the L‑Menthol market is entering a phase of steady expansion and structural realignment. PW Consulting’s new market study, anchored on base year 2025 with a forecast horizon of 2026–2032, quantifies that trajectory: the global market has expanded from roughly USD 180 Million in 2020 to about USD 224 Million in 2025, and is projected to reach approximately USD 306 Million by 2032, reflecting a compound annual growth rate of 4.5% through the forecast period. For executives planning 2026 capital allocation, commercial strategy, or M&A activity, the study provides an evidence‑based roadmap tuned to both cyclical agricultural risk and structural demand shifts.
L-Menthol Market
Why 2026 Is a Pivotal Planning Year
Two converging forces make 2026 a decision point rather than a routine planning cycle. First, demand composition is shifting: regulatory moves and consumer preferences have reduced the predictability of certain legacy channels while amplifying demand in pharmaceutical, personal care, and premium food & beverage segments. Second, upstream volatility remains high. Historical mint oil price swings and seasonal crop variability have repeatedly translated into supply squeezes and margin pressure. These dynamics favor actors with integrated supply options, verified quality systems, and clarity on sustainability claims. Our report converts these high‑level realities into executable choices for 2026 board agendas.
L-Menthol Market
Executive Takeaways: What Every Board Should Know
- Growth is predictable but segmented: The total market size shows steady expansion at a mid‑single digit CAGR through 2032, yet growth is uneven by application and by procurement model. Firms that anticipate where premiumization and regulatory displacement will occur will capture disproportionate share.
- Supply resilience is now a strategic capability: Agricultural seasonality and historically large year‑on‑year price fluctuations for mint derivatives make single‑source or spot‑heavy purchasing strategies risky. Companies that blend synthetic capacity access, forward contracting, and geographically diversified natural sourcing will reduce earnings volatility.
- Sustainability claims are commercial levers: Product launches that quantify reduced product carbon footprints are no longer marketing curiosities; they command procurement preference in pharma and premium CPG applications. Expect sustainability credentials to influence supplier selection and price concessions in 2026.
- Market concentration leaves room for consolidation plays: The top three suppliers account for a material share of global supply, and the top five control an even larger portion. This concentration creates both pricing power for incumbents and arbitrage opportunities for agile challengers through targeted M&A or capacity investments.
Market Dynamics: Drivers, Risks, and Near‑Term Inflection Points
Our findings identify a handful of dynamics that will determine winner/loser scenarios over the next 18–36 months:
L-Menthol Market
- Regulatory displacement of legacy demand: Public health regulations and proposals (notably actions targeting menthol as a characterizing tobacco flavor) have introduced demand uncertainty in tobacco applications but concurrently accelerated reallocation into pharmaceutical and personal care channels. Firms with pharmaceutical‑grade capabilities and validated regulatory dossiers are positioned to capture that uplift.
- Raw material volatility and seasonal constraints: Natural L‑menthol supply remains sensitive to crop cycles and mint oil prices, which have historically swung 25–40% during stressed years. Buyers without buffering strategies face sudden cost jumps or forced formulation changes.
- Rise of synthetic and bio‑based production: Several global producers operate large synthetic L‑menthol plants that offer scale, shorter lead times, and retest‑backed shelf stability—advantages in the face of natural supply intermittency. Simultaneously, manufacturers are launching biobased grades with recognized pharmacopeial specifications to bridge sustainability demands with industrial reliability.
- Sustainability as procurement filter: The market is already responding: leading ingredient producers introduced reduced‑product‑carbon‑footprint L‑menthol grades in 2025. Buyers in regulated and premium sectors increasingly require quantified environmental claims and traceability, elevating the cost of non‑compliance.
Competitive Landscape — What the Leading Players Signal
The competitive map is a mix of large multinational chemical and flavour houses with fully backward‑integrated synthetic platforms, and specialist producers rooted in natural mint supply chains. Key market actors demonstrate two dominant strategic postures: scale + integration on the synthetic side, and certification + supply proximity on the natural side.
- BASF SE (Ludwigshafen, Germany) — operates as one of the largest synthetic L‑menthol producers through a dedicated facility, offering pharmaceutical‑grade formats with extended retest stability and a backward‑integrated supply model that buffers crop risk. Its April 2025 launch of an L‑menthol variant with a reduced product carbon footprint is an early indicator of how incumbents will use sustainability to defend premium segments.
- Symrise AG (Germany/USA) — historically the first to scale synthetic L‑menthol production, Symrise demonstrates that repeated capacity expansions are a tactical response to structural demand growth in non‑tobacco applications.
- Takasago International (Japan) — a leader in chiral synthetic routes and in delivering pharmacopeial‑grade materials at scale; continued emphasis on biobased grades shows how technical differentiation can coexist with volume leadership.
- Natural‑focused suppliers — several specialist producers across North America, India, and China continue to supply certified natural L‑menthol crystals for food and pharma. Their value proposition centers on natural‑claim documentation, local supply relationships, and price competitiveness when crop conditions are benign.
Importantly, the market is neither atomized nor monopolistic. The top three suppliers control a meaningful share of supply, and the top five widen that concentration further. That structure supports price discipline among incumbents but also rewards new entrants that can deliver certified differentiation or guaranteed volume under long‑term commercial contracts.
What the PW Consulting Report Contains (Practical, Transactional, and Operational Deliverables)
This report is designed as an operational playbook for 2026 decisions rather than a high‑level commentary. Key inclusions:
- Market sizing and a transparent forecast model anchored on 2025 base data and a 2026–2032 outlook, including scenario and sensitivity analyses around raw material shocks and regulatory outcomes.
- Supply chain maps and risk heatmaps that identify single‑points‑of‑failure, lead‑time bottlenecks, and cost levers across natural and synthetic routes.
- Commercial playbooks for buyers and suppliers: negotiation frameworks, contract structures (indexation, volume floors, and evergreen clauses), and pricing pass‑through templates.
- Due diligence checklists and valuation comparables tailored to M&A in a concentrated supplier market, plus an annex of likely acquisition targets based on capability gaps and regional exposure.
- Regulatory and sustainability trackers that translate emerging rules and rPCF claims into practical compliance actions and go‑to‑market narratives.
- Company profiles and capability matrices for the major players, with signals for partnership, competitive threat, and acquisition rationale.
Actionable Recommendations for 2026 Plans
Translate market intelligence into prioritized actions for the coming fiscal year:
- Secure optionality: Institute a blended sourcing strategy that pairs strategic long‑term agreements with synthetic manufacturers and spot access to certified natural suppliers to mitigate seasonal shortages.
- Make sustainability commercial: Invest in validated rPCF or equivalent lifecycle assessments for premium product lines; prepare procurement RFPs to reward carbon‑verified suppliers.
- Hedge economically and operationally: Use a mix of forward contracts, inventory buffers, and formula clauses tied to mint oil indices to stabilize margins during crop stress.
- De‑risk formulations: For applications sensitive to supply disruptions (e.g., certain pharmaceutical or high‑value personal care SKUs), qualify synthetic‑equivalent or bio‑based grades in parallel to natural specifications.
- Pursue targeted consolidation: For companies seeking scale, prioritize acquisitions that add either technical (pharmacopeial accreditation, chiral synthesis) or geographical natural supply depth rather than undifferentiated volume.
- Operationalize regulatory monitoring: Establish a regulatory watch cell to assess tobacco‑flavor rulings, pharmacopeial updates, and labelling requirements that could reallocate demand or raise compliance costs.
How PW Consulting Helps
Our L‑Menthol study is structured to move clients from insight to decision. Whether you are a CPG purchaser stabilizing costs, a chemical producer sizing capacity expansion, or an investor conducting commercial due diligence, the report couples quantitative forecasting with practical templates and supplier assessments so that 2026 moves are both defensible and executable.
Note: this article highlights strategic findings and market mechanics while intentionally withholding detailed segment‑level tables and region/application splits to protect proprietary modelling and to direct stakeholders to the full report for transaction‑grade data. For full model access, supplier scorecards, and downloadable scenario workbooks, please consult the PW Consulting market portal and our L‑Menthol dossier.
For detailed analysis of this topic, please visit the official page: L-Menthol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com