

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lithium‑Metal Secondary Battery Market Poised to Expand at 18.42% CAGR Through 2032

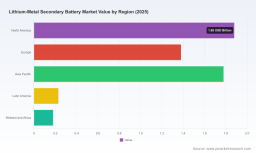
Strategic Preview: Navigating the Lithium‑Metal Secondary Battery Market in 2026 — PW Consulting Intelligence Brief
As organizations prepare capital allocation, sourcing strategies, and product roadmaps for 2026, PW Consulting’s latest market study on Lithium‑Metal Secondary Batteries delivers an actionable strategic compass. Anchored on a rigorous historical baseline (2020–2025) and forward-looking forecasts through 2032, the report quantifies a high‑growth trajectory—an 18.42% CAGR across the forecast window—while translating that growth into decision-ready insight for manufacturing, procurement, and technology investments.
Lithium-Metal Secondary Battery Market
Why 2026 Is a Strategic Inflection Point
The industry transitions out of a technology validation phase and into early commercial scale-up. From 2020 to 2025 the market expanded from a modest base to multi‑billion‑dollar commercial activity, and our 2026 starting point captures the moment when several pilot lines, patent milestones, and initial domestic production efforts converge. By 2032 the market is modeled to exceed multiple times the 2025 base, reflecting rapid adoption curves across mobility, defense, consumer, and stationary storage use cases.
Lithium-Metal Secondary Battery Market
For executives, 2026 matters because the decisions made this year—siting of production, capacity commitments, licensing and IP strategy, and raw‑material contracting—determine which players will capture scale economies and which will be forced into costly retrenchment. Our modeling shows the market maturity trend and the implied investment windows; however, the playbooks required to capitalize on that window are not one‑size‑fits‑all. That is the practical value PW Consulting delivers.
Lithium-Metal Secondary Battery Market
Report Scope and Practical Deliverables
The study is designed to be immediately operational for corporate strategy, venture investing, and procurement teams. It combines robust top‑down modeling with bottom‑up validation and includes the following practitioner tools:
- Market sizing and scenario models (base case, downside, upside) covering 2026–2032, built on granular build‑out assumptions and validated against recent commercial milestones.
- Supply‑chain maps and cost‑to‑serve indices delineating upstream feedstock risk, cell manufacturing bottlenecks, and logistics constraints.
- Technology readiness and cost‑curve analysis for lithium‑metal anodes, lithium‑sulfur chemistries, and emerging solid‑state architectures.
- Regulatory and standards tracker, highlighting near‑term certification timelines and planned regulatory shifts that materially affect OEM qualification schedules.
- IP landscape and patent cluster mapping with infringement risk scoring and targeted freedom‑to‑operate assessments.
- Go‑to‑market playbooks for OEMs and suppliers, with partnership archetypes, contracting templates, and a supplier short‑list framework for rapid deployment.
- M&A and capital‑allocation screening tools, including sensitivity analyses driven by raw‑material scenarios and production ramp curves.
To preserve competitive value for subscribing clients, the report intentionally refrains from publishing certain detailed regional and application breakdowns in public summaries. Those granular splits, supplier‑level economics, and detailed model exports are available through the full report access channel.
Competitive Landscape: Who’s Shaping the Near‑Term Frontier
Market concentration has already begun to show signs of clustering around first‑mover manufacturers and vertically integrated players. Our concentration analysis indicates that the top three companies account for a majority share of the early commercial value pool, with the top five capturing well over two‑thirds—an indicator that strategic partnerships and early capital commitments yield outsized advantage.
Key companies to watch—representative of distinct technology and go‑to‑market approaches—include:
- Lyten (San Jose, CA): Achieved U.S. production of battery‑grade lithium‑metal foils and alloys in April 2025, a strategic move to localize anode supply for lithium‑sulfur systems. Their focus on domestically produced anode materials reduces geopolitical supply risk and positions them as a potential anchor supplier for North American cell manufacturers.
- Sion Power (Tucson, AZ): Concentrating on high‑energy applications for defense and aerospace, Sion Power has expanded programs with initial cell shipments anticipated in late 2026. Their roadmap emphasizes high‑specific‑energy cells where safety and reliability are premium procurement criteria.
- Pure Lithium Corporation (Chicago, IL): Advancing a vertically integrated “Brine to Battery™” pathway, Pure Lithium’s patent wins across jurisdictions in late 2025 and early 2026 indicate an aggressive strategy to control upstream lithium conversion and downstream cell manufacture—an integration thesis that can materially shorten supply chains and reduce feedstock margin exposure.
- SES AI (Woburn, MA): Focusing on polymer electrolyte lithium‑metal systems and large‑format cells (50Ah–100Ah) for EVs, drones, and urban air mobility. Their emphasis on scalable large‑format manufacturing and energy‑dense architectures positions them for OEM partnerships where volume and formulation control matter.
In Europe and elsewhere, established suppliers such as Avesta have also announced series production of lithium‑metal anodes, evidencing regional capability build‑out and providing alternatives to sourcing concentrated in Asia or the U.S.
Dynamics That Will Shape Procurement and CapEx Decisions
Two categories of dynamics are especially material for 2026 planning: raw‑material volatility and the interplay of IP/regulatory timelines with manufacturing ramps.
- Raw‑material volatility: Lithium feedstock pricing showed pronounced swings in 2025–early‑2026. Spot lithium carbonate experienced a trough in mid‑2025 followed by a marked recovery into early 2026, while lithium hydroxide benchmarks also exhibited significant month‑to‑month divergence depending on data source. This price volatility translates directly into margin risk for cell makers and into working‑capital pressure for OEMs that delay long‑term offtake agreements.
- IP and regulatory timing: The patent grants and notices of allowance observed across key vertically integrated players create both defensive and offensive considerations. Firms should align product qualification timelines with patent landscapes and anticipate licensing or joint‑development needs well ahead of production ramps to avoid costly redesigns or injunction risk.
Our sensitivity matrices show that a one‑year shift in large‑format cell qualification can change breakeven capacity thresholds materially — supporting the case for earlier contract commitments or staged capacity investments backed by performance milestones.
What Leaders Must Decide in 2026
Executives and investors must answer a concise set of questions to secure optionality and avoid lost‑opportunity costs:
- Do we pursue vertical integration to control feedstock and IP, or partner with specialized material suppliers to preserve capital flexibility?
- Where should early production capacity be located to balance logistics, incentives, and talent availability—recognizing that early site decisions often lock in 7–10 year cost trajectories?
- Which technology pathway aligns with our core value proposition—ultra‑energy density for aerospace/defense, cost‑effective large‑format cells for EVs, or polymer/solid‑state for safety‑critical applications?
- How will we structure procurement to mitigate raw‑material price swings—long‑term indexed contracts, buy‑backs, or hedged inventory strategies?
PW Consulting’s report converts these strategic questions into executable options, prioritizing near‑term action items that meaningfully alter a firm’s position at the 2030+ inflection point.
How PW Consulting Supports Execution
Beyond the report’s analytical core, our advisory offering includes implementation sprints designed to translate insights into tangible milestones. Examples include supplier due‑diligence workshops, anode and cell pilot co‑design programs, IP clearance and licensing negotiation support, and capital‑planning models aligned to grant and incentive programs across target jurisdictions.
We work with clients to size investments against realistic ramp profiles and to structure commercial contracts that balance volume commitment with technology evolution clauses. For private investors and corporate development teams, we provide M&A target lists with fit‑for‑purpose scoring on technology, capacity, and geopolitical exposure.
Next Steps and Access to Full Intelligence
The public brief above outlines the strategic contours of the lithium‑metal secondary battery opportunity without exposing the granular regional, type, and application-level splits that drive competitive positioning. For companies preparing to commit capital or to negotiate supply and technology partnerships in 2026, the full PW Consulting report is a tactical resource: it contains the detailed model outputs, supplier economics, risk matrices, and go‑to‑market templates necessary to move from strategy to execution.
Contact our Industrial Batteries practice for a tailored briefing. PW Consulting’s multi‑disciplinary teams are positioned to help translate the 2026 inflection into measurable competitive advantage.
For detailed analysis of this topic, please visit the official page: Lithium-Metal Secondary Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com