

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Water Pumps Market to Reach USD 82.16 Billion by 2032 at a 5.1% CAGR — Asia Pacific Leads with USD 24.88B (Base Year 2025)

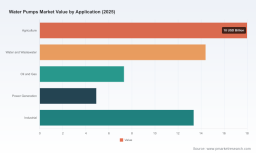
PW Consulting Strategic Brief — Water Pumps Market: Positioning for 2026
PW Consulting’s Water Pumps Market report (base year 2025) synthesizes five years of historical performance and an actionable seven-year outlook (2026–2032). The global market has expanded steadily from approximately USD 45.2 Billion in 2020 to USD 58.0 Billion in 2025 and is projected to continue growing at a compound annual growth rate of 5.1% through 2032, reaching roughly USD 82.2 Billion under the central scenario. For executive teams and investors planning 2026 initiatives, this study translates macro momentum into pragmatic decisions—without burying you in raw segment tables. The granular regional and application breakdowns, proprietary supplier scoring and downloadable forecasting models are reserved for the full report.
Water Pumps Market
Why this report matters for 2026 decisions
2026 will be a turning point for pump manufacturers, system integrators and major end-users. Three structural forces are converging: regulatory escalation (notably evolving pump-efficiency mandates and water-quality standards), acceleration of digital and energy-efficiency technologies, and strategic reshoring/localization pressures in critical infrastructure programs. Collectively, these dynamics are reshaping product roadmaps, capital allocation and go-to-market priorities. With a moderate but persistent market CAGR and a mid-market competitive concentration, 2026 decisions should prioritize agility: targeted R&D investment, selective footprint expansion, and aftermarket monetization.
Water Pumps Market
Five strategic implications for 2026 planning
-
Recalibrate R&D toward efficiency plus intelligence. Efficiency standards and energy-conservation programs are no longer optional. Firms that accelerate hydraulic optimization, advanced materials and embedded controls will extend product lifecycles and reduce total cost of ownership—critical selling points for municipal and industrial buyers under new compliance regimes. Prioritize modular platforms that allow retrofit of smart controls to legacy product lines.
Water Pumps Market -
Localize selectively to de-risk project access. Procurement rules and infrastructure incentives in several markets are raising the value of local manufacturing and verified domestic supply chains. A targeted approach—combining local assembly, partner-managed manufacturing and selective greenfield facilities—delivers compliance and cost control without broad duplicative investments.
-
Monetize aftermarket and services. As core hardware margins compress under commoditization and competitive bids, aftermarket services (predictive maintenance, spare parts subscriptions, lifecycle management) are high-margin growth levers. Companies should build bundled service propositions with clear SLA-based pricing tied to measured efficiency gains.
-
Make M&A and partnerships highly surgical. Given a moderately concentrated market structure, acquisitions should focus on plugging capability gaps—digital platforms, materials science, regional dealer networks—rather than broad-scale horizontal consolidation. Partnerships with systems integrators and utilities accelerate deployment of digital-enabled solutions where regulatory compliance is the primary procurement driver.
-
Institutionalize scenario-driven risk management. The interplay of commodity cycles, supply-chain friction and regulatory pivot points (e.g., water-quality thresholds or national content rules) calls for playbooks that model multiple futures. The report contains stress-tested scenario outputs to inform capital buffers, supplier diversification and pricing strategies.
What the report delivers — operational intelligence for 2026
This is a practitioner’s dossier for decision-makers who need executable answers, not just charts. Highlights include:
-
An executive dashboard tracking the market’s historical trajectory (2020–2025) and three forecast scenarios (base, upside, downside) for 2026–2032 that can be dropped into board materials.
-
Methodology notes and data lineage so procurement, finance and strategy teams can reconcile internal models with our outputs.
-
Decision frameworks: capex prioritization matrices, ROI templates for efficiency upgrades, and go-to-market playbooks for commercial, municipal and industrial channels.
-
Technology adoption maps that link product attributes (efficiency, materials, digital control) to buyer pain points and procurement cycles.
-
Supplier assessment toolkits and a regulatory compliance checklist tailored to the major jurisdictional shifts affecting 2026 projects.
-
A prioritized list of strategic initiatives—ranging from quick-win aftermarket pilots to multi-year platform investments—each with estimated time-to-impact and implementation risks.
Competitive landscape: positioning the leaders
The competitive profile in our study highlights the strategic postures of established pump manufacturers and identifies where advantage will be created in 2026–2032. Market concentration metrics indicate meaningful room for differentiation: the top three players collectively account for a material share of the market, with the top five occupying a broader leadership band—creating a landscape where scale, technology and distribution are each decisive.
-
Grundfos Holding A/S (Denmark) — Market leader credentials built on energy-efficient platforms and integrated control ecosystems. Their strength is in product innovation and aftermarket services; the strategic question for 2026 is how to accelerate digital monetization across legacy installed bases.
-
Xylem Inc. (United States) — Strong in water infrastructure and systems-level solutions. Xylem’s advantage is systems integration and data-driven water management; expect continued emphasis on municipal contracts and utility-grade digital offerings.
-
KSB SE & Co. KGaA (Germany) — Reinforcing its industrial engineering position with next‑generation designs. Recent model launches focused on hydraulic efficiency underline a play for industrial and municipal specification wins.
-
Sulzer Ltd. (Switzerland) — Engineered solutions and aftermarket services anchor Sulzer’s value proposition. Their installed-base service model is a template for players seeking sustainable margin uplift.
-
Pentair plc (United States) — Broad channel reach in residential and light commercial segments; distribution strength positions Pentair to capitalize on decentralized water solutions and retail-driven demand.
-
ITT Inc. (United States) — Diversified fluid-handling business with emphasis on specialized materials and OEM partnerships. ITT’s modular approach supports high-reliability applications.
-
Flowserve Corporation (United States) — Complementary portfolio across valves and pumps, emphasizing lifecycle services for heavy industries. Flowserve is well-positioned for large-scale energy and petrochemical projects.
-
WILO SE (Germany) — Known for compact, smart urban water solutions. Their European footprint, combined with smart-pump offerings, targets municipal modernization projects.
-
Ebara Corporation (Japan) — Manufacturing precision and a strong industrial base; Ebara’s engineering focus supports demand in sectors requiring high reliability and materials expertise.
-
Kirloskar Brothers Limited (India) — Deep regional presence with recent capacity expansion and product introductions. Local manufacturing and product adaptation make Kirloskar an influential player in emerging markets.
-
SPX FLOW, Inc. (United States) — Process-oriented pump technologies that serve specialty industrial segments; SPX FLOW’s channel and OEM relationships are assets for niche growth.
-
Gorman-Rupp Company (United States) — Focus on municipal and rental markets, with resilient service revenues and aftermarket opportunities.
Recent industry developments underscore the themes above: capacity investments and plant inaugurations, product launches for higher efficiency and lower solids handling, and innovations in control and automation. These moves confirm an industry pivot toward energy performance, local production capability and smart controls—each of which is extensively analyzed in the full report.
Regulation, raw materials and program-level risks
Regulatory action is a primary near-term driver. Evolving Department of Energy pump efficiency standards, national content requirements on infrastructure programs, and tightening drinking-water rules are reshaping specification requirements and procurement filters. Countries with energy-efficiency programs and industrial incentives are already seeing accelerated adoption of higher-performance pumps. Simultaneously, raw material sourcing policies and supply-chain constraints require procurement strategies that combine alternate sourcing, hedging and vertical partnerships.
How senior teams should use this study in 2026
-
Board and strategy offsites: Use our scenario outputs to stress-test capital plans and set three-year product and channel priorities.
-
M&A diligence: Apply the report’s target-screening matrix to shortlist bolt-ons that deliver capability or regional access, not just revenue.
-
Product portfolio refresh: Prioritize platform investments that can be manufactured locally and upgraded with digital modules.
-
Service transformation: Launch pilot aftermarket bundles that tie predictive maintenance to documented energy savings—then scale by channel.
Next step: what’s behind the curtain
This strategic brief surfaces the structural takeaways and practical implications senior teams must act on in 2026. The full PW Consulting report contains the detailed regional and application-level splits, supplier scorecards, downloadable forecast tables, and implementation-ready templates that operational teams can use to execute the strategies outlined here. Those granular datasets and proprietary models are intentionally withheld from this brief to preserve analytical value for report subscribers.
For leadership teams preparing board presentations, investment committees or a 2026 budget cycle, the full report provides the actionable figures and playbooks you need to convert market insight into concrete outcomes.
For detailed analysis of this topic, please visit the official page: Water Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com