

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Roofing Underlying Materials Market Set to Expand at a 4.2% CAGR Through 2032

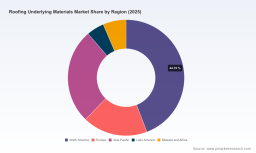
Roofing Underlying Materials Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
PW Consulting’s latest Roofing Underlying Materials Market report (base year 2025) equips executives with the forward-looking intelligence needed to set pricing, procurement, and product strategies in 2026. The global market, valued at approximately USD 146.59 Million in 2025, is projected to expand at a compound annual growth rate (CAGR) of 4.2% through the 2026–2032 forecast window, reaching roughly USD 196.6 Million by 2032. This growth will be uneven across product families and geographies, and will be shaped by raw-material volatility, regulatory headwinds, and a persistently fragmented supplier landscape.
Roofing Underlying Materials Market
Why this matters for 2026 planning
-
Budgeting and pricing: Margin compression risk will be concentrated in asphalt-based lines sensitive to crude/resin moves. Companies that bake more realistic input-cost escalation into 2026 price decks will protect operating margins without sacrificing volume.
Roofing Underlying Materials Market -
Procurement and supplier strategy: Near-term supply-chain disruptions and feedstock price swings require dynamic hedging and alternative-sourcing playbooks.
Roofing Underlying Materials Market -
Portfolio and R&D prioritization: Demand for high-performance synthetic underlayments and low-carbon alternatives will influence capex and product-development trade-offs.
Market trajectory — what the headline numbers hide
The market recovered from pandemic-era volatility to register meaningful expansion into 2025, and our baseline forecast indicates steady, mid-single-digit growth through 2032 (4.2% CAGR). That trajectory reflects a mix of steady replacement demand in residential roofing, steadying commercial construction pipelines, and selective innovation-driven uptake of non-bitumen synthetics. However, growth is materially exposed to two variables: (1) crude oil and resin price cycles that feed asphalt and polymer costs; and (2) construction input inflation and regulatory developments that can accelerate renovation cycles or delay new-builds.
What the full report delivers (practical, executable content)
-
Comprehensive market model — multi-scenario top-down and bottom-up forecasts from 2026–2032, with sensitivity levers for feedstock price, installation rates, and policy shifts.
-
Competitive benchmarking — capability maps, plant footprints, and go-to-market vectors for the leading suppliers, accompanied by a quantified margin and cost-to-serve framework (note: detailed subsegment shares are reserved for report subscribers).
-
Procurement playbook — hedging strategies, alternative-sourcing routes, and vendor scorecards to defend gross margins when crude-based inputs spike.
-
Commercial and pricing templates — tiered price-response strategies validated against real-world supplier moves and channel elasticity studies.
-
Capex and network optimization toolkit — plant-level utilization scenarios, make-or-buy thresholds, and logistics trade-offs to optimize working capital and lead times.
-
M&A and partnership blueprint — target criteria, valuation multiples observed in adjacent polymer and membrane deals, and integration checklists for buyer diligence.
-
Regulatory and sustainability roadmap — compliance timing, green-product commercialization pathways, and carbon-intensity reduction levers for underwriting long-term product premiums.
Competitive landscape — who moves markets
The roofing underlayments and base-materials market remains fragmented, with many specialized players operating regionally and a handful of large incumbents influencing price and innovation cycles. PW Consulting’s qualitative and quantitative review highlights a spectrum of strategic postures among the name-players below — from vertical integrators to membrane specialists — each with different implications for partners and rivals.
-
GAF Materials Corporation (Parsippany, NJ) — North America’s leading residential/commercial roofing systems provider. GAF’s scale and channel coverage give it a premium position to pass through cyclical cost increases, but its pricing actions are a bellwether for the broader market, as seen in the company’s April 2026 price increase.
-
Owens Corning (Toledo, OH) — A major player in synthetic and self-adhered underlayments, Owens Corning combines material science R&D with broad channel access. Its product mix positions it to capitalize if adoption of synthetic alternatives accelerates.
-
CertainTeed Corporation (Malvern, PA) — Focused on premium residential products and sustainability-driven differentiation. CertainTeed’s April 2026 pricing action demonstrates how sustainability messaging and premium positioning co-exist with the need to protect margins.
-
Carlisle Companies Incorporated (Scottsdale, AZ) — A leader in commercial single-ply membranes and technical underlayments via Carlisle SynTec. Carlisle’s exposure to commercial roofing dynamics makes it especially sensitive to nonresidential construction cycles and public-sector procurement.
-
IKO Industries (Mississauga, ON) — A vertically integrated manufacturer with broad North American and European manufacturing footprint; vertical integration provides a degree of raw-material and margin insulation but requires active optimization in volatile feedstock environments.
-
Johns Manville (Denver, CO) — Supplies a wide array of commercial membranes and underlayments; technical and industrial focus drives different channel economics compared with residential shingle suppliers.
-
TAMKO Building Products (Galena, KS) — Regional stronghold with a focused residential product mix; TAMKO’s March 2026 price increase exemplifies near-term elasticity testing among regional customers.
-
Atlas Roofing Corporation (Atlanta, GA) — Syncretic positioning across shingles and synthetic underlayments with emphasis on performance attributes (wind/impact). Atlas’s April 2026 price action is indicative of manufacturers’ attempts to realign prices with elevated input costs.
-
Duro-Last, Inc. (Saginaw, MI) — Niche specialist in custom-fabricated PVC systems for commercial roofs; its value proposition centers on long-life membranes and reduced life-cycle costs.
-
Soprema (Wadsworth, OH) — Strong presence in membrane and waterproofing systems for both commercial and residential markets; product breadth supports integrated systems sales to contractors and specifiers.
Pricing and raw-material dynamics — the immediate 2026 pressure points
Crude oil and resin price movements remain the dominant input variable. Brent crude was trading around USD 92.87 per barrel (early June 2026 reference) and WTI averaged in the low-to-mid USD 90s per barrel, directly pressuring asphalt feedstocks and polymer resins. Concurrently, government data show construction input prices rising sharply into Q1 2026, with the largest year-over-year gain since early 2023. These forces together prompted a wave of manufacturer price increases in March–April 2026, with multiple large suppliers implementing mid-single-digit to high-single-digit adjustments across shingles, underlayments, and membranes.
For 2026 planning, two practical consequences follow:
-
Price pass-through windows will be short and contested; companies that can demonstrate transparent input-linked price mechanics in channel agreements will be better positioned to preserve margin while retaining share.
-
Procurement diversification (feedstock swaps, regional buys, long-term resin contracts) and operational levers (formulation changes, yield improvements) will be high-impact, near-term value drivers.
Strategic playbook for 2026 — prioritized actions for executives
-
Embed scenario-based costing into 2026 budgets. Incorporate at least two downside scenarios tied to +/- 20–30% swings in crude and resin baskets to stress test margins and covenants.
-
Reassess channel contracts to include indexed pricing triggers or shared-savings clauses that preserve competitiveness during volatile input cycles.
-
Accelerate higher-margin synthetic and polymer-based product commercialization where lifecycle premiums are defensible, and protect IP through tactical partnerships with compounders and membrane formulators.
-
Prioritize plant-level resiliency investments (modular instrumentation for quick formula changeovers, dual-feed capability) to reduce changeover costs and capture opportunistic arbitrage.
-
Use targeted M&A to acquire incremental manufacturing scale or specialty formulation talent rather than broad regional roll-ups — the market remains sufficiently fragmented to reward bolt-on scope acquisitions.
-
Operationalize ESG-linked revenue opportunities: low-carbon asphalt alternatives and recycled-content synthetics can command price premiums for publicly funded or high-spec projects.
Risk scenarios and monitoring dashboard
PW Consulting’s dashboard for 2026 monitoring emphasizes five leading indicators: crude/resin basket, regional construction starts, distributor inventory levels, lead times at major compounders, and announced manufacturer price actions. In our scenario framework, a persistent elevation in crude/remnant resin prices combined with slowing commercial starts produces the downside case; conversely, a rapid adoption of synthetic underlays and stable oil prices support upside adoption and margin expansion.
How to use this report in your 2026 decision cycle
-
Board and investor briefings: use the scenario outputs and consensus case to update EBITDA guidance and working-capital sensitivities.
-
M&A diligence: apply the valuation templates and synergy calculators to screen targets where cost-to-serve and formulation IP create defensible arbitrage.
-
Commercial strategy sessions: deploy the price-response playbook in quarterly channel reviews to align distributor incentives and protect shelf placement.
-
Procurement renegotiations: use the supplier scorecards and hedging approaches as the basis for RFPs and long-term resin contracts.
Closing — what you gain by reading the full analysis
This release provides the strategic contours and immediate implications for 2026 decision-making. The full PW Consulting Roofing Underlying Materials Market report contains the granular, transaction-grade intelligence (detailed subsegment shares, regional and application splits, plant-level economics, and vendor-level margin models) that commercial and corporate development teams require to execute. If your 2026 plans hinge on pricing, procurement, or product roadmap choices in roofing underlayments and base materials, the full dataset and playbooks will materially shorten your path from insight to action.
Methodology note
Base year: 2025. Historical period: 2020–2025. Forecast horizon: 2026–2032. Our model synthesizes primary interviews with manufacturers and distributors, contract-level pricing data, macro commodity inputs, and construction starts datasets. Select public actions from industry participants in March–April 2026 corroborate the near-term pricing pressures outlined above.
For access to the complete report, the downloadable data tables, and client workshops that translate the findings into bespoke 2026 playbooks, visit PW Consulting’s market report page (full link available in the press release distribution).
For detailed analysis of this topic, please visit the official page: Roofing Underlying Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com