

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Optical Disc Drive Market Poised for a Steady 2.38% CAGR Through 2032, New Insight Shows

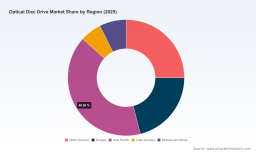
Optical Disc Drive Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest Optical Disc Drive (ODD) Market report — base year 2025 with a forecast horizon to 2032 — delivers a pragmatic roadmap for executives, product leaders, investors, and supply-chain strategists preparing decisions in 2026. Grounded in a rigorous historical series (2020–2025) and forward-looking scenario analysis, the market is modeled in USD Million and shows a measured recovery and renewal pattern: the global market expanded from approximately USD 2,053.2 Million in 2020 to USD 2,455.6 Million in 2025, and under the base forecast grows at a compound annual growth rate (CAGR) of 2.38% through the 2026–2032 period, reaching roughly USD 2,914.8 Million by 2032. These headline dynamics mask important inflection points — product lifecycle transitions, aftermarket opportunities, and concentration-driven competitive levers — that will materially shape strategic choices in 2026.
Optical Disc Drive Market
Why this report matters for 2026
-
Decision timing: 2026 is the first full planning year after our base year. The trajectory established to 2025 and the early uptick projected for 2026 create windows for reallocating R&D, refreshing product portfolios, and recalibrating go-to-market investments.
Optical Disc Drive Market -
Low-to-moderate market growth: A 2.38% CAGR signals a stable but mature market; winners will capture share through differentiation (form factor, reliability, integration with PC/OEM ecosystems) and expanded aftermarket services rather than through volume-driven expansion alone.
Optical Disc Drive Market -
Concentration matters: Market concentration metrics indicate that leading manufacturers continue to command a majority of supply and OEM relationships. That structural reality raises the value of partnerships, licensing, and selective acquisitions to accelerate access to channels or technology.
Market trajectory and near-term inflection points
Our model synthesizes shipment-level inputs, OEM sourcing patterns, and pricing dynamics to map a multi-year curve that reflects both demand-side stabilization and episodic upticks tied to product refresh cycles. After steady recovery through 2024–2025, the model projects a modest acceleration in 2026, driven by replacement cycles in commercial and consumer equipment and continued demand for high-capacity optical media compatible with specialized workflows.
Key structural observations:
-
Replacement and aftermarket economics: As installed bases age, aftermarket service, spare parts, and upgrade programs become higher-margin opportunities than new unit sales.
-
Product lifecycle heterogeneity: The portfolio spans legacy CD-ROM and DVD form factors to high-capacity Blu-ray variants — each with differing margin profiles and adoption dynamics; strategic winners will manage a balanced roadmap across legacy support and selective high-density innovation.
-
OEM channel stickiness: Original equipment manufacturer relationships remain the dominant route to scale; negotiating favorable long-term supply terms or co-development agreements remains a key 2026 priority.
Actionable strategic playbook for 2026
For executive teams entering 2026 planning cycles, the report translates market intelligence into a pragmatic set of initiatives:
-
Portfolio prioritization: Segment products into “Core Support,” “Profit Accretors,” and “Strategic Investments.” Allocate R&D and manufacturing capacity commensurate with each bucket to maintain service margins while investing selectively in high-value format enhancements.
-
Aftermarket monetization: Launch targeted service contracts, lifetime warranties, and upgrade kits for enterprise clients. Our elasticity analysis indicates that modest investments in field service infrastructure can disproportionately increase lifetime value.
-
Supply-chain resilience: Adopt dual-sourcing for critical components, implement strategic buffer inventories for long-lead items, and pursue co-development agreements to lock in technological roadmaps with key suppliers.
-
Channel engineering: Deepen OEM integration through certified modules and reference designs; explore bundling optical drives with software or content partnerships that expand stickiness and create new revenue share models.
-
Cost-to-serve optimization: Reexamine logistics and fulfillment footprints to reduce end-to-end cost without increasing lead times — including selective nearshoring for time-sensitive SKUs.
-
M&A and alliances: Prioritize small-to-midscale acquisitions that provide complementary IP, aftermarket service networks, or channel access over large transformational deals, given the market’s measured growth profile.
Report deliverables — what executives will find inside
This publication is designed as a decision-support toolkit rather than a static market summary. Highlights of deliverables include:
-
Granular market model and scenario engine (2020–2032) with base and alternate cases so planners can stress-test assumptions across demand shocks, price erosion, and technology shifts.
-
Product-by-product margin and total-cost-of-ownership (TCO) analyses that identify where incremental engineering investment yields the largest margin expansion.
-
Commercial playbooks: GTM templates for OEM, channel, and direct enterprise sales; negotiation frameworks for long-term supply agreements; and pricing sensitivity maps to optimize list vs. negotiated pricing.
-
Supply-chain risk heat map: Tiered supplier exposure, lead-time distribution modeling, and contingency plans prioritized by risk impact.
-
Investment decision frameworks: Scorecards and valuation guidance for M&A targets, licensing deals, and greenfield manufacturing investments tailored to the ODD lifecycle.
-
Appendices with methodology, key data sources, and model transparency to support internal audit and board-level review.
Competitive landscape: positioning and implications
The market remains concentrated among a handful of incumbents that maintain deep OEM relationships and manufacturing scale. Our competitive concentration analysis shows a pronounced leader-centric structure, reinforcing the strategic premium of scale and sustained OEM certification programs.
Case in point: Hitachi-LG Data Storage is profiled as a longstanding global leader with extensive installed scale and a history of supplying manufacturers at volume. Its product portfolio spans internal and external optical drives, including slimline and high-capacity variants, and it has established a durable position in OEM channels. For challengers and partners alike, this type of incumbent profile carries both barriers and opportunities:
-
Barrier: Deep, long-term OEM relationships and scale production create entry friction for challengers seeking volume contracts.
-
Opportunity: Strategic collaboration (component supply, co-engineering, or licensed manufacturing) can accelerate market entry without the full burden of scale economics.
-
Partnering rationale: For firms with differentiated IP or niche applications, partnering with an incumbent can offer a faster route to channel access and certification.
Investment signals and risk calibration
Given the measured CAGR and concentration dynamics, the optimal investment posture in 2026 is selective and disciplined. Recommended investment priorities are:
-
Capex for precision manufacturing or retrofit of lines that support higher-margin SKUs, justified by detailed ROI modeling in the report.
-
Targeted acquisitions for aftermarket service providers, software-enabled content partners, or suppliers with unique components that shorten time-to-market for premium offerings.
-
Defensive investments in IP and certification compliance, as regulatory and content-protection requirements can materially affect OEM qualification and pricing power.
Risk factors to monitor closely in 2026 include raw-material price volatility, sudden shifts in OEM bundling strategies, and potential obsolescence in specific low-density formats. The report’s scenario module quantifies these risks and provides contingency pathways.
How to use this report in your 2026 planning
-
Executive planning: Use the report’s scenario outputs to stress-test top-line and margin forecasts during budget cycles and to align board-level capital allocation with realistic upside scenarios.
-
Product strategy: Adopt the report’s portfolio triage methodology to prioritize roadmaps and stop-loss rationales for underperforming SKUs.
-
M&A diligence: Leverage our target-screening frameworks and valuation templates to move quickly on bolt-on acquisitions that enhance aftermarket or channel capability.
-
Procurement: Implement the supplier heat-map and dual-sourcing playbook to reduce single-vendor dependency ahead of contract renewal windows.
What we intentionally withhold (and why)
Consistent with the “trailer” approach of this briefing, we are presenting the high-level market trajectory, structural implications, and the strategic playbook that will be relevant to 2026 decisions. Detailed tables with regional and application-level breakdowns, line-item revenue schedules, and the full set of segment-specific forecasts are reserved for the full report and its accompanying Excel model. This preserves the actionable intelligence and encourages direct engagement with our advisory team for executional support.
Next steps
Leaders preparing 2026 strategy cycles should: (1) review the scenario outputs in the full report to align planning assumptions; (2) initiate horizon-one moves for aftermarket monetization and OEM negotiations; and (3) schedule a tailored strategy workshop with PW Consulting to translate the model into an executable 18-month roadmap. Our team can also provide bespoke sensitivity analyses and M&A target screens keyed to your corporate objectives.
For access to the full dataset, segmented forecasts, company profiles, and the scenario modeling toolbox, please request the PW Consulting Optical Disc Drive Market full report and model. The intelligence contained therein is calibrated for swift executive use in the 2026 planning and investment cycle.
For detailed analysis of this topic, please visit the official page: Optical Disc Drive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com