

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts IoT Fleet Management Market to Reach USD 39.5 Billion by 2032

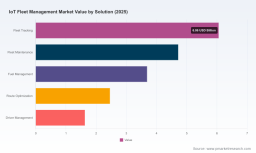
PW Consulting Releases Strategic Brief: IoT Fleet Management Market Outlook — Essential Intelligence for 2026 Decision-Makers
PW Consulting today publishes an executive briefing from our new IoT Fleet Management Market research report (base year 2025, forecast 2026–2032). The analysis synthesizes five years of historical performance (2020–2025) and delivers scenario-driven guidance for procurement, operations, and M&A choices that will shape fleet programs in 2026. At a macro level, the market has demonstrated robust expansion—from approximately USD 10.9 Billion in 2020 to USD 18.56 Billion in 2025—and our modeled trajectory, underpinned by an 11.42% compound annual growth rate, points to a continued climb toward roughly USD 39.5 Billion by 2032. This growth amplifies both opportunity and complexity for enterprises planning near-term investments.
IoT Fleet Management Market
Why this report matters for decisions in 2026
-
Timing: 2026 is a pivot year—cloud-native platforms, edge-capable telematics devices and regulatory moves are simultaneously accelerating deployment pressure. Executive sponsors need a concise playbook to sequence investments without overcommitting capital.
IoT Fleet Management Market -
Trade-offs: Buyers must balance hardware and connectivity costs against software-led operational gains. Our research quantifies typical cost buckets, models TCO scenarios, and translates them into procurement triggers for small, mid-size, and enterprise fleets.
IoT Fleet Management Market -
Risk management: Increasing regulatory fragmentation (spectrum allocation, data sovereignty and evolving net neutrality regimes) elevates compliance risk. This report maps practical mitigations for cross-border operations and multi-jurisdiction rollouts.
Key market dynamics shaping 2026 strategies
-
Technology convergence—edge + AI: The next wave of value is migrating to the device layer. Our field interviews and device telemetry analysis reveal suppliers are embedding more processing capability into telematics and camera devices to reduce latency, preserve bandwidth, and enable local compliance controls. This trend changes procurement priorities: compute-per-unit now competes with connectivity spend when calculating ROI.
-
Cost composition matters: Deployment budgets are not evenly distributed. Telematics hardware, GPS modules and sensors represent a substantial share of initial outlays, while connectivity, cloud services and cybersecurity occupy a non-trivial recurring spend. Procurement teams that optimize across both CAPEX and OPEX unlock materially lower lifecycle costs.
-
Regulatory friction: Spectrum licensing, regional band differences, and data sovereignty rules force architectural decisions—centralized clouds are not always viable. Our compliance framework prescribes localization strategies and vendor contractual clauses that reduce legal exposure without sacrificing operational visibility.
-
Skills and integration: Skilled labor for installation, legacy integration and analytics remains a gating constraint. We quantify typical integration timelines and recommend modular rollout approaches that shorten time-to-value while reducing dependence on scarce specialists.
-
Commercial models diversifying: Vendors increasingly couple hardware, software and services in blended commercial models. Our commercial matrix helps buyers compare pure-SaaS, device-anchored subscriptions, and outcome-based contracts across realistic fleet scenarios.
Competitive landscape — what market leaders are doing
The market remains moderately concentrated: the top three players hold a meaningful share, and the top five consolidate further, but there is room for differentiated niche players and continued consolidation. Leaders are pursuing distinct tectonic moves that buyers and acquirers should watch closely.
-
Samsara Inc. continues to advance a platform-centric strategy focused on real-time operations, safety and compliance. Recent product activity underscores a dual push: expand regulatory services for international customers and deepen safety automation. Their introduction of dynamic compliance tooling signals an intention to make complex regulatory adherence a core value prop for fleets operating across multiple regimes.
-
Geotab Inc. is investing aggressively in mixed-fleet and edge-capable devices. New hardware launches and a unified platform for on- and off-highway operations show a play to capture construction and heavy-equipment telemetry—areas traditionally underpenetrated by pure fleet telematics vendors.
-
Verizon Connect leverages network integration to position itself as a turnkey solution for customers seeking high-availability telemetry and integrated SIM/cellular management. Their strategy reduces buyer complexity for enterprises that prefer telecom-grade SLAs and consolidated billing.
-
Trimble and Omnitracs emphasize transportation software depth and logistics optimization, appealing to fleets where route efficiency and back-office integration yield direct margin impact. Their offerings are attractive to operators looking to rationalize multiple point solutions into one platform.
-
Teletrac Navman and Powerfleet (formerly Fleet Complete) are differentiating through specialized video telematics, AI camera systems, and operational analytics that speak to compliance and risk-avoidance buyers.
-
Cisco and CalAmp occupy infrastructure roles—connectivity platforms, device lifecycle management, and telematics hardware—making them natural partners for systems integrators and enterprises focused on scalability and secure device fleets.
Recent product introductions across the vendor ecosystem—ranging from AI-powered camera systems to edge-optimized telematics devices—are shifting the locus of competition from pure tracking to platform intelligence. For 2026 purchasers, competitive differentiation will hinge on three vendor capabilities: device edge compute, regulatory compliance tooling, and the depth of analytics that turn telemetry into operational decisions.
What’s inside the PW Consulting report — practical, executable content
-
Actionable buyer playbooks: build vs. buy decision trees, procurement RFP templates and vendor scorecards tuned to fleet size and mission profile.
-
TCO and ROI models: scenario-based calculators that combine CAPEX/OPEX elements (including hardware, connectivity, cloud, and labor) to produce multi-year financials and payback horizons.
-
Implementation blueprints: phased rollout plans, integration checkpoints with common telematics platforms, and field installation labor estimates to reduce deployment surprises.
-
Compliance and localization matrices: practical steps to meet spectrum, data sovereignty and privacy obligations across operating regions—plus contract language templates to embed in supplier SLAs.
-
Vendor benchmarking and M&A scouting: profiles, capability heatmaps, and acquisition candidate screening criteria for strategics and private equity interested in consolidation plays.
-
Technology roadmaps and scenario planning: three adoption scenarios (baseline, accelerated, and disruptive) that map to budget envelopes and operational KPIs for 2026–2028 decision horizons.
How to use this intelligence in 2026
-
Prioritize pilots that test edge compute and AI camera use-cases before enterprise-wide rollouts. Pilots should be designed to validate both technical interoperability and the real-world operational uplift in safety or fuel efficiency.
-
Structure contracts to separate hardware replacement cycles from software subscriptions. This reduces vendor lock-in risk while enabling iterative upgrades to edge capabilities as they mature.
-
Build a compliance-first architecture for international fleets: adopt localized processing where required, use contractual assurances for data handling, and plan for multi-band connectivity strategies to mitigate spectrum and roaming issues.
-
Invest in workforce enablement early. Training installers, integrators and analysts reduces long-tail support costs and accelerates time-to-value; our installation staffing model provides concrete FTE estimates by fleet scale.
-
Monitor vendor roadmaps and recent product launches—particularly in edge devices and compliance tooling—to align procurement windows with feature availability and to capture competitive pricing benefits from product cycles.
Next steps — where to get the full intelligence
The briefing above offers a distilled strategic vantage point. For CFOs, CIOs and heads of fleet operations preparing budgets and programs for 2026, the full PW Consulting IoT Fleet Management Market report supplies the granular segmentation, model inputs, and regional price sensitivity analyses necessary to finalize capital approvals and vendor RFIs. The report includes the full dataset, scenario models, and vendor profiles that were summarized here; access to the complete content will enable your team to convert strategic intent into executable plans with confidence.
To obtain the comprehensive report and supplementary tools—including editable TCO spreadsheets, RFP templates and a vendor short-list tailored to your fleet profile—contact PW Consulting via our website. Our analysts stand ready to provide a tailored briefing for your executive team and to support immediate procurement or M&A diligence for 2026 initiatives.
For detailed analysis of this topic, please visit the official page: IoT Fleet Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com