

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Rotary DIP Switches Market to Grow from USD 159.56 Million in 2025 to USD 199.66 Million by 2032 at a 3.3% CAGR — Asia‑Pacific Leads with USD 68.82 Million

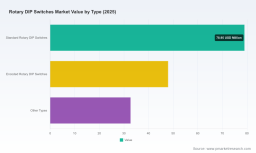
Rotary DIP Switches Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
The rotary DIP switches market is evolving from a niche components market into a strategically important segment for OEMs managing configuration, channel-setting, and ruggedized human-machine interfaces. PW Consulting’s latest study — built on a 2020–2025 historical base and projecting through 2032 — shows steady, predictable growth driven by industrial automation upgrades, continued demand in communications and instrumentation, and selective product premiumization. The market expanded from roughly USD 132 million in 2020 to about USD 160 million in 2025 and is forecast to approach USD 200 million by 2032. Our forecast period (2026–2032) carries a compound annual growth rate of approximately 3.3%.
Rotary DIP Switches Market
This trajectory reflects maturity: growth is slower than high‑velocity semiconductor segments, but attractive because of high replacement value, long product life cycles, and technical barriers to entry (precision manufacturing, environmental qualification, and certification). For 2026 planning cycles, this report is designed to translate that stability into concrete strategic choices — selecting suppliers, defining product roadmaps, and calibrating inventory and sourcing strategies under material-cost and regulatory pressures.
Rotary DIP Switches Market
What the full report delivers (practical, operations-ready content)
- Robust market sizing and forward-looking scenarios — base, upside, and downside — to stress-test revenue plans and model SKU-level impacts under different adoption speeds.
- Proven forecasting methodology and an editable financial model (Excel) so procurement, product, and strategy teams can run custom scenarios tied to their BOMs and unit forecasts.
- Competitive benchmarking of leading suppliers, including capability maps, certification profiles, time-to-market estimates, and supplier risk scores.
- Supply chain and cost‑curve analysis highlighting where material volatility (notably plastics and aluminium components) compresses margins or triggers alternative sourcing.
- Regulatory and qualification playbook — required test suites and certification pathways (e.g., environmental, military, and medical pathways) that accelerate design-in cycles.
- Commercial playbooks: go-to-market and aftermarket strategies, distributor and EMS partner selection criteria, pricing tactics, and contract negotiation levers.
- M&A and partnership opportunity scans: criteria for bolt-on targets, capability gaps, and manufacturing consolidation candidates.
Why this matters for 2026 decision cycles
- From a procurement perspective: predictable mid-single-digit market growth combined with material-price volatility means teams should prioritize multi-year supply agreements with capacity guarantees, while preserving options to switch between sealed and non-sealed product families as assembly-process requirements change.
- From a product-development perspective: enterprise customers must balance the cost and complexity of environmental and immersion cleaning qualifications against differentiation opportunities in ruggedized or medical applications. Investments in AS9100D-level quality systems and IEC 60068 environmental testing pay off when pursuing defense and healthcare segments.
- From a manufacturing footprint perspective: production concentration among a limited number of global suppliers (see concentration discussion below) implies that locating final assembly or buffer inventory near key EMS partners can materially reduce lead-time risk and expedite design changes.
- From an innovation standpoint: small modular changes in knob/actuator ergonomics and sealed‑contact chemistry yield disproportionate value in premium segments. Roadmapping these features into product line roadmaps for 2026–2028 can secure design wins that sustain revenues through long product life cycles.
Competitive landscape—who matters and why
The market exhibits significant concentration at the top. The largest three vendors account for roughly seven out of ten revenue units at the leading end of the market, and the top five capture most of the remaining share. That concentration creates advantages for scale players (capacity stability, certification breadth) and niche specialists (precision, sealed technology and military/medical focus).
Rotary DIP Switches Market
- Grayhill (La Grange, Illinois) — Known for precision rotary DIP variants and a strong presence in military and healthcare controls. Their emphasis on quality-system certifications and immersion-capable sealed products positions them as a preferred partner for defense and medical OEMs that demand AS9100D-level controls and strict qualification processes.
- C&K Components (Irvine, California) — Strength lies in coded and high-density rotary solutions tailored to communications and embedded systems. Their product breadth helps OEMs seeking compact, programmable configuration controls.
- E-Switch (Cypress, Minnesota) — Recognized for sealed-series products suitable for industrial and medical equipment, offering design choices that simplify assembly-line cleaning and environmental qualification.
- CIT Relay & Switch (Auburn, New York) — Focused on sealed-coded rotary products with practical terminal options, attractive to OEMs needing higher electrical ratings in compact packages.
- Asian and European manufacturers — Companies such as Diptronics, Nidec Copal, Omron, NKK, ALPS ALPINE, Würth Elektronik and several Taiwanese firms bring scale, diversified manufacturing footprints, and regionally optimized cost bases. Dailywell stands out for manufacturing capacity scale, while Salecom and Taiway offer cost-competitive, high-volume manufacturing options.
For buyers, the competitive choice is often a trade-off between certified, premium suppliers (shorter qualification cycles for regulated sectors but higher unit cost) and lower-cost manufacturers (price pressure but longer qualification timelines and potential supply risk). Our supplier scorecards in the full report quantify these trade-offs and provide ready-to-use RFP templates and acceptance criteria.
Supply chain & regulatory dynamics to watch in 2026
- Raw material volatility: Prices and availability for plastics and aluminium components remain a near-term margin lever. Procurement teams should model material-cost pass-throughs into multi-year contracts and consider hedging or strategic inventory levels for critical subcomponents.
- Certifications and testing regimes: ISO 9001 and ISO 14001 remain table stakes; AS9100D and IEC 60068 are decisive differentiators for defense, aerospace, and industrial OEMs. Sealed rotary DIP switches that are qualified for immersion cleaning reduce downstream assembly risk and are increasingly demanded by high-throughput EMS and medical production lines.
- Concentration and resilience: The high share held by leading vendors increases the importance of supplier diversification strategies. Dual-sourcing, staggered lead-times, and geographically distributed safety stock reduce single-point-of-failure exposure.
How clients should use the report when making decisions in 2026
- Procurement teams: Use the cost curve and supplier scorecards to renegotiate supply agreements and set contract terms that reflect qualification costs and lead-time commitments.
- Product and engineering teams: Align product roadmaps with certification timelines. Prioritize product families where minor changes unlock design wins in regulated sectors with higher margins and longer lifecycles.
- M&A teams: Focus on tuck-in targets that add sealed‑switch capability, environmental testing labs, or regional manufacturing capacity to mitigate concentration risks.
- Operations and supply-chain leaders: Implement inventory and sourcing playbooks in the report to buffer against raw‑material price swings and single-supplier exposure, while preserving flexibility for design iterations.
Why PW Consulting’s approach is different
We combine component‑level engineering sensitivity analysis with a commercial lens. Rather than offering static market shares, the report provides dynamic scenario tools — including SKU-level P&L impact assessments — tailored to procurement and product teams. Our supplier scorecards map certification, testing capability, lead times, capacity, and documented quality history into a single, actionable procurement grade. The goal is to move teams from anecdotal supplier preference to defensible, repeatable supplier selection criteria that hold up under audit and during M&A diligence.
Next steps—accessing the intelligence you need
This brief highlights the strategic contours of the rotary DIP switches market for 2026 planning. For commercial teams, supply‑chain leads, and corporate strategists who are preparing annual budgets and three‑year product roadmaps, the full PW Consulting report provides the granular inputs required to translate these insights into actionable plans: detailed regional and application splits, supplier-level cost models, downloadable scenario workbooks, and validated sourcing checklists.
To request the full report, including the Excel scenario model and supplier scorecards, visit our report page or contact your PW Consulting account manager. The full dossier contains the segmented data, granular competitor matrices, and procurement templates that are intentionally excluded from this preview to protect the integrity of the primary research and to ensure direct access for subscribing clients.
Prepared by PW Consulting — Senior Strategy & Industry Analysis Team. We welcome briefing requests and custom extensions of the model to your product and supplier portfolio.
For detailed analysis of this topic, please visit the official page: Rotary DIP Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com