

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fault Indicators Market Forecast to Reach USD 248.8 Million by 2032 on a 4.85% CAGR

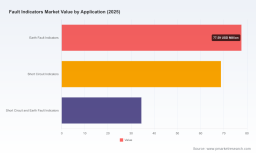
Fault Indicators Market 2026 Strategic Preview: Actionable Intelligence for Executive Decision-Making
As utilities and grid OEMs recalibrate their reliability and automation roadmaps for 2026, PW Consulting’s Fault Indicators Market report delivers an indispensable strategic lens. Anchored on a 2025 base year and built from a five-year historical series, our analysis projects a steady compound annual growth rate of 4.85% through the 2026–2032 forecast window — translating to market expansion from roughly USD 181 million in 2025 to about USD 249 million by 2032. This preview outlines the report’s operational value for decisions you will make in 2026, surfaces near-term competitive dynamics, and identifies the practical levers procurement, product and strategy leaders should prioritize.
Fault Indicators Market
Why this research matters to 2026 strategy
- Regulatory pressure is tightening. Reliability standards such as NERC’s availability and feeder-level outage expectations, and regional directives aimed at reducing customer minutes lost, are compressing acceptable fault-detection windows and forcing utilities to rethink sensing architectures.
- Distribution networks are getting more complex. Increasing distributed generation, electrification of transport, and denser underground cabling are raising the technical bar for accurate fault localization and fast restoration — shifting value toward intelligent, directional, and submersible fault sensing solutions.
- Procurement focus is moving from unit price to lifecycle value. While medium-voltage fault indicators remain low-cost hardware items on a per-unit basis, the economic case for devices that reduce transient outage duration, integrate with distribution automation (DA), and minimize truck rolls is becoming decisive.
What the report delivers — practical, deployable outputs
- Robust market sizing and forecast framework with transparent methodology and baseline series (2020–2025 historical, 2026–2032 projected).
- Vendor benchmarking matrix covering product families, deployment environments (overhead, underground, cable banks, panels), intelligence levels (passive, directional, digital), and systems-integration maturity.
- Operational playbooks for pilot selection, field testing protocols, and measurable KPIs (restore time reduction, truck-roll avoidance, false-positive rates).
- Procurement decision tools including TCO calculators, RFP templates, and risk-adjusted supplier scorecards.
- Supply-chain risk model addressing component availability, pricing sensitivity, and supplier concentration impacts.
- Regulatory compliance mapping that converts reliability standards into procurement and deployment requirements.
Taken together, these deliverables are designed to move decisions from debate to deployment: short-listing vendors, specifying pilot success criteria, and building business cases for network-wide rollouts.
Fault Indicators Market
Market trajectory — high-level, data-driven takeaways
The market’s projected 4.85% CAGR reflects steady, demand-led growth rather than a short-lived spike. Between the pandemic recovery years and today’s push for grid resilience, utilities have steadily increased investments in fault detection and sectionalizing technology. The coming five to seven years are expected to consolidate that momentum: vendors that pair robust hardware with digital integration and remote diagnostics will capture disproportionate value.
Fault Indicators Market
Market concentration remains moderate: the top three vendors do not dominate the landscape, and even the top five leave significant share to regional specialists and systems integrators. For incumbents and new entrants alike, that creates opportunity for focused differentiation — whether through ruggedized underground solutions, directional earth-fault intelligence, or seamless DA integration.
Competitive landscape — who to watch and why
The market is populated by a diverse set of companies that range from heavy electrical conglomerates to niche specialists. The companies highlighted in our analysis illustrate different strategic paths:
- Schweitzer Engineering Laboratories (SEL) — SEL’s LINAM family spans overhead to underground devices, including new ruggedized underground fault indicators introduced in early 2025. Their focus on field-hardened designs and strong protection system heritage positions them well for utilities prioritizing durability and integration with protection schemes.
- Eaton Corporation — Eaton leverages its Cooper Power series to deliver variable-trip faulted-circuit indicators aimed at medium-voltage distribution. Eaton’s pathway leverages existing utility relationships and emphasizes tried-and-tested hardware complemented by service offerings.
- Siemens AG — Siemens’ SICAM portfolio targets cable-network challenges with dedicated short-circuit and earth-fault indicators for medium-voltage networks; their strength is in system-level integration and enterprise software alignment.
- Dipl.-Ing. H. Horstmann GmbH — A specialist in underground cable indicators, Horstmann’s product series appeals to operators with extensive underground networks and bespoke technical requirements.
- Ensto Protrol — With directional earth-fault sensing in its IPC4020 line, Ensto targets secondary substation-level diagnostics and nuanced fault discrimination — a capability increasingly sought where single-phase faults and neutral shifts complicate detection.
- A. Eberle GmbH & Co. KG — A. Eberle’s combined-location indicators for digital secondary substations speak to utilities modernizing distribution substations and integrating digital protection ecosystems.
- Suparule Systems Ltd — As a niche medium-voltage cable sensor specialist, Suparule focuses on practical, cost-conscious devices tailored to underground cable fault detection.
- Sentient Energy, Inc. and Tollgrade Communications, Inc. — These companies represent the intelligent-sensing end of the market: their solutions emphasize line sensing, circuit-level analytics, and direct integration with DA and outage-management systems, offering a pathway to measurable reductions in outage duration and operational costs.
Our full vendor profiles include side-by-side technical comparisons, integration-readiness scoring, and field-performance proxies based on deployment case studies — information that is central to RFP shortlisting but intentionally withheld in this preview to preserve the report’s commercial value.
Regulatory and procurement dynamics shaping 2026 choices
- Reliability mandates are converting into procurement specifications. NERC’s availability expectations and similar regional standards are being translated into device-level requirements for fail-safe indication and automated sectionalizing compatibility.
- SAIDI and customer-minutes targets are shortening tolerance for manual troubleshooting. Targets set at jurisdictional levels are compelling operators to prioritize solutions that demonstrably reduce in-field response times.
- Hardware is inexpensive, but system value is not. Medium-voltage fault indicators remain low-cost per unit; however, value accrues through integration, remote diagnostics, and lifecycle services — a subtle but material shift in procurement evaluation criteria.
Strategic implications for 2026 executive decisions
- Prioritize interoperability and data models. Devices that support open protocols and provide clear telemetry into DA and OMS systems offer more scalable value and reduce long-term vendor lock-in risk.
- Pilot to learn, not just to validate. Structure pilots to capture restoration-time metrics, false-trip rates, and the operational lift required for remote diagnostics — gate subsequent rollouts on measurable KPI improvements.
- Value lifecycle services over penny-per-unit savings. Low upfront hardware cost can obscure higher lifecycle costs. Evaluate vendors on support SLAs, field-service coverage, and firmware/analytics roadmaps.
- Design procurement around risk and compliance. Factor regulatory timelines into procurement lead times and include contractual clauses for performance and compliance updates linked to regulatory changes.
- Monitor consolidation and M&A signals. Given the moderate concentration levels, expect strategic acquisitions by larger control-equipment players seeking to round out distribution automation stacks — an important factor for long-term partnership selection.
How PW Consulting can accelerate your 2026 program
- Custom vendor shortlists and technical due diligence tailored to your network topology and reliability targets.
- End-to-end pilot design and independent field-validation services to convert technology trials into deployment-ready configurations.
- Regulatory-mapping workshops that translate jurisdictional reliability requirements into procurement specifications and contractual language.
- TCO and ROI models calibrated to your outage cost buckets, enabling defensible CAPEX/ OPEX decisions.
This preview is intended to guide the early-stage decisions you will face in 2026: vendor selection priorities, pilot design parameters, and procurement evaluation criteria. PW Consulting’s full Fault Indicators Market report contains the granular segmentations, regional and application-level breakdowns, company scorecards, and downloadable models necessary to implement these recommendations. For utilities, OEMs and investors preparing for the next wave of distribution modernization, that detailed intelligence is the difference between speculative planning and executable strategy.
To obtain the full dataset, vendor benchmarking, and deployment playbooks, please visit our report landing page or contact your PW Consulting advisor for a personalized briefing and data license.
For detailed analysis of this topic, please visit the official page: Fault Indicators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com