

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Cycloidal Gear Reducers Market to Hit USD 3,310.4 Million by 2032, Growing at a 5.34% CAGR

Cycloidal Gear Reducers Market: Strategic Signals for 2026 Decision-Makers
Executive summary
PW Consulting’s new Cycloidal Gear Reducers Market report—anchored to a 2025 base year and projecting through 2032—provides actionable intelligence designed for executives making strategic choices in 2026. Our analysis combines a detailed historical review (2020–2025), a robust forecasting model, and operator-level competitive insight to clarify where value will form and how risks will propagate across the value chain.
Cycloidal Gear Reducers Market
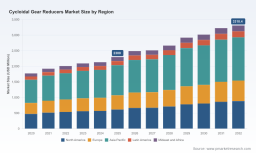
Key topline metrics: the global cycloidal gear reducers market is modeled at approximately USD 2,300.0 Million in 2025 and is forecast to reach roughly USD 3,310.4 Million by 2032, implying a compound annual growth rate (CAGR) of 5.34% over the 2026–2032 forecast horizon. The short-term step into 2026 projects a market near USD 2,489.2 Million, underscoring both continuity and acceleration in demand drivers for precision motion control solutions.
Cycloidal Gear Reducers Market
Why this matters for 2026 strategic planning
For 2026 planning cycles, three imperatives emerge from our analysis:
Cycloidal Gear Reducers Market
- Prioritize precision-mechatronics segments where cycloidal designs deliver distinct technical advantages (high torque density, low backlash, shock resilience), especially as robotics and automated systems proliferate across logistics, factory automation, and machine tool ecosystems.
- Align commercial and supply chain strategies with evolving certification and export regimes: regulatory tailwinds and constraints are already affecting product certification, customs clearance, and licensing for high-precision machine components.
- Differentiate through application-specific engineering or service bundles—OEMs who pair reducers with integrated controls, lifecycle services, or tailored mechanical interfaces capture higher margin pools as the market matures.
Market trajectory and drivers (data-driven perspective)
The historical series from 2020 through 2025 reveals steady expansion from a market base under USD 1.8 billion to the 2025 level of USD 2.3 billion. The forecast to 2032 reflects continued adoption across robotics, industrial machinery, and emergent mobility/AGV platforms. At a modeled CAGR of 5.34%, growth reflects a mix of replacement demand in heavy-duty automation, greenfield automation in emerging manufacturing hubs, and escalating standards for positional accuracy in collaborative and service robotics.
Demand-side drivers identified in the report include:
- Robotics acceleration—both industrial and collaborative—where zero-backlash, compact high-torque solutions are mission critical.
- Factory automation and machine tool modernization, where retrofits and new-install projects seek robust reducers tolerant of shock and cyclical loading.
- Specialty processing and high-performance chemical applications where bespoke gearbox materials and sealing solutions increasingly matter.
On the supply side, our synthesis highlights manufacturing intensity in specialist hubs, continuing investment in precision machining and heat-treatment capabilities, and a progressive shift toward modular, assembly-line friendly reducer platforms that lower integration cost for OEMs.
Competitive landscape: what leading firms signal
The cycloidal reducer space is moderately consolidated—with the top three players controlling a meaningful share and the top five increasing that concentration. Our market concentration analysis estimates CR3 at roughly 40% and CR5 near 50%, a structure that rewards both scale and differentiated engineering.
Leading vendors profiled in the report offer instructive strategic postures:
- Sumitomo Drive Technologies (Japan): Focused on high-precision, zero-backlash Fine Cyclo® series—a playbook centered on premium robotic and automation OEMs where product reliability commands price premium.
- Nabtesco Corporation (Japan): Strength in RV-series precision reducers and continuous catalogue tuning—an indicator of product platform refinement and close OEM relationships. Nabtesco’s January 2026 product catalogue revision underlines ongoing technical spec evolution as a competitive lever.
- Nidec Drive Technology / KINEX (United States): Emphasizes shock-load resistance and dependable positioning; a strong industrial-automation and motion-control channel focus.
- Cone Drive, Spinea AG, GAM (US/Switzerland/Germany): Each offers regionally respected precision motion portfolios—these firms balance niche mechanical design with quality certifications and service agreements to capture aftermarket value.
- Onvio, DieQua and a growing cohort of Chinese and Taiwanese manufacturers (e.g., HONPINE, SigGear, Tailong, Guomao, Transcyko): These suppliers focus on cost-competitive precision, local assembly ecosystems, and rapid application-specific customization. Recent industry activity—Transcyko’s planned exhibition at Chinaplas 2026 and HONPINE’s technical publications—reflects rising commercial and technical assertiveness among regional producers.
Collectively, company strategies indicate two viable pathways for competitive advantage: (1) premium differentiation through performance and validation for high-end robotics and aerospace-adjacent applications, and (2) cost and integration leadership targeting high-volume industrial automation and process-machinery retrofit markets.
Regulatory, trade, and market 'noise' influencing 2026
Beyond pure demand-supply fundamentals, several non-technical forces shape near-term investment decisions:
- Certification and safety regimes: New EU-level interpretations—particularly around PL certification and ISO 13849-1 performance level (PLd) expectations—are changing compliance roadmaps for harmonic and related reducer technologies. Firms should reassess product roadmaps to minimize customs and certification friction.
- Export controls and machine-tool licensing: Recent tightening of export controls in certain markets for high-precision multi-axis CNC machinery introduces procurement lead-time risk for manufacturers that source precision machine tools offshore.
- Regional trade dynamics and show floor visibility: Events and pavilion expansions that spotlight smart-factory and AI-enabled manufacturing offer rapid lead-generation opportunities for suppliers; conversely, they increase competitive intensity for platform adoption in targeted geographies.
- Application-specific technical dissemination: Supplier-published technical guides (e.g., polyurethane mixing gearbox guides) and OEM analyses of AGV components accelerate buyer education—pressuring laggards to upskill in application integration or risk being disintermediated by better-informed systems integrators.
Strategic playbook for 2026 (practical recommendations)
We translate the report’s findings into a concise playbook for decision-makers preparing strategic moves in 2026:
- Portfolio triage: Classify product SKUs into high-performance, application-tuned, and commoditized buckets. Invest selectively in R&D for premium segments while optimizing cost-to-serve in volume channels.
- Regulatory proofing: Fast-track safety and PL-compliance assessments on product lines in scope of evolving EU and export-control rules. Factor certification timelines into 2026 launch calendars.
- Supply chain resilience: Map critical machine-tool and component dependencies; pursue dual-sourcing for key machining and finishing operations, and pre-comply with export licensing where applicable.
- Commercial model innovation: Embed services and predictive maintenance offerings to monetize installed bases and sustain margins as gearbox commoditization picks up pace.
- M&A and partnerships: Pursue bolt-on acquisitions to close capability gaps—especially in precision manufacturing, control integration, or regional distribution that can accelerate market entry without incurring greenfield costs.
What the full report contains (operational depth)
PW Consulting’s comprehensive report goes beyond this executive preview. Inside you will find:
- Detailed historical time series (2020–2025) and our year-by-year forecast model (2026–2032) with scenario sensitivity testing under alternative macro and regulatory assumptions.
- End-use segmentation and application analysis with growth vectors, pricing dynamics, and buyer decision matrices (note: detailed sub-segment data and regional splits are presented in the full report to enable precise go-to-market planning).
- Vendor benchmarking matrix including product feature sets, channel strategies, manufacturing footprints, and recent R&D or product portfolio moves.
- Hands-on commercial playbooks for OEMs, system integrators, and aftermarket service providers—complete with suggested KPIs, contract structures, and launch timing recommendations for 2026.
- Risk register and mitigation templates that translate export-control, certification, and supply disruptions into operational checklists for procurement, legal, and engineering teams.
How to use this analysis in boardroom decisions
Use this report as a decision-support toolkit for 2026 planning cycles. Typical use cases include:
- Capital allocation: Prioritizing capex for capacity expansion versus R&D for high-value reducer platforms.
- Go-to-market sequencing: Determining which geographies and vertical segments should receive commercial investment given regulatory and competitive curves.
- M&A screening: Sourcing targets with complementary manufacturing capability, market channel access, or software-enabled service offerings.
- Contract negotiation: Setting negotiation benchmarks based on supplier concentration and differentiated value propositions.
To preserve the actionable core of our findings while encouraging stakeholder verification and scenario-based planning, we have intentionally withheld granular segment-by-segment figures in this release. The full dataset, model files, and vendor profiles are available in the complete market report and accompanying data annex for subscribers and licensed purchasers.
Next steps
If your organization is preparing strategic moves—capex, acquisitions, product launches, or compliance programs—for 2026, PW Consulting’s Cycloidal Gear Reducers Market report will supply the quantitative basis and practical roadmaps to de-risk decisions and capture value. Contact our advisory team to arrange a briefing, request the dataset, or commission a tailored workshop that aligns this market intelligence with your corporate KPIs.
For detailed analysis of this topic, please visit the official page: Cycloidal Gear Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com