

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Commercial Soda Water Dispenser Market to Surge to USD 344.8 Million by 2032 at a 6.98% CAGR

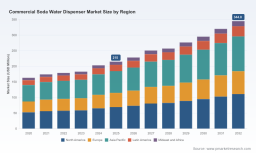
Commercial Soda Water Dispenser Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting’s latest Commercial Soda Water Dispenser Market report (base year 2025; historical 2020–2025; forecast 2026–2032) delivers the actionable intelligence executives need to set strategy in 2026. The market has expanded from USD 163.15 Million in 2020 to USD 215.0 Million in 2025 and is forecast to reach USD 344.8 Million by 2032, growing at a 6.98% CAGR through the projection window. This briefing highlights the report’s strategic value, the operational playbook we recommend for the coming 12–18 months, and the competitive and regulatory dynamics that will shape winners and laggards — while intentionally withholding the granular segment tables and regional splits that are available in the full report.
Commercial Soda Water Dispenser Market
Market snapshot: structural growth, technology acceleration
-
Recovery and premiumization. The post‑pandemic rebound in on‑premise beverage consumption, combined with premiumization of flavored and sparkling water offerings, is a core demand driver. Operators are investing in flexible, compact dispensers to support differentiated beverage menus.
Commercial Soda Water Dispenser Market -
Technology-led differentiation. IoT, AI‑enhanced maintenance, contactless interfaces and modular flavor architectures are shifting product value from simple dispense mechanics to data, uptime and user experience.
Commercial Soda Water Dispenser Market -
Fragmented competitive landscape. The market concentration remains low (CR3 ~24.6%; CR5 ~26.2%), pointing to widespread regional OEMs, local fabricators and specialized service providers — and therefore plentiful consolidation and partnership opportunities.
-
Input and compliance pressures. Raw material and operating cost volatility (notably CO2 prices, which reached 0.76 USD/kg in North America in March 2026) and tighter certification standards are squeezing design and procurement choices.
Why this report matters to 2026 boardrooms
-
Investment prioritization: Our model translates projected market growth (2026 through 2032) into revenue scenarios and break‑even horizons for product investments, new manufacturing lines and service expansions.
-
M&A and partnership playbook: Given low top‑player concentration, the report identifies strategic carve‑outs, OEM acquisition archetypes and integration playbooks that maximize route‑to‑market and service synergies.
-
Commercial models for service and consumables: We map the long‑tail economics of subscription vs. outright sale for dispensers, plus the lifetime value of consumables and CO2 supply agreements under multiple price scenarios.
-
Compliance and product‑in‑market risk: The report consolidates regulatory obligations (NSF/UL certification requirements, ASSE 1022 backflow standards, CHC 2025 certification implications) into a practical compliance roadmap for R&D and procurement teams.
Competitive landscape — qualitative analysis of core players
The vendor ecosystem mixes established global brands, specialized hospitality suppliers and regional OEMs. A selective view of companies covered in the report offers a sense of competitive positioning without revealing confidential share data.
-
Cornelius (Anoka, MN, USA): A legacy supplier that emphasizes intelligent beverage dispensing platforms. Strengths include brand recognition with large foodservice chains, an installed base that supports after‑sales monetization, and product portfolios that integrate with existing beverage brands.
-
Lancer Worldwide (San Antonio, TX, USA): Known for advanced soft‑drink towers and dispensers tailored to hospitality. Lancer’s focus on hospitality design and serviceability positions it well for premium venues and retrofit projects.
-
Servend (Chicago, IL, USA) and Follett Products (Crystal Lake, IL, USA): Both offer certified commercial equipment with specific features such as integrated ice handling, high throughput designs and NSF/UL‑certified models that appeal to regulated customers.
-
Emerging Asia and India OEMs (including manufacturers from India and China): These suppliers are competitive on cost and customization, and many provide OEM/OEM‑to‑brand arrangements. Their strengths are rapid product iteration and localized manufacturing footprints — important for price‑sensitive segments and for mitigating tariff exposure.
Recent industry moves underscore the shift to software-enabled and modular systems. Notable developments: Coca‑Cola’s Freestyle platform refresh (May 2026) and prior Smart Dispense initiatives (March 2025), PepsiCo’s beverage launches tailored for dispenser networks (March 2024), and several hospitality pilots deploying modular, IoT‑enabled units (mid‑2025). These validate the premium placed on flexibility, data and the customer interface.
Key dynamics that will decide market leadership in 2026
-
Supply‑chain and input cost management: Tariff pressure on stainless steel components and volatile CO2 costs force suppliers to redesign for lower bill‑of‑materials, to localize sourcing, or to pass costs to operators through service contracts.
-
Certification as market access: NSF/UL and ASSE 1022 requirements are de facto market gates in many commercial channels. Certification timelines must be built into product development roadmaps to avoid go‑to‑market delays.
-
Software and services as differentiators: IoT‑enabled uptime guarantees, remote diagnostics and flavor usage analytics create recurring revenue streams and sticky customer relationships.
-
Fragmentation creates M&A runway: The current CR3/CR5 levels indicate substantial scope for consolidation, roll‑ups and distribution partnerships to create national footprints out of regional suppliers.
Operational playbook — eight tactical moves for 2026
-
Hedge critical inputs: Negotiate forward CO2 contracts or partner with local gas suppliers; qualify alternative suppliers and explore CO2 reclamation technologies for high‑volume venues.
-
Embed certification early: Make NSF/UL and ASSE 1022 design checks mandatory at prototype stage; secure third‑party certification partners to compress approval timelines.
-
Accelerate IoT pilots: Deploy a fleet pilot (50–200 units) with predictive maintenance and telemetry to validate service economics and reduce total cost of ownership for customers.
-
Re‑engineer for cost and modularity: Redesign core systems to allow modular flavor packs, simplified service modules and plastic/alternative materials where certification and hygiene allow.
-
Build consumables economics: Launch bundled CO2 and syrup subscription offers; model breakage and downtime costs into pricing to convert CapEx buyers to recurring revenue contracts.
-
Pursue targeted tuck‑ins: Prioritize acquisitions that add channel reach or service capabilities; integrate back‑office and field service systems to realize synergies within 18 months.
-
Design for retrofit: Create retrofit kits for existing installations to accelerate penetration without full replacement cycles.
-
Leverage brand partnerships: Collaborate with beverage brand owners for co‑branded dispensers and exclusive flavor packs that strengthen operator margins and customer loyalty.
How executives should use the full PW Consulting report
The full report translates high‑level trends into executable deliverables: a market sizing workbook (USD Million, base 2025), scenario P&L and cash flow templates for new product investments, a supplier risk heat map, a regulatory compliance checklist, technology evaluation scoring and a 12–month implementation roadmap. It also contains the granular segment data, regional breakdowns and downloadable models that boards and investment committees require to finalize capex allocation, M&A targets and go‑to‑market targets. We intentionally withhold these segment tables in this briefing to preserve the signal that underscores their value.
90‑day boardroom agenda
-
Week 0–4: Ratify strategy — agree on target segments, pricing approach and service model (CapEx sale vs. subscription) using the report’s executive summary and scenario outputs.
-
Month 2: Start pilot — deploy an IoT fleet pilot with a small set of key customers to validate uptime SLAs and service economics.
-
Month 3: Procurement and certification sprint — secure key supplier contracts, fast‑track certification and finalize retrofit product specs.
Conclusion — where to place your bets in 2026
2026 will separate companies that treat dispensers as “hardware items” from those that view them as platforms for recurring revenue, data and branded experiences. The market’s steady mid‑single digit CAGR and the low concentration ratio create simultaneous opportunities for product incumbents to monetize installed bases and for nimble OEMs to scale through partnerships and regionally focused consolidation.
For executives making resource allocation decisions this year, the immediate priorities are clear: secure input cost exposure, lock down certification roadmaps, establish IoT proof points and design a service strategy that converts one‑time equipment sales into predictable recurring revenue. PW Consulting’s full Commercial Soda Water Dispenser Market report provides the detailed segmentation, scenario models and supplier benchmarks needed to operationalize these priorities — including the granular data and downloadable tools that are not included in this summary.
To access the full dataset, segment tables and Excel models that underpin the scenarios referenced here, visit the PW Consulting report page and request the complete Commercial Soda Water Dispenser Market report. Our consultants are available for board briefings, custom sensitivity analysis and implementation support.
For detailed analysis of this topic, please visit the official page: Commercial Soda Water Dispenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com